For Buyers
Will We See a Surge of Homebuyers Moving to the Suburbs?
As remote work continues on for many businesses and Americans weigh the risks of being in densely populated areas, will more people start to move out of bigger cities? Spending extra time at home and dreaming of more indoor and outdoor space is certainly sparking some interest among homebuyers. Early data shows an initial trend in this direction of moving from urban to suburban communities, but the question is: will the trend continue?
According to recent data from Zillow, there is a current surge in urban high-end listings in some larger metro areas. The month-over-month increase in these homes going on the market indicates more urban homeowners may be ready to make a move out of the city, particularly at the upper end of the market (See graph below):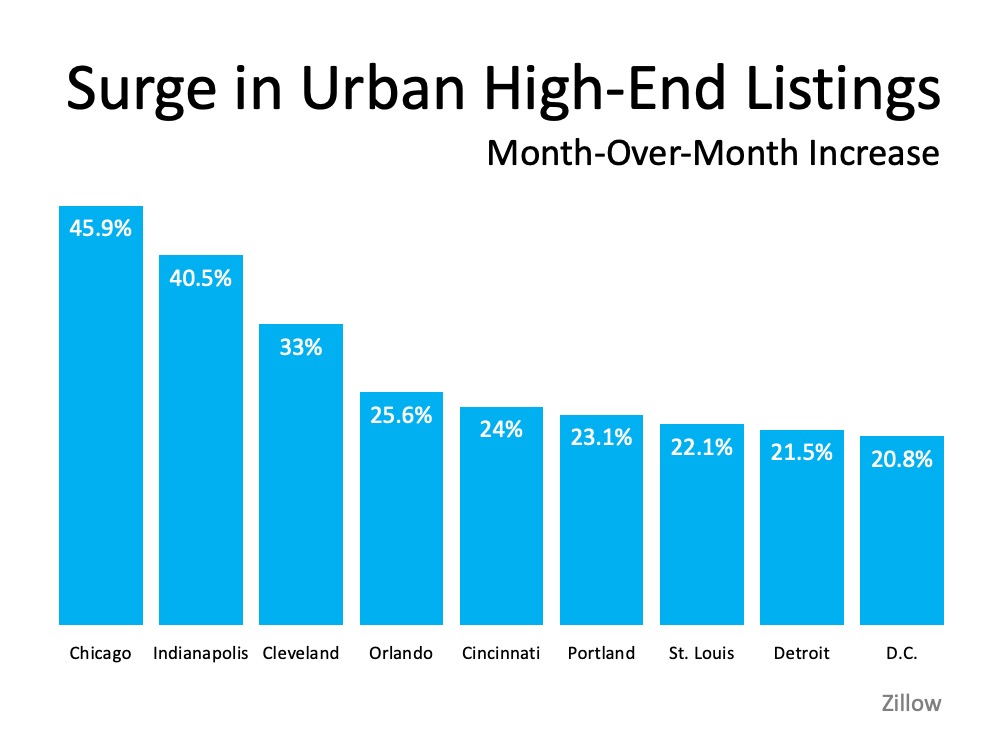
Why are people starting to move out of larger cities?
With the ongoing health crisis, it’s no surprise that many people are starting to consider this shift. A July survey from HomeLight notes the top reasons people are actually moving today:
- More interior space
- Desire to own
- Move from city to suburbs
- More outdoor space
More space, proximity to fewer people, and a desire to own at a more affordable price point are highly desirable features in this new era, so the list makes sense.
John Burns Consulting notes:
“The trend is accelerating faster than anyone could have predicted. The need for more space is driving suburban migration.”
In addition, Sheryl Palmer, CEO of Taylor Morrison, a home building company, indicates:
“Most recently, we’re really seeing a pickup in folks saying they want more rural or suburban locations. Initially, there was a lot of talk about that, but it’s really coming through our buyers today.”
The National Association of Home Builders (NAHB) also shares:
“New home demand is improving in lower density markets, including small metro areas, rural markets and large metro exurbs, as people seek out larger homes and anticipate more flexibility for telework in the years ahead. Flight to the suburbs is real.”
Will the shift pick up speed and continue on?
The question remains, will this interest in suburban and rural living continue? Some, like Lawrence Yun, Chief Economist at the National Association of Realtors (NAR) think the possibility is there, but it is still quite early to tell for sure. Yun notes:
“Homebuyers considering a move to the suburbs is a growing possibility after a decade of urban downtown revival…Greater work-from-home options and flexibility will likely remain beyond the virus and any forthcoming vaccine.”
While much of the energy behind this trend has largely been accelerated by the current health crisis, monitoring the momentum over time is critically important. Businesses are discovering new and innovative ways to function in remote environments, so the shift has the potential to stick. Much like the economic recovery, however, the long-term impact may hinge largely on the health situation throughout this country.
Bottom Line
Early data is showing a shift from urban to suburban markets, but keeping an eye on this trend will help us understand how it will ultimately play out. It may just be a temporary swing in a new direction until Americans once again feel a sense of comfort in the cities they’ve grown to love.
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.
More and more of them are finding it in the adjustable-rate mortgage, or ARM.
The ARM Option
Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.
Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity.
Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home.
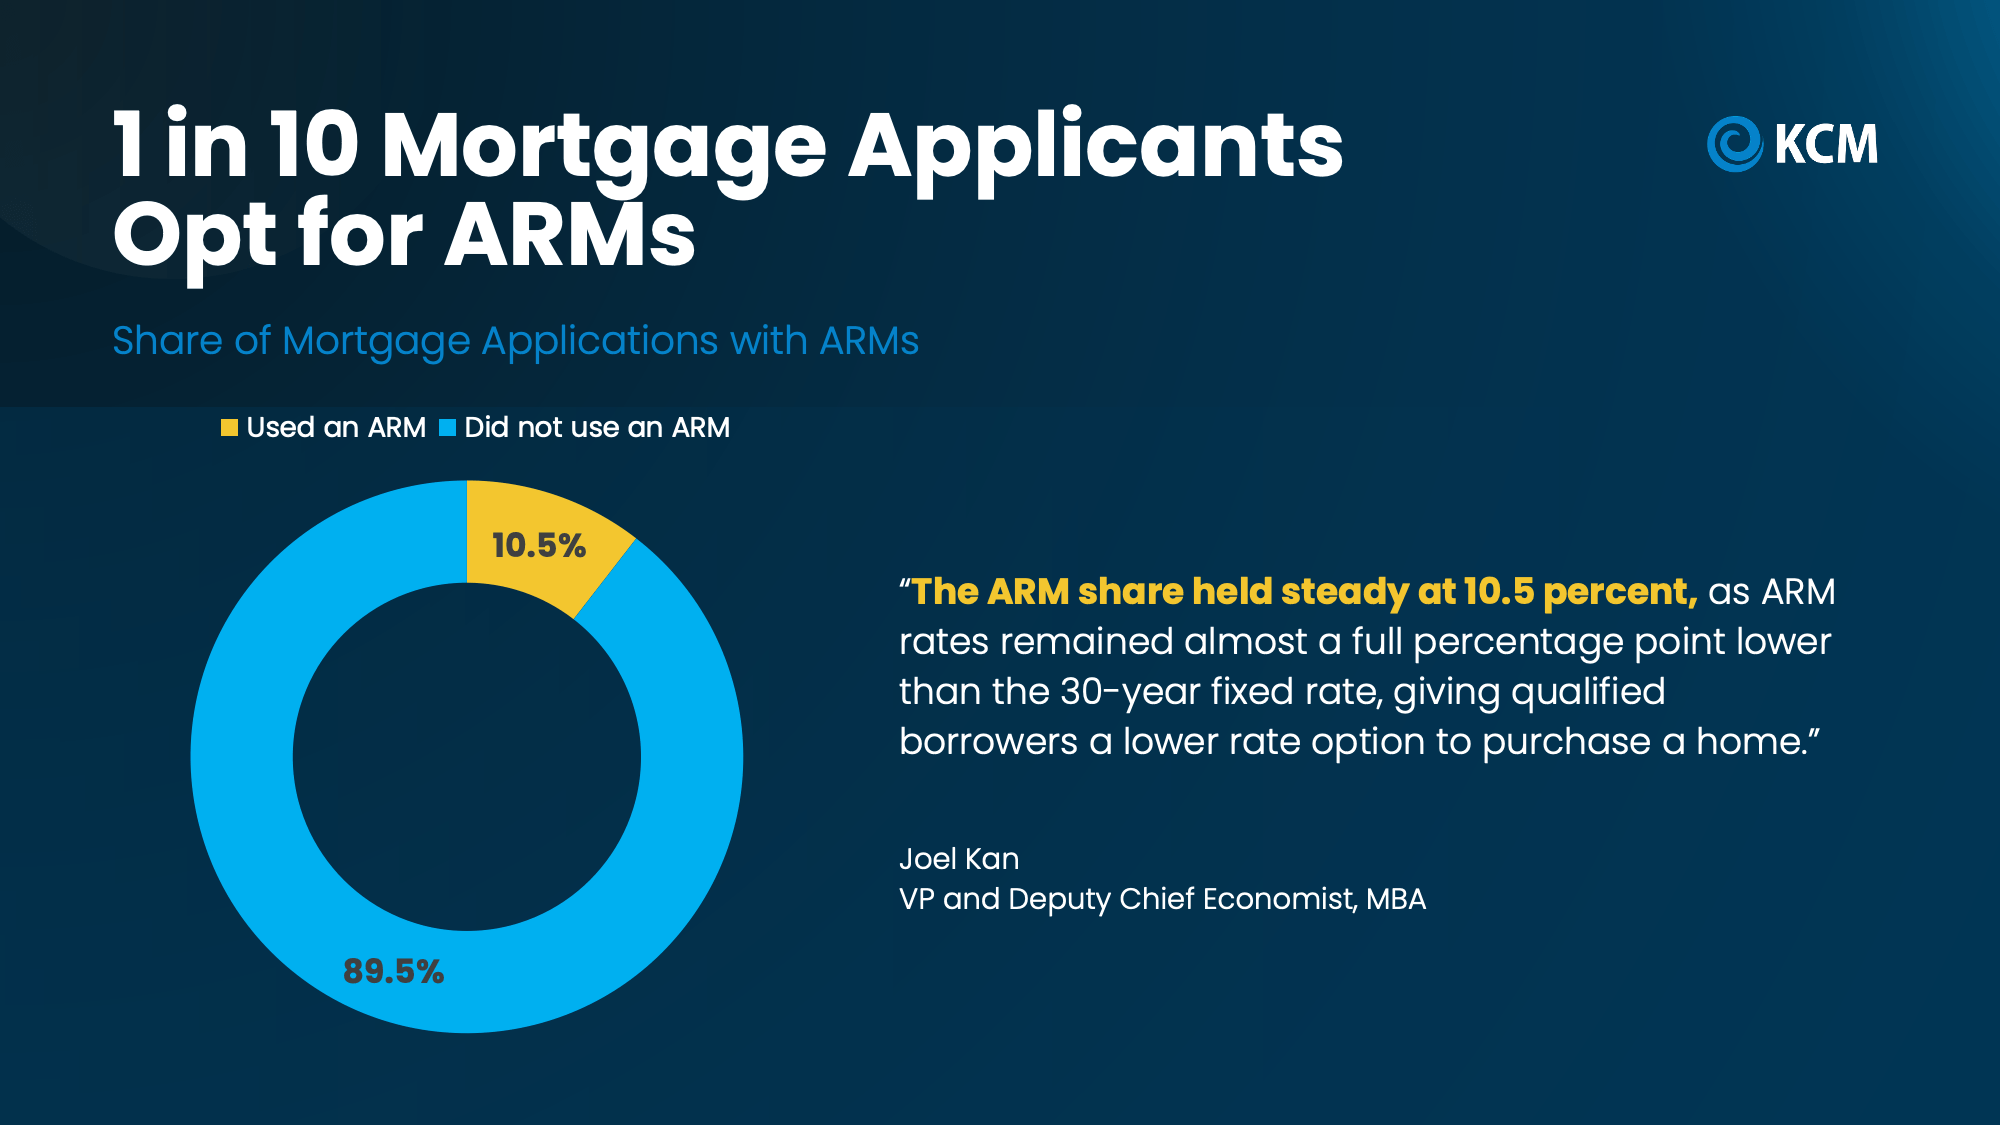
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
If you think you may want to consider this yourself, here’s what you need to know about how it works.
The 5/1 ARM
An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.
The “5” means your introductory rate is locked for the first five years, and the “1” means that the rate can change every year after that. The rate change is called the “reset.” And here’s the really important part.
When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready.
The Upsides and Potential Downsides
To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
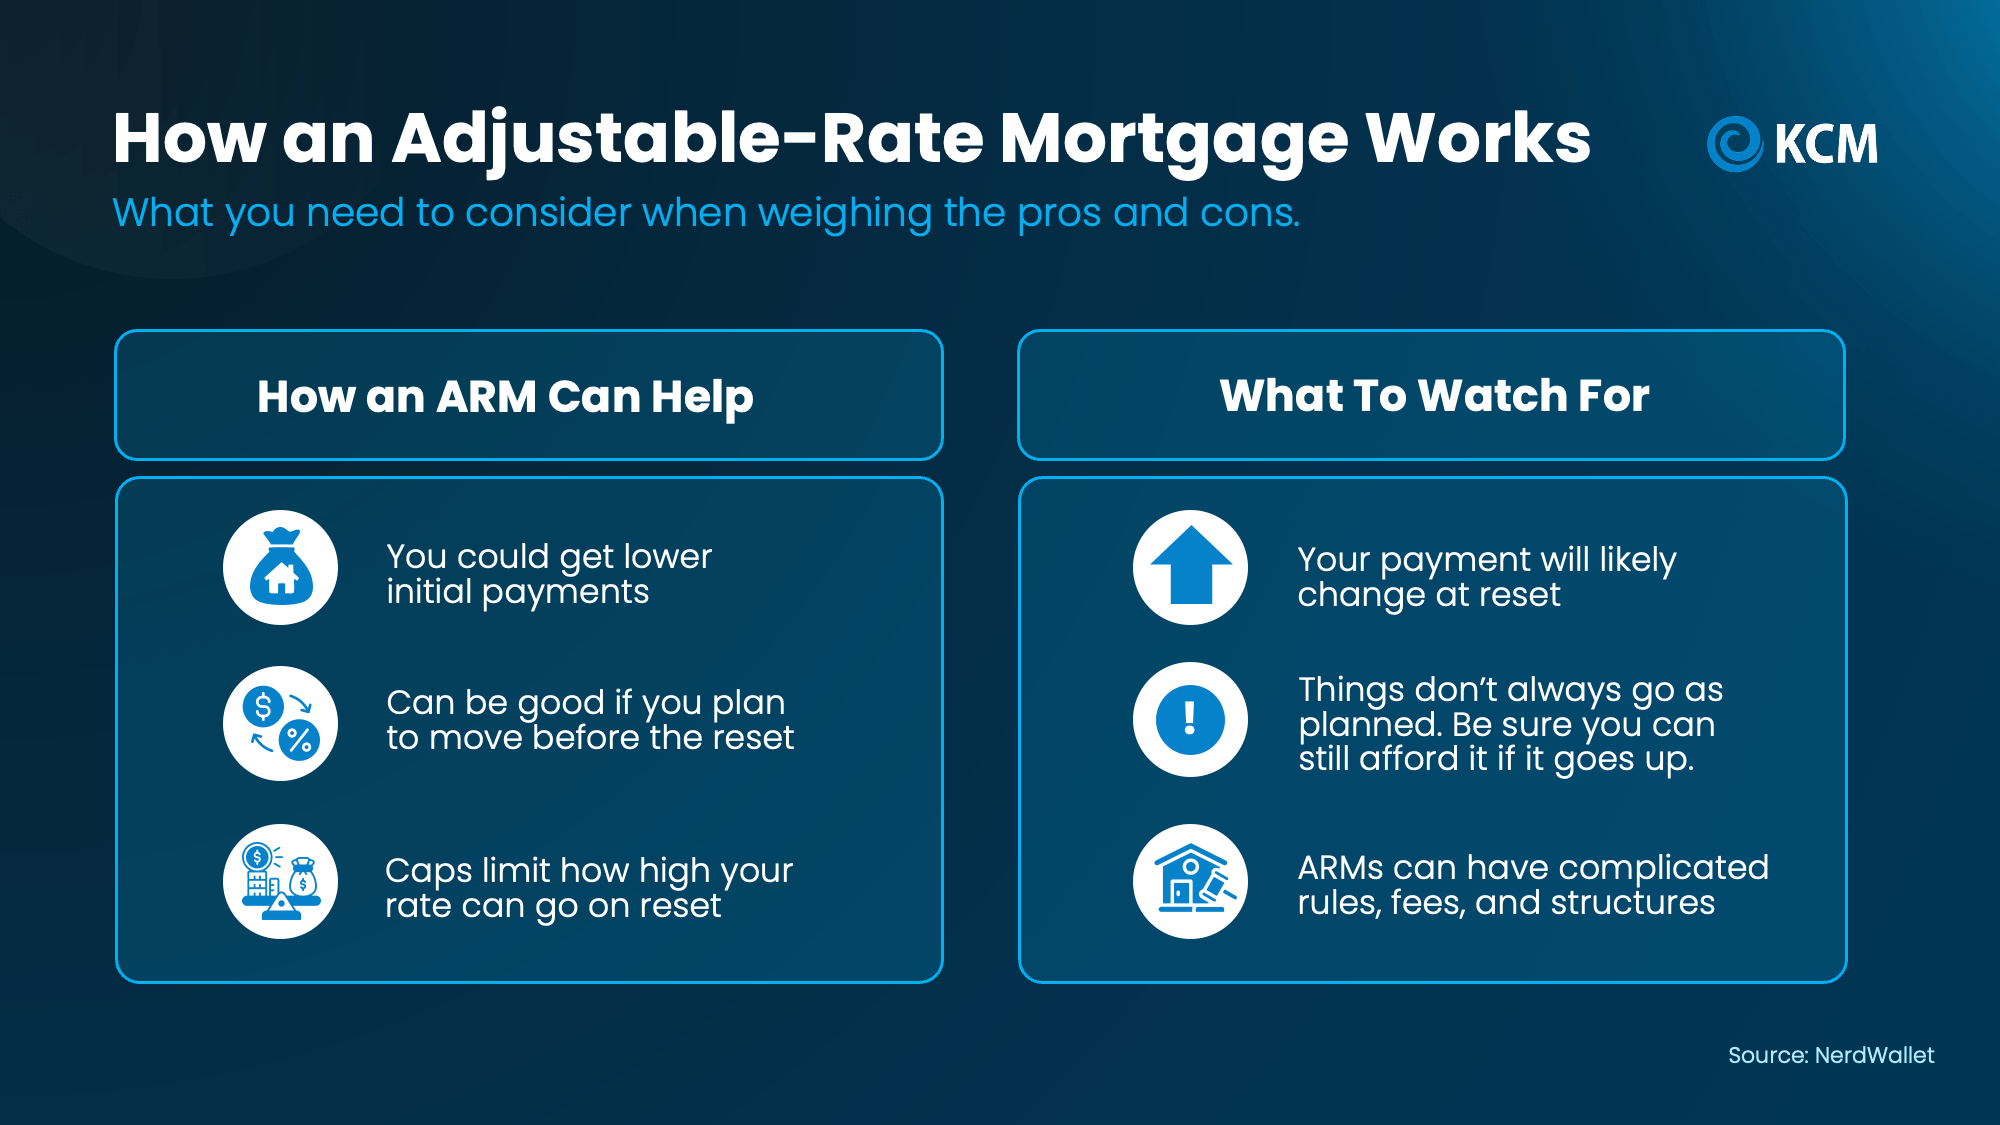
Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.
Be Ready for the Reset
And, if you do go with an adjustable-rate mortgage, just know that you’ll have choices when the reset time arrives. You could:
-
Do nothing and keep your loan in place if the new payment still fits your budget.
-
Refinance into a fixed-rate loan with a payment that never changes.
-
Refinance into another ARM with a new lower rate locked for a specified timeframe.
-
Sell your home.
-
Talk to the loan servicer about assistance or modification.
Remember, a refinance is a brand-new loan that you’ll have to qualify for – even if it’s on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It’s important to keep your credit and finances in “mortgage shape.”
Today’s ARMs Aren’t Like 2008
One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.
But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment.
So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.
Bottom Line
Today’s market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.
Is an ARM a good option for you? Talk to a loan officer to find out.
Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.
One says home prices are falling. The next says they’re still climbing.
So, which one’s right? It comes down to where you live.
What’s Really Going on with Asking Prices
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):
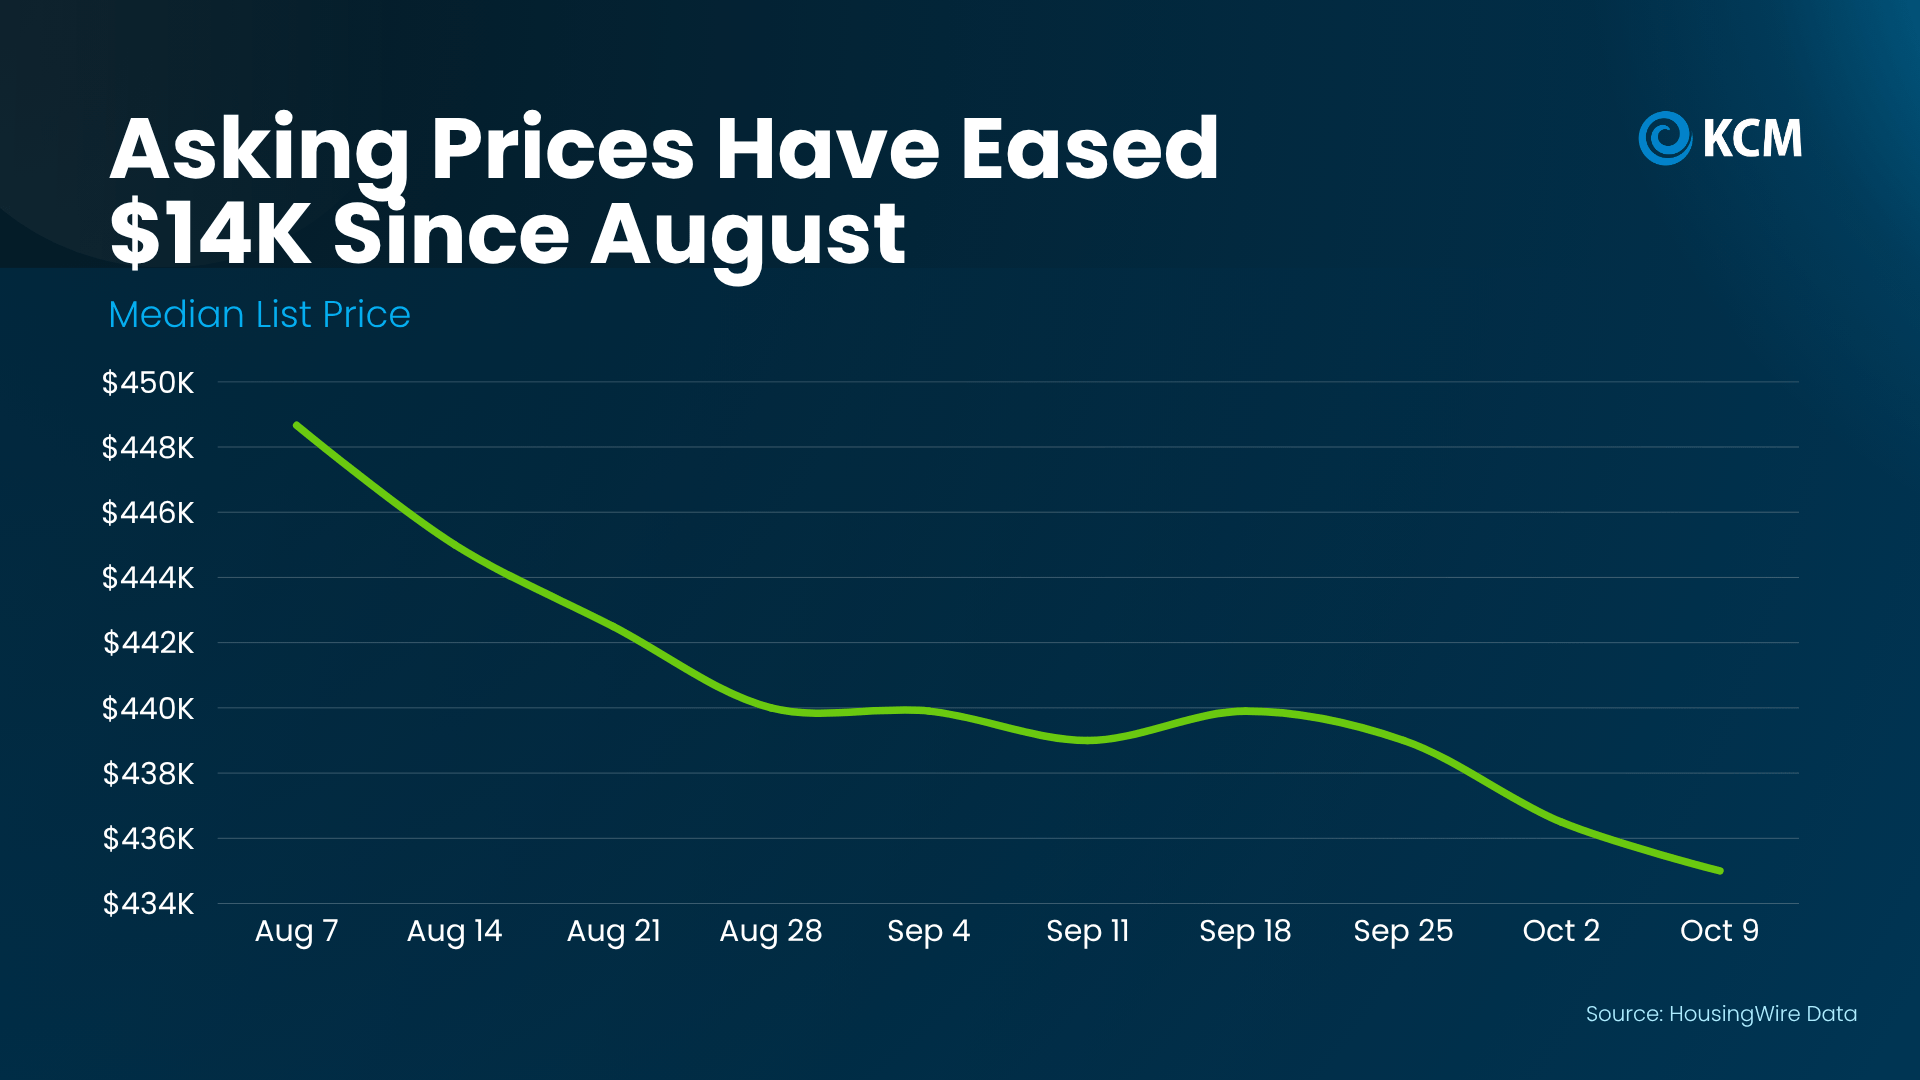
That’s a dip of about 3%, and a lot of it is normal for this time of year.
Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.
Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.
Where You Live Changes Everything
Realtor.com explains:
“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):
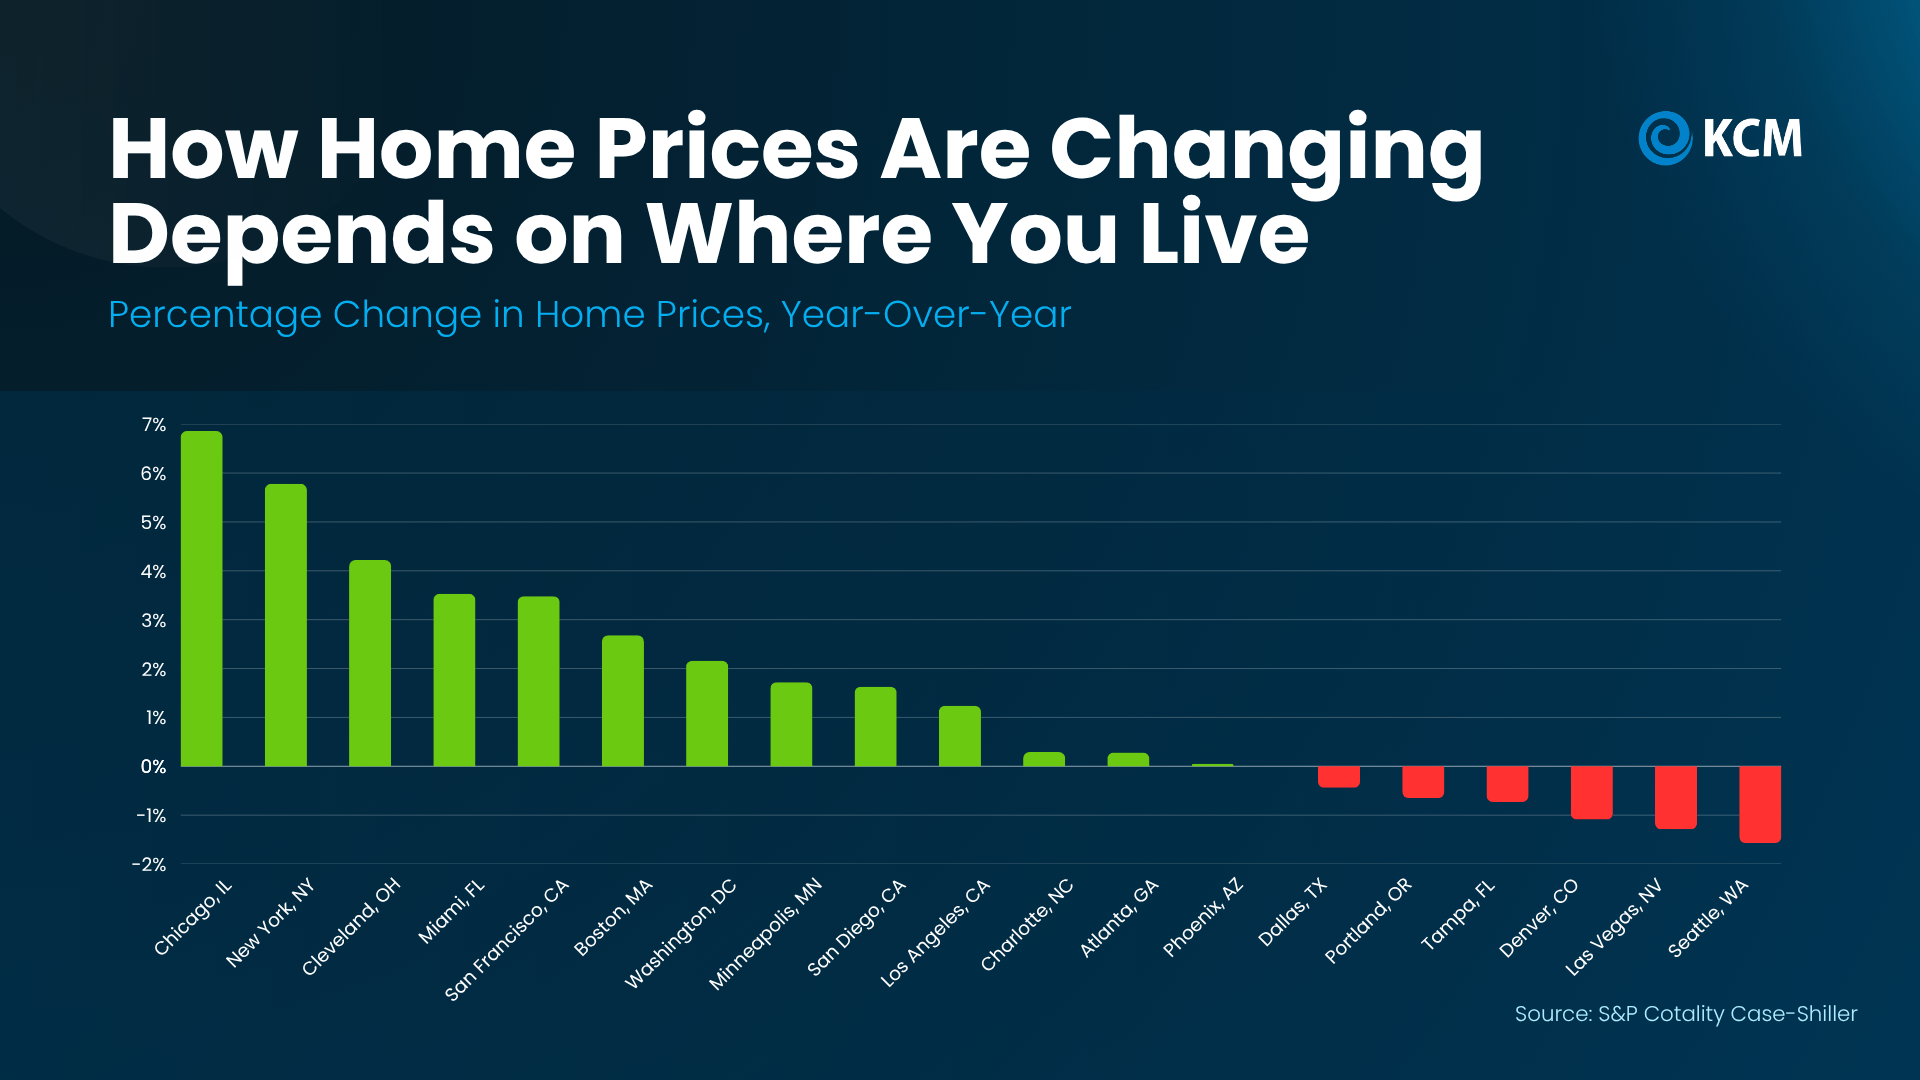
That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.
Why You Don’t Need To Worry About a Crash
Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.
And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):
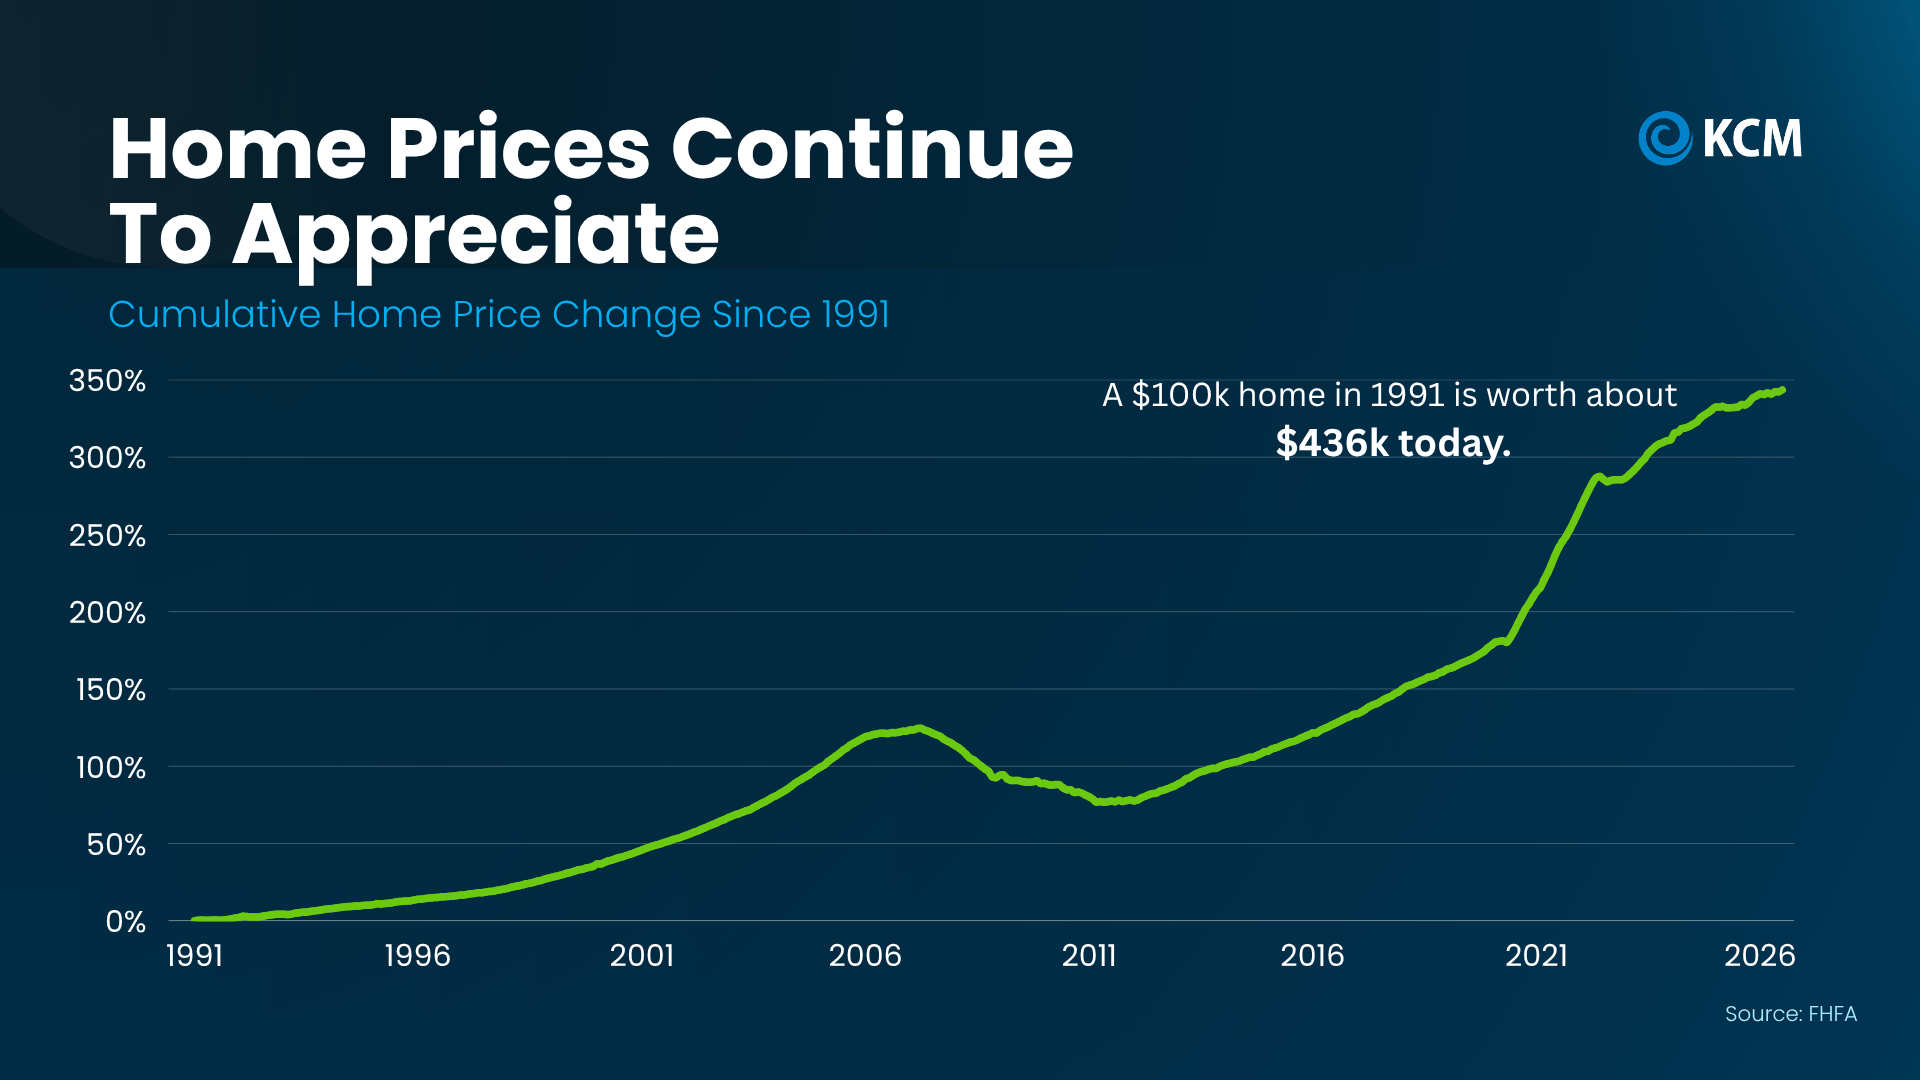
So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.
Bottom Line
National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.
When you picture buying your first home, chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now.
So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo.
Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door.
Condos Can Cost Less Than You Think
According to a recent study by Zillow:
“Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home.”
And depending on where you live, the difference can be much bigger.
Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research (see chart below).
In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area’s median household income.
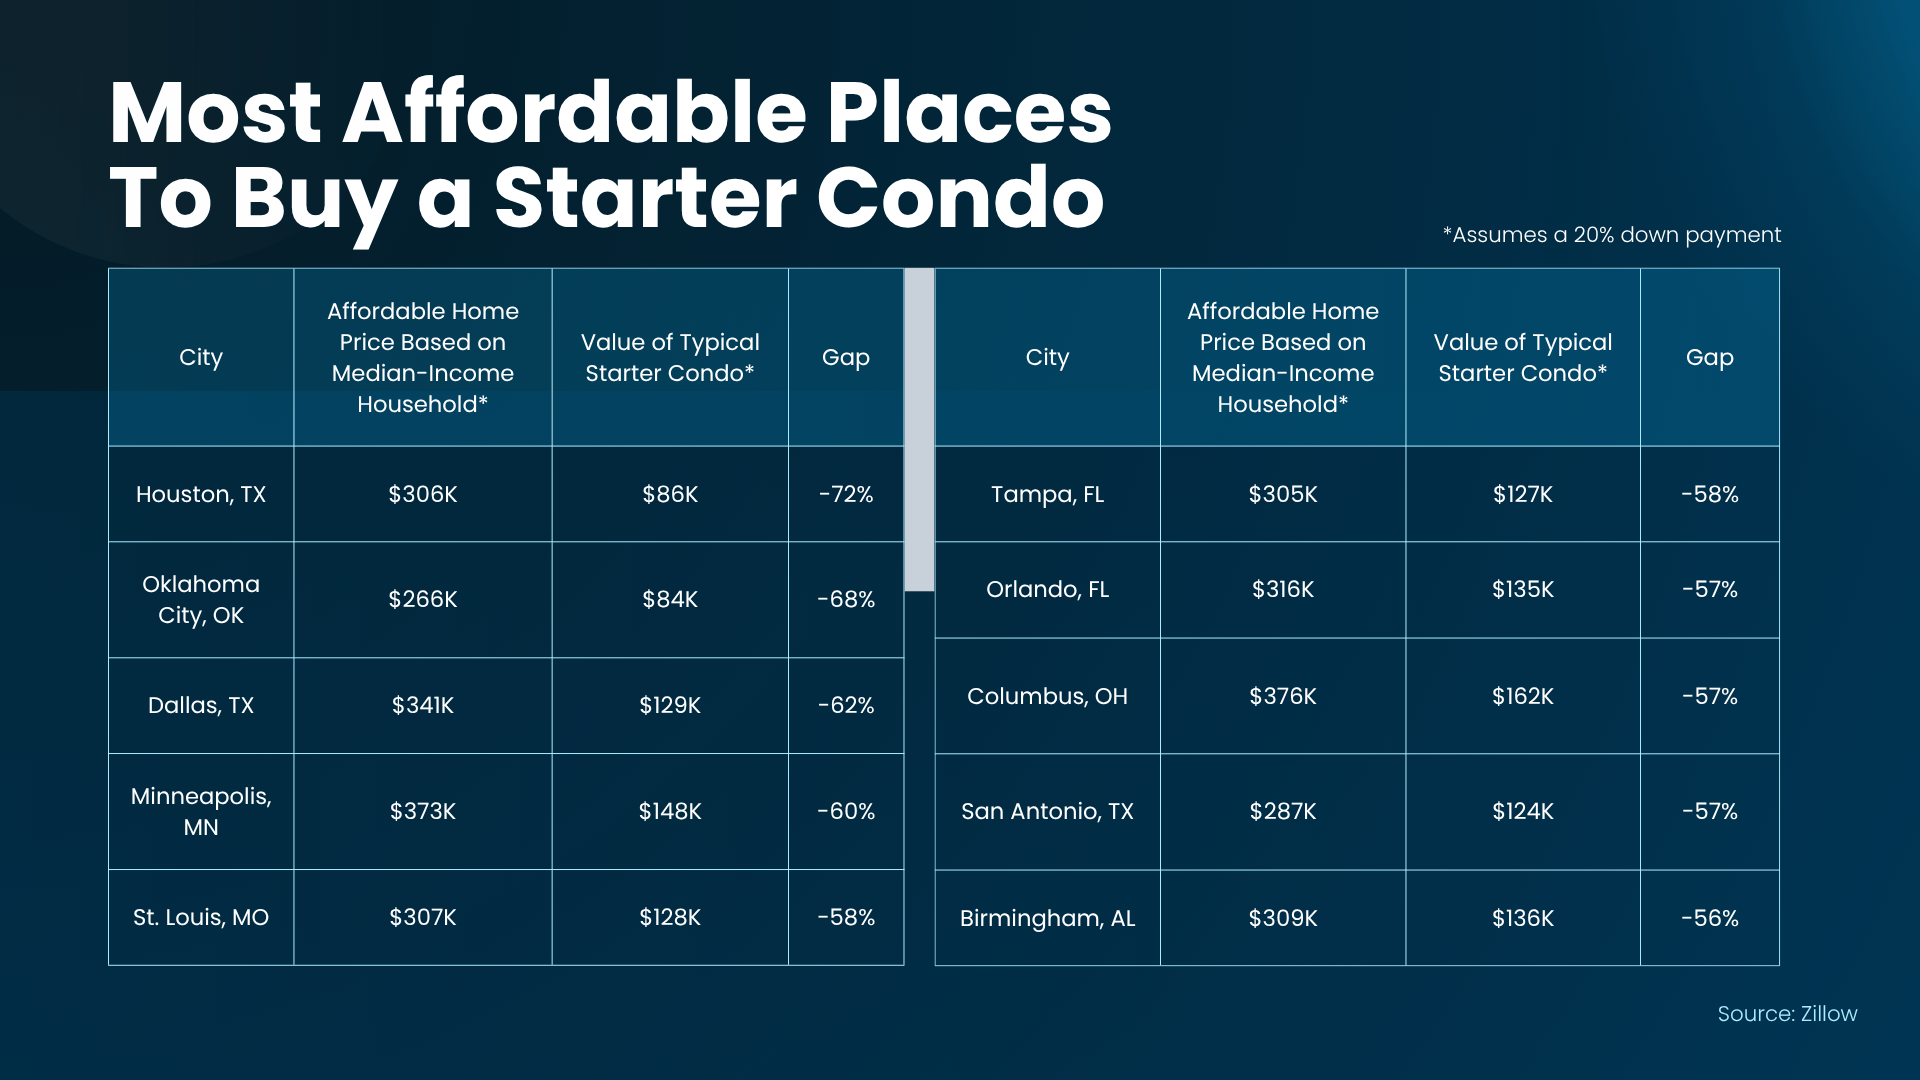
Of course, every market is different. But the bigger point is this: if you’ve only been searching for traditional single-family houses, you may be overlooking some of the more affordable options on the market.
And even if your city didn’t make this list, that’s okay. The trend holds true in many places across the country. Here’s why.
A Condo Could Give You a Different Way In
Part of the reason condos can cost less is pretty straightforward. They’re typically smaller. And less square footage can mean a lower purchase price.
So, if you can make do with a bit less space or you’re coming from a smaller apartment now, this can be a great way in. Plus, on the upside, you won’t have to buy a ton of furniture to fill out a bigger house. You can get a potentially lower price up front and spend less once you move in because you’ll need less new stuff to fill that empty space.
And more buyers are making that trade off on space to offset the current affordability challenges. Ali Wolf, Chief Economist for New Home Source, explains:
“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”
That’s really the heart of it. Looking at condos isn’t necessarily about wanting less. It’s about finding another way to make your move happen with the budget you have.
Don’t Rule Out an Option That Could Work
If you’ve been struggling to find a house you like at a price you can comfortably afford, talk to your agent about adding condos to your search.
You may find something in a neighborhood you thought was outside your budget. You could get access to amenities you wouldn’t otherwise have. And you may be able to become a homeowner sooner rather than waiting for the numbers on a single-family house to work.
While there are trade-offs like shared walls, less outdoor space, and an HOA fee to factor into your monthly budget, maybe that’s worth it if you finally get your own set of keys.
Plus, a lot of the times, a condo community comes with great amenities like pools, gyms, and the condo association handles at least some of the maintenance. Which is closer to what you’re used to from your apartment – it could make the transition to homeowner not just more affordable, but that much easier too.
Bottom Line
The first home you buy doesn’t have to be a single-family house. If affordability has been holding you back, talk to a local agent about expanding your search and see whether a condo could fit the price point you’re looking for.

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today

To Sell or Rent? How To Choose the Best Path for Your House.

Confused by Home Price Headlines? Here’s Why.


-
 Buying Tips3 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 For Sellers3 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability4 weeks ago
Why So Many Sellers Are Cutting Their Price Right Now
-
 Affordability4 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Affordability2 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Affordability3 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Downsize2 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
-
 Affordability2 weeks ago
Why Most People Are Still Glad They Bought a Home
You must be logged in to post a comment Login