Buying Tips
Savings Strategies Every First-Time Homebuyer Needs To Know
What’s the biggest payment you make every month? If you’re a renter, it’s probably your rent.
But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It’s pretty frustrating, especially if you’d like to buy a home someday and you’re trying to build your credit.
The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.
The Problem for Would-Be Buyers
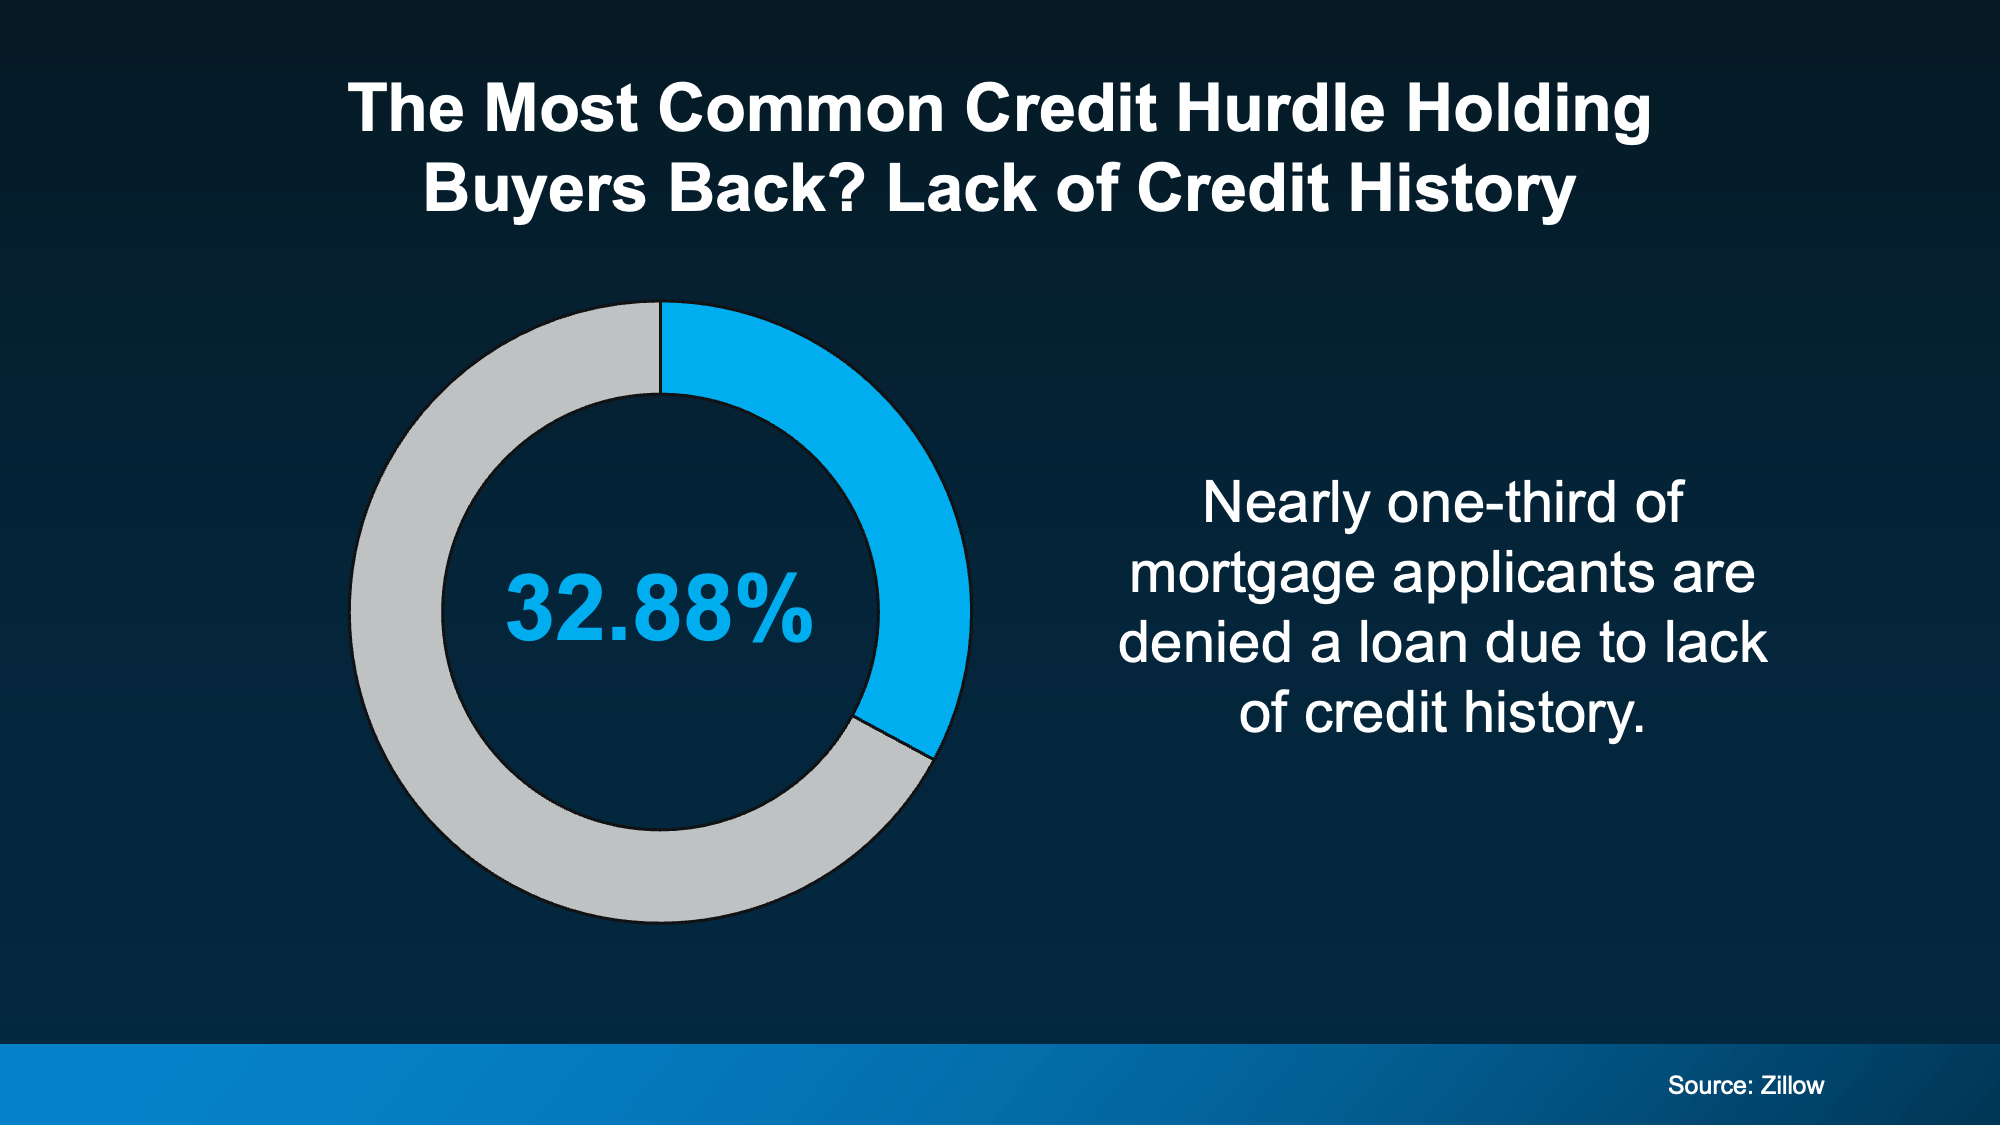
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history – not missed payments or too much debt. Just not enough credit history for a lender to say “yes.”
It’s the most common hurdle would-be buyers have. As Zillow explains:
“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
But there’s finally a way in now that how credit gets measured is changing.
The Good News: Credit Is Getting Broader
As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:
“Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”
Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.
VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.
A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.
Here’s the catch though, you still have to walk through it.
Counting Rental Payment History Is Not Automatic
There are more options available to build credit, but you have to be proactive. Your rent won’t necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.
Here’s how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:
-
Ask your landlord or property manager if your rent is being reported. If it’s not, opt in.
-
If your landlord doesn’t offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.
-
Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.
-
Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don’t apply for a bunch of new credit at once.
-
Don’t close any accounts – even if you have paid them off and don’t use them often.
-
Diversify your profile by getting a secured credit card or becoming an authorized user on someone else’s account to help you build history beyond rent.
These steps take a little time and effort, but it could be worth it if it starts building up your credit history.
Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better.
Even if you’re not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.
Bottom Line
The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.
Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you’re closer to owning a home than you think.
Mortgage rates being back above 7% isn’t exactly the news most people wanted. But it’s changing the market in ways that matter whether you’re buying or selling.
The number of homes for sale is growing faster than it was this time last year. And interestingly, the main reason isn’t a flood of new listings. It’s because homes aren’t selling as quickly.
Here’s why – and what that means if you’re thinking about buying or selling.
Inventory Growth Is Picking Up Steam
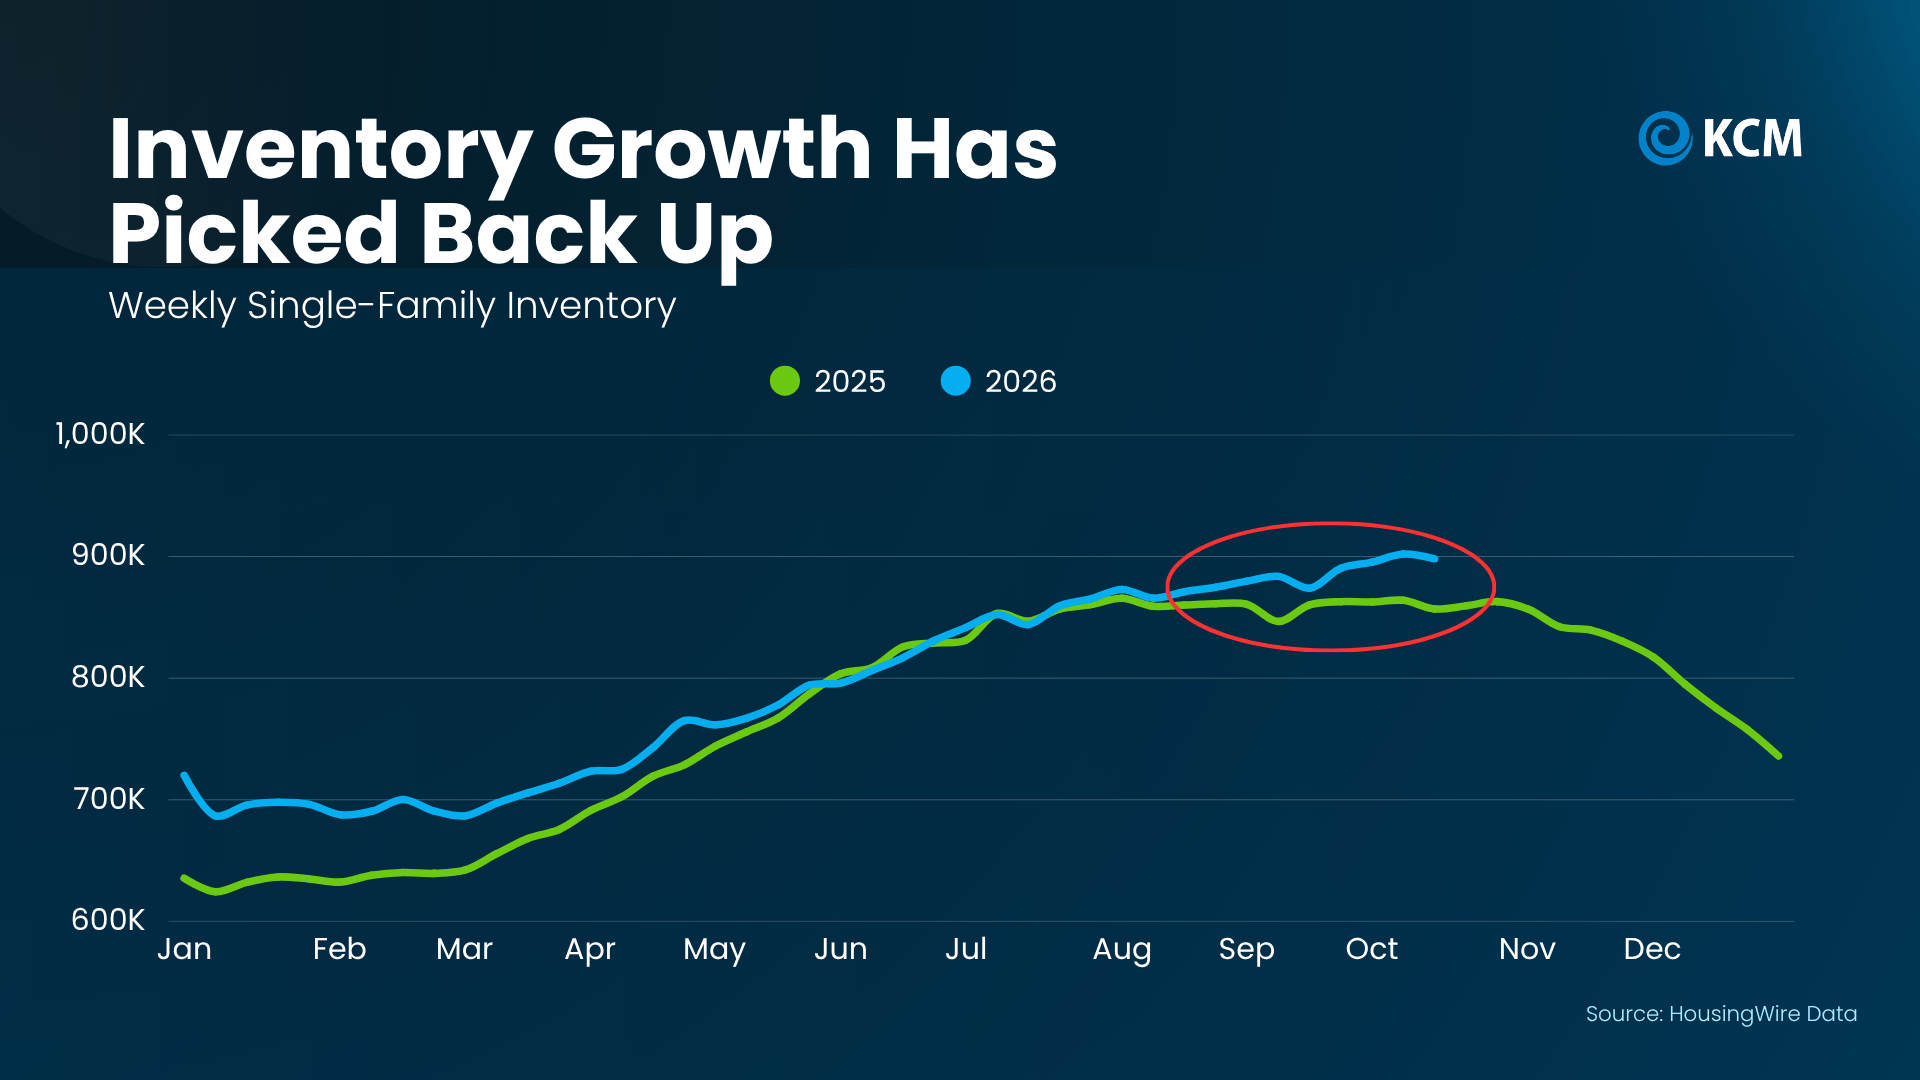
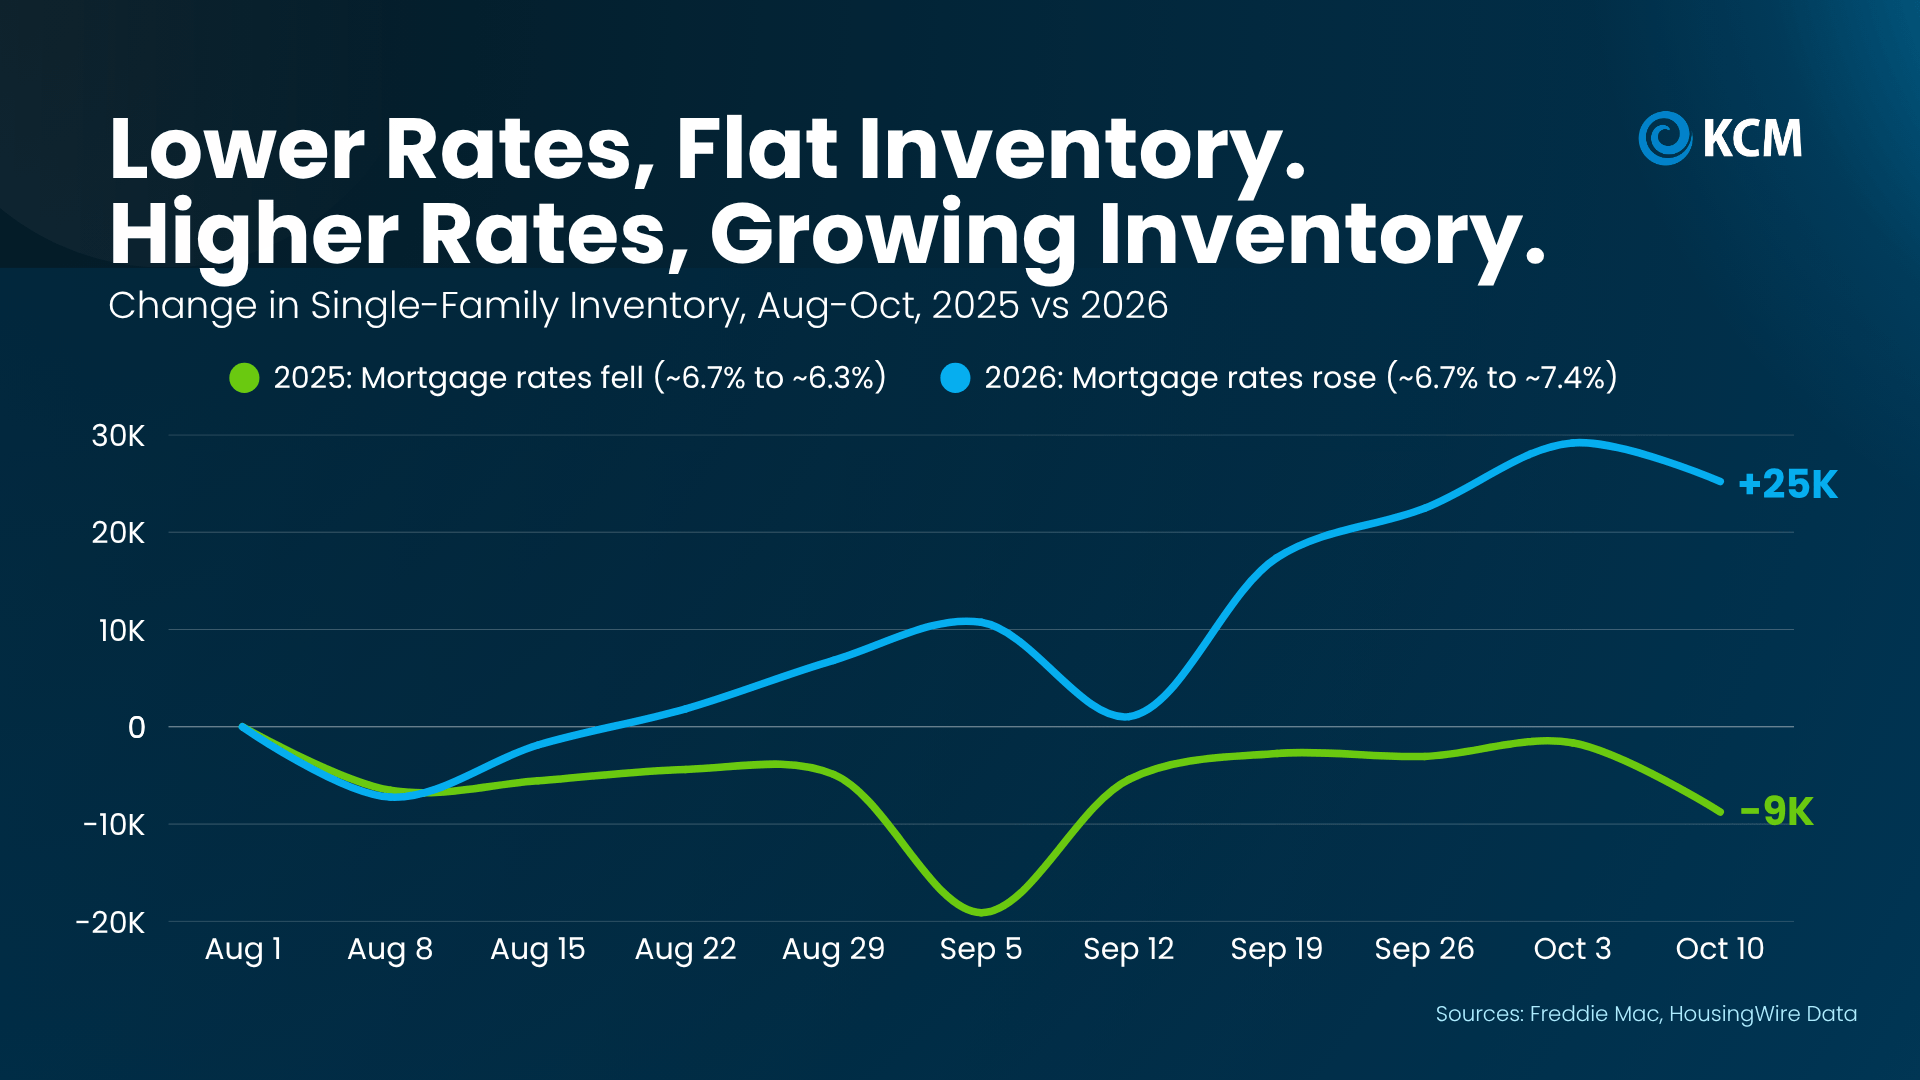
According to HousingWire Data, after inventory growth slowed down for most of the past year, it’s accelerated again in recent weeks. You can see that in the graph below. Just look at the blue line:
And what’s behind this shift might surprise you.
When rates rise, some buyers hit pause. That means fewer homes sell each week. And as those unsold homes stay on the market alongside new listings, the number available starts to grow (see the blue line in the graph below).
Here’s another way to look at it to make it even more obvious. The graph below shows the relationship between rates and inventory. Again, this year is the blue line. Last year? That’s the green.
With rates inching up this year, you can see inventory has grown by about 25k. But when rates went down this time last year, buyers jumped back in, and inventory actually dropped by about 9k.
Logan Mohtashami, Lead Analyst at HousingWire, explains how that’s flipped from 2025 to 2026:
“With mortgage rates over 7%, demand tends to soften and inventory rises . . .”
Homes Are Spending More Time on the Market
Here’s another metric that shows the impact rates are having: time on market. Data from Realtor.com shows the typical home spent 61 days on the market this September. Back in September 2021, it was just 41 days (see graph below):
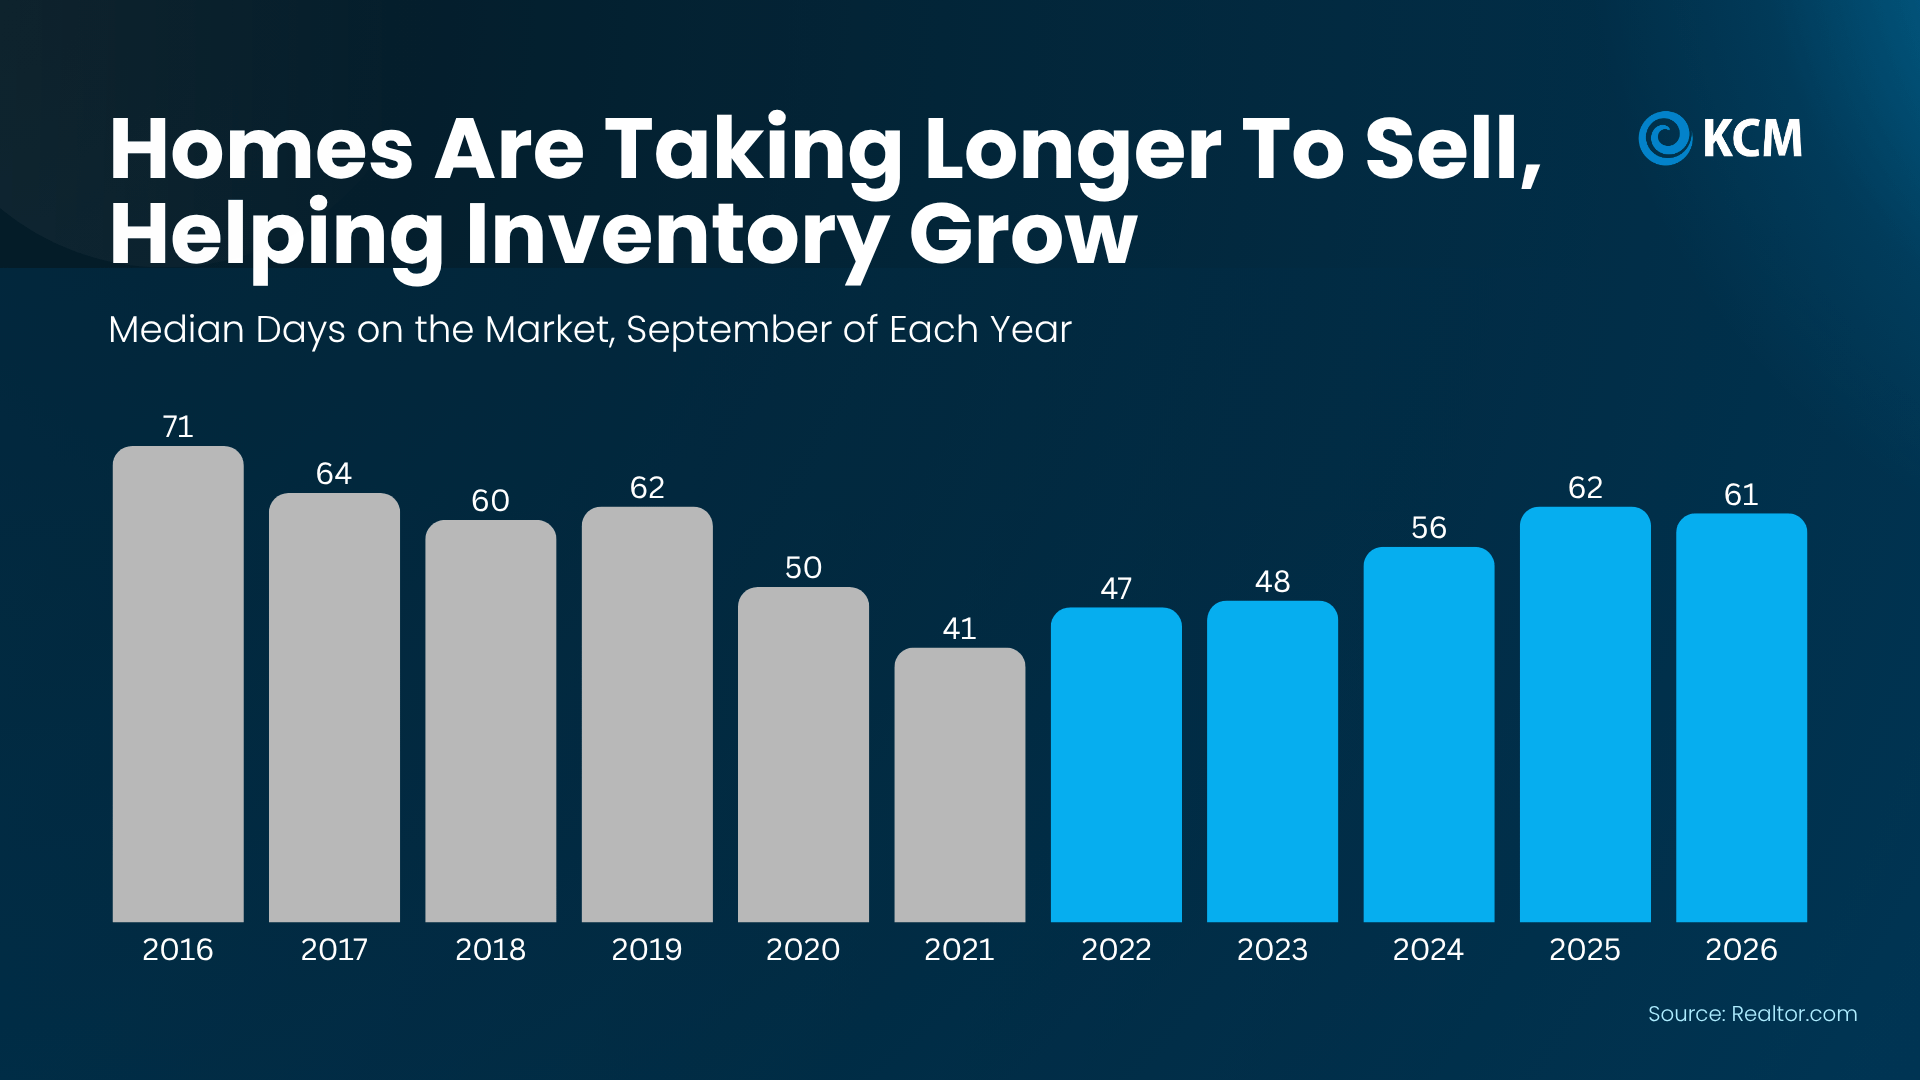
Here’s what that tells us. In 2021, when rates were low, more buyers were active, and homes sold fast. But now that rates are a bit higher, not as many buyers are interested, so it takes a bit longer to close a deal.
How To Make This Market Work for You
So, what does all of this mean for your plans? That depends on which side of the move you’re on:
If you’re buying, more homes for sale means more choices and less pressure to rush. And more room to negotiate too. A house that’s been sitting for a while could have a seller who’s more willing to talk – not just about price, but repairs, closing costs, or even helping buy down your mortgage rate.
That doesn’t mean every seller will play ball. But compared to the frenzy of a few years ago, buyers have more leverage now.
If you’re selling, the right strategy can make all the difference. Buyers have more homes to choose from, so making yours stand out is especially important. That starts with pricing it right from day one, making a great first impression, and working with your agent to highlight what makes your house worth choosing. Buyers are still buying and homes are still selling. The key is making sure yours is positioned to attract the right buyer.
The market hasn’t stopped. It’s just moving at a different pace. And whether you’re buying or selling, your strategy needs to move with it.
Bottom Line
In many places right now, inventory is growing and homes are taking a bit longer to sell. And that’s information that should shape the strategy you use going in.
Whether you’re buying or selling, connect with a local real estate agent to look at how long homes are taking to sell in your neighborhood, so your offer, or your price, fits today’s market.
You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.
With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.
So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.
Why the Fed Is Raising Rates
It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.
So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.
-
MYTH: The Fed controls mortgage rates.
-
REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.
As NerdWallet explains:
“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”
Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.
Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
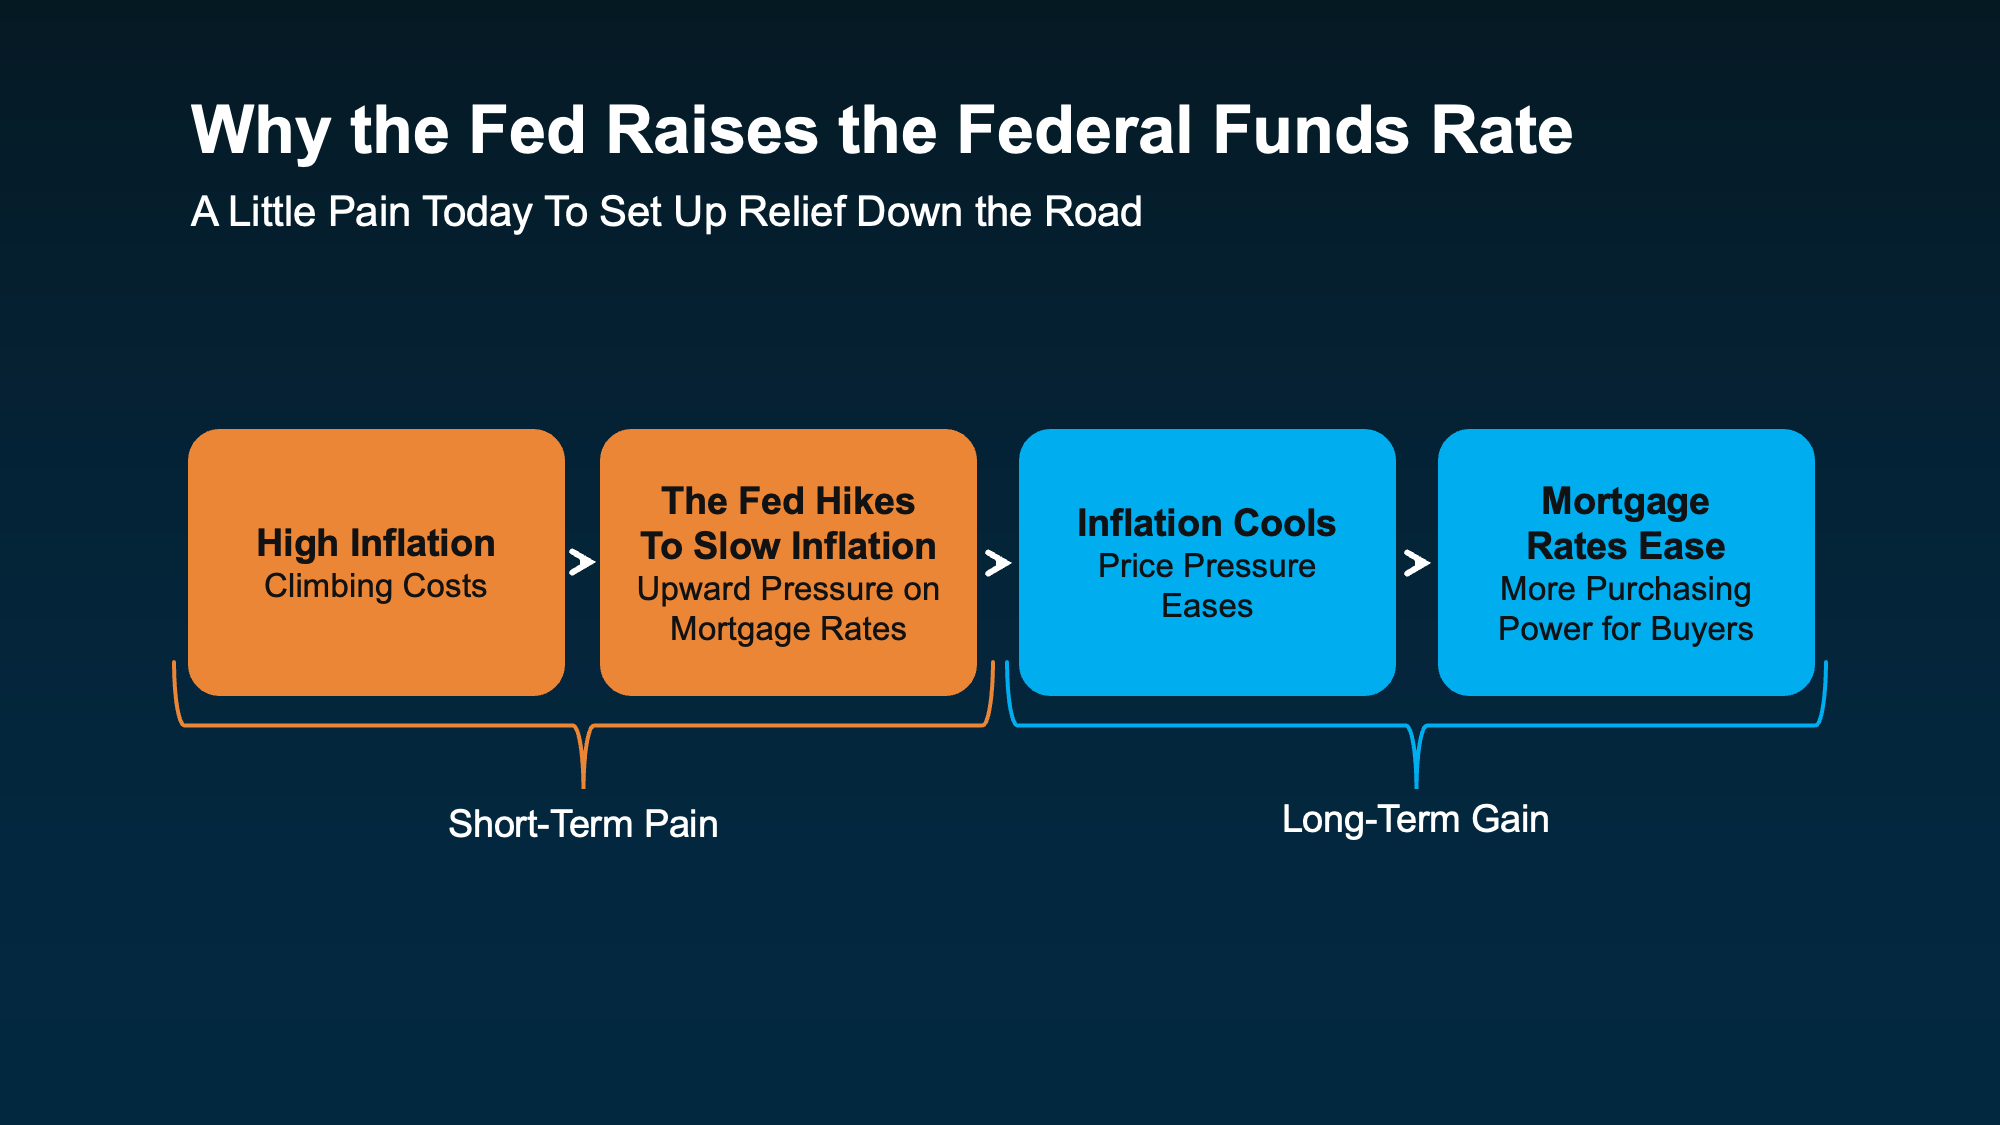
Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.
There’s a Strong Possibility the Fed Will Hike Again This Year
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:
“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“
And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:
-
PCE inflation dropped to 3.4%, down from 3.7% in July.
-
Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.
That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.
How To Make Your Move Work Right Now
While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.
-
If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.
-
If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.
Bottom Line
The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.

The Biggest Credit Hurdle for Renters Who Want To Buy

Homes Are Still Selling – Even in a Slower Market

Why There are More Homes for Sale Right Now (and What It Means for You)


-
 For Sellers4 weeks ago
Selling This Fall? You Want To Get These 4 Things Right.
-
 Affordability4 weeks ago
3 Things You Can Actually Control About Your Mortgage Rate Right Now
-
 Buying Tips2 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 Agent Value3 weeks ago
There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?
-
 For Sellers2 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability3 weeks ago
Why So Many Sellers Are Cutting Their Price Right Now
-
 Affordability3 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Affordability2 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
You must be logged in to post a comment Login