Forecasts
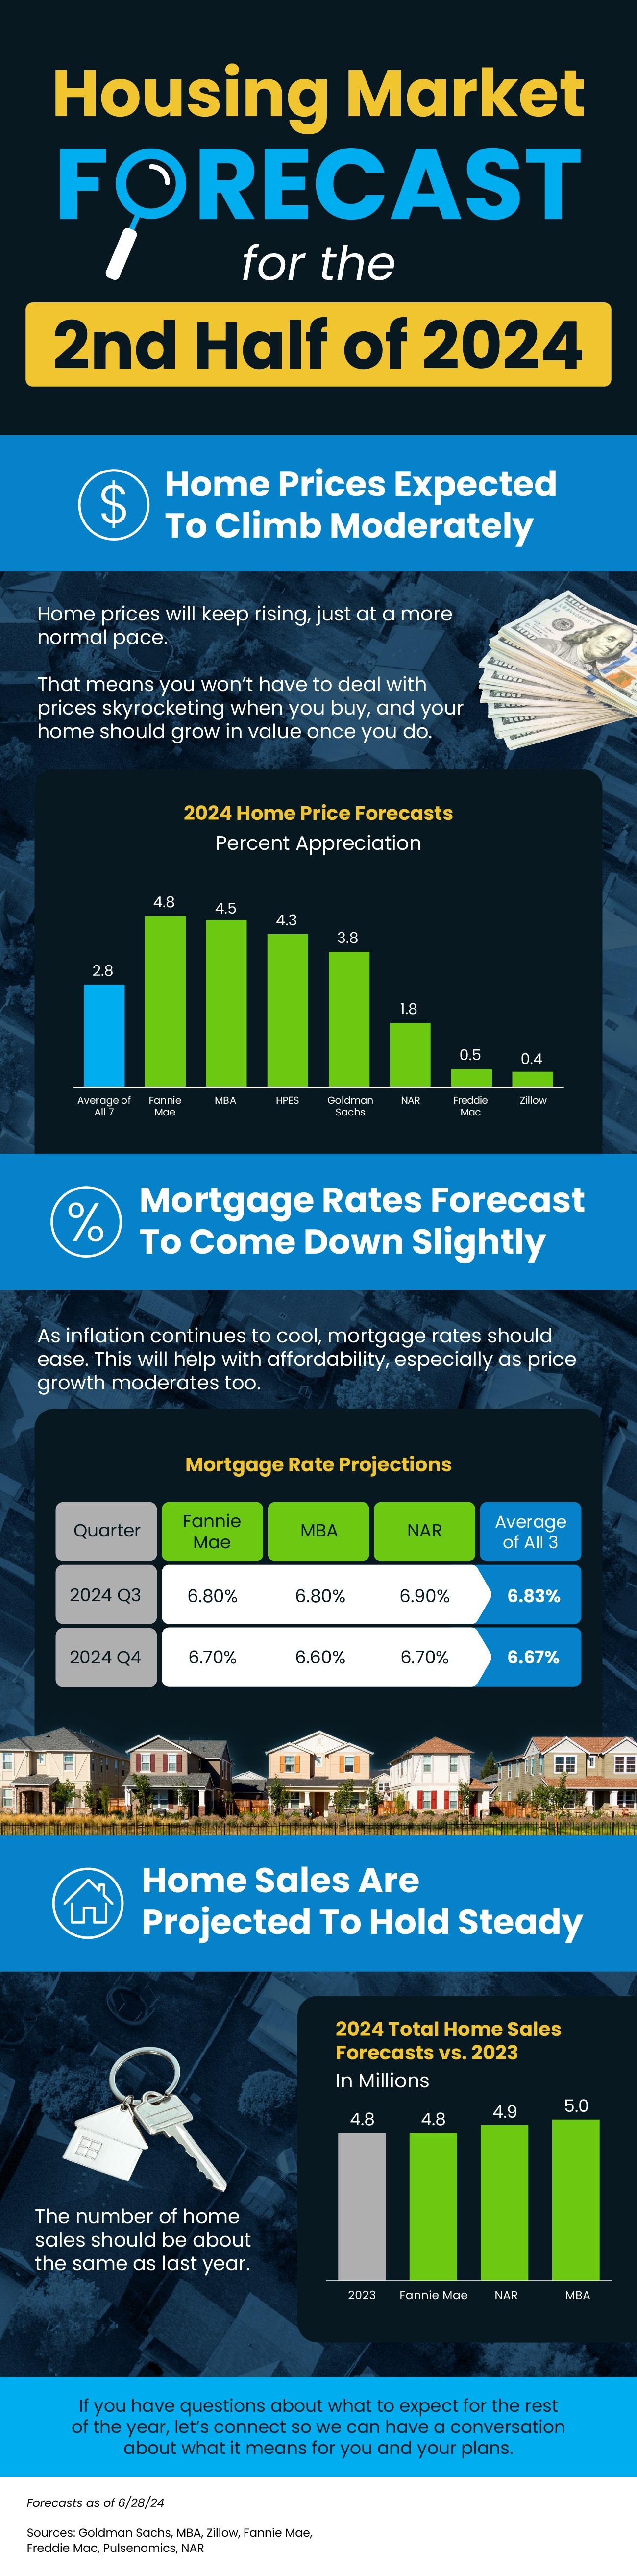
Housing Market Forecast for the 2nd Half of 2024 [INFOGRAPHIC]
Some Highlights
- Wondering what the second half of the year holds for the housing market? Here’s what expert forecasts say.
- Home prices are expected to climb moderately. Mortgage rates are forecast to come down slightly. And, home sales are projected to hold steady.
- If you have questions about what to expect for the rest of the year, connect with a local agent to have a conversation about what it means for you and your plans.
Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.
A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.
So, what do the forecasts actually say?
Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.
What the Newest Numbers Actually Say
The panel’s latest forecast has prices climbing every single year through at least 2030.
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):
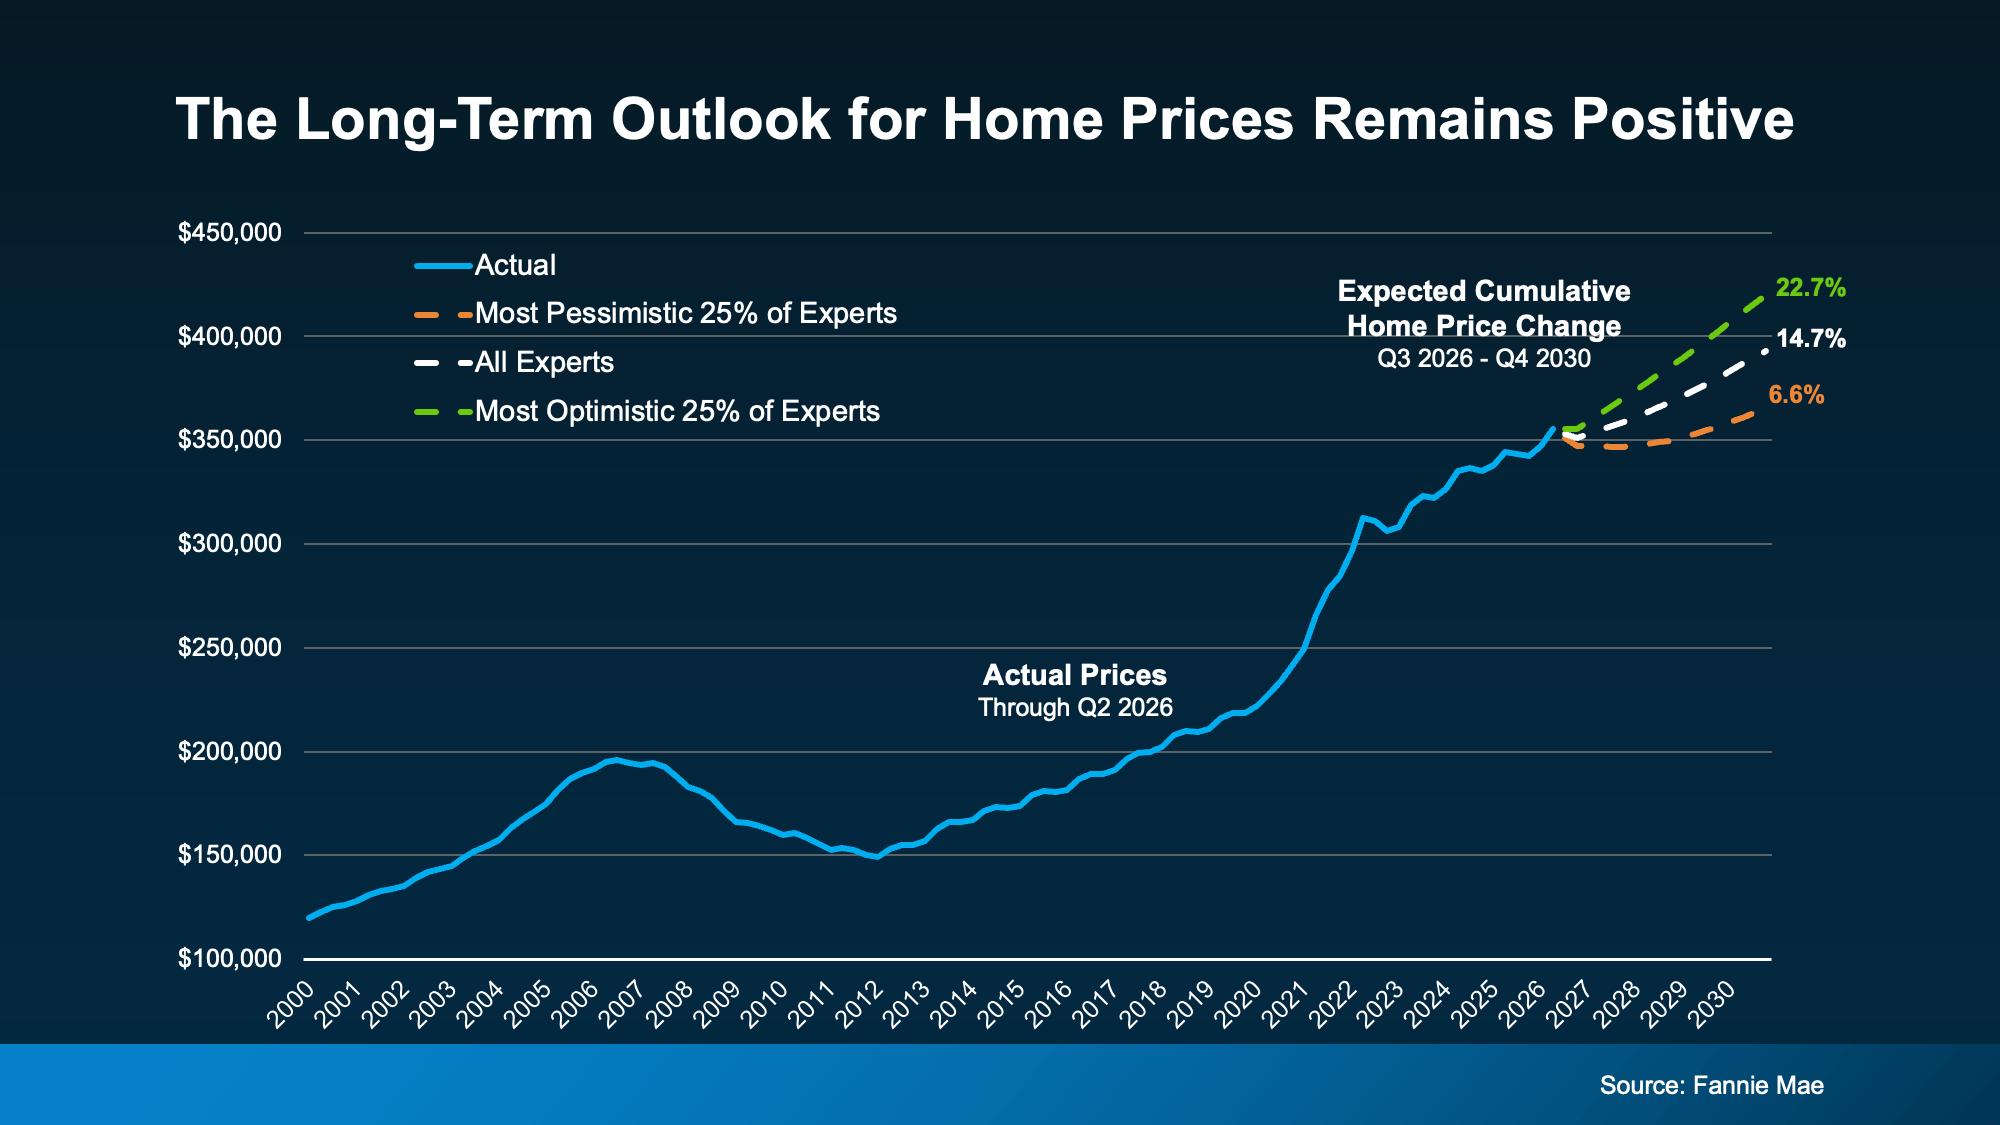
The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.
One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.
How This Quarter Compares to the Past
Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.
A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):
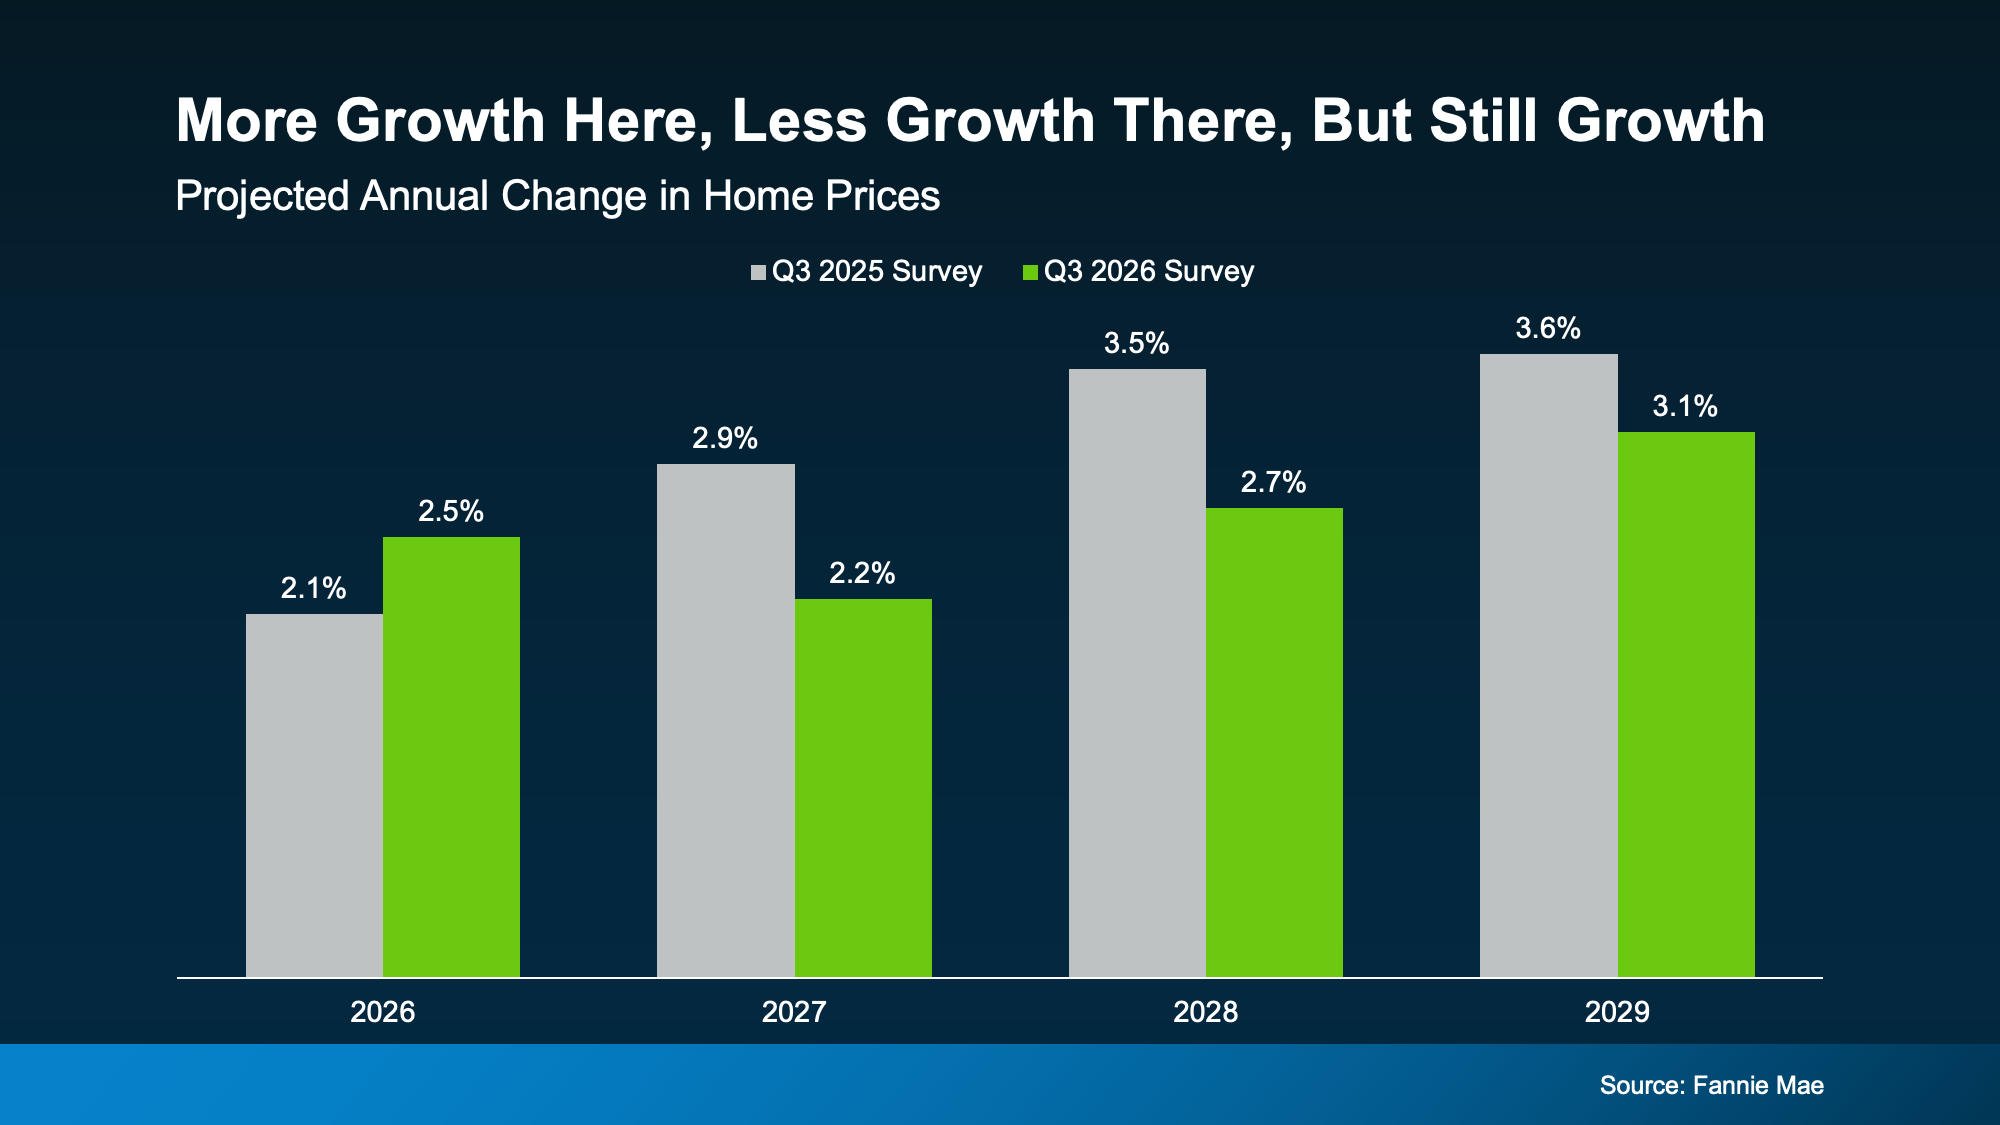
Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.
But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.
A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.
A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.
What It Means for Your Next Move
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.
Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):
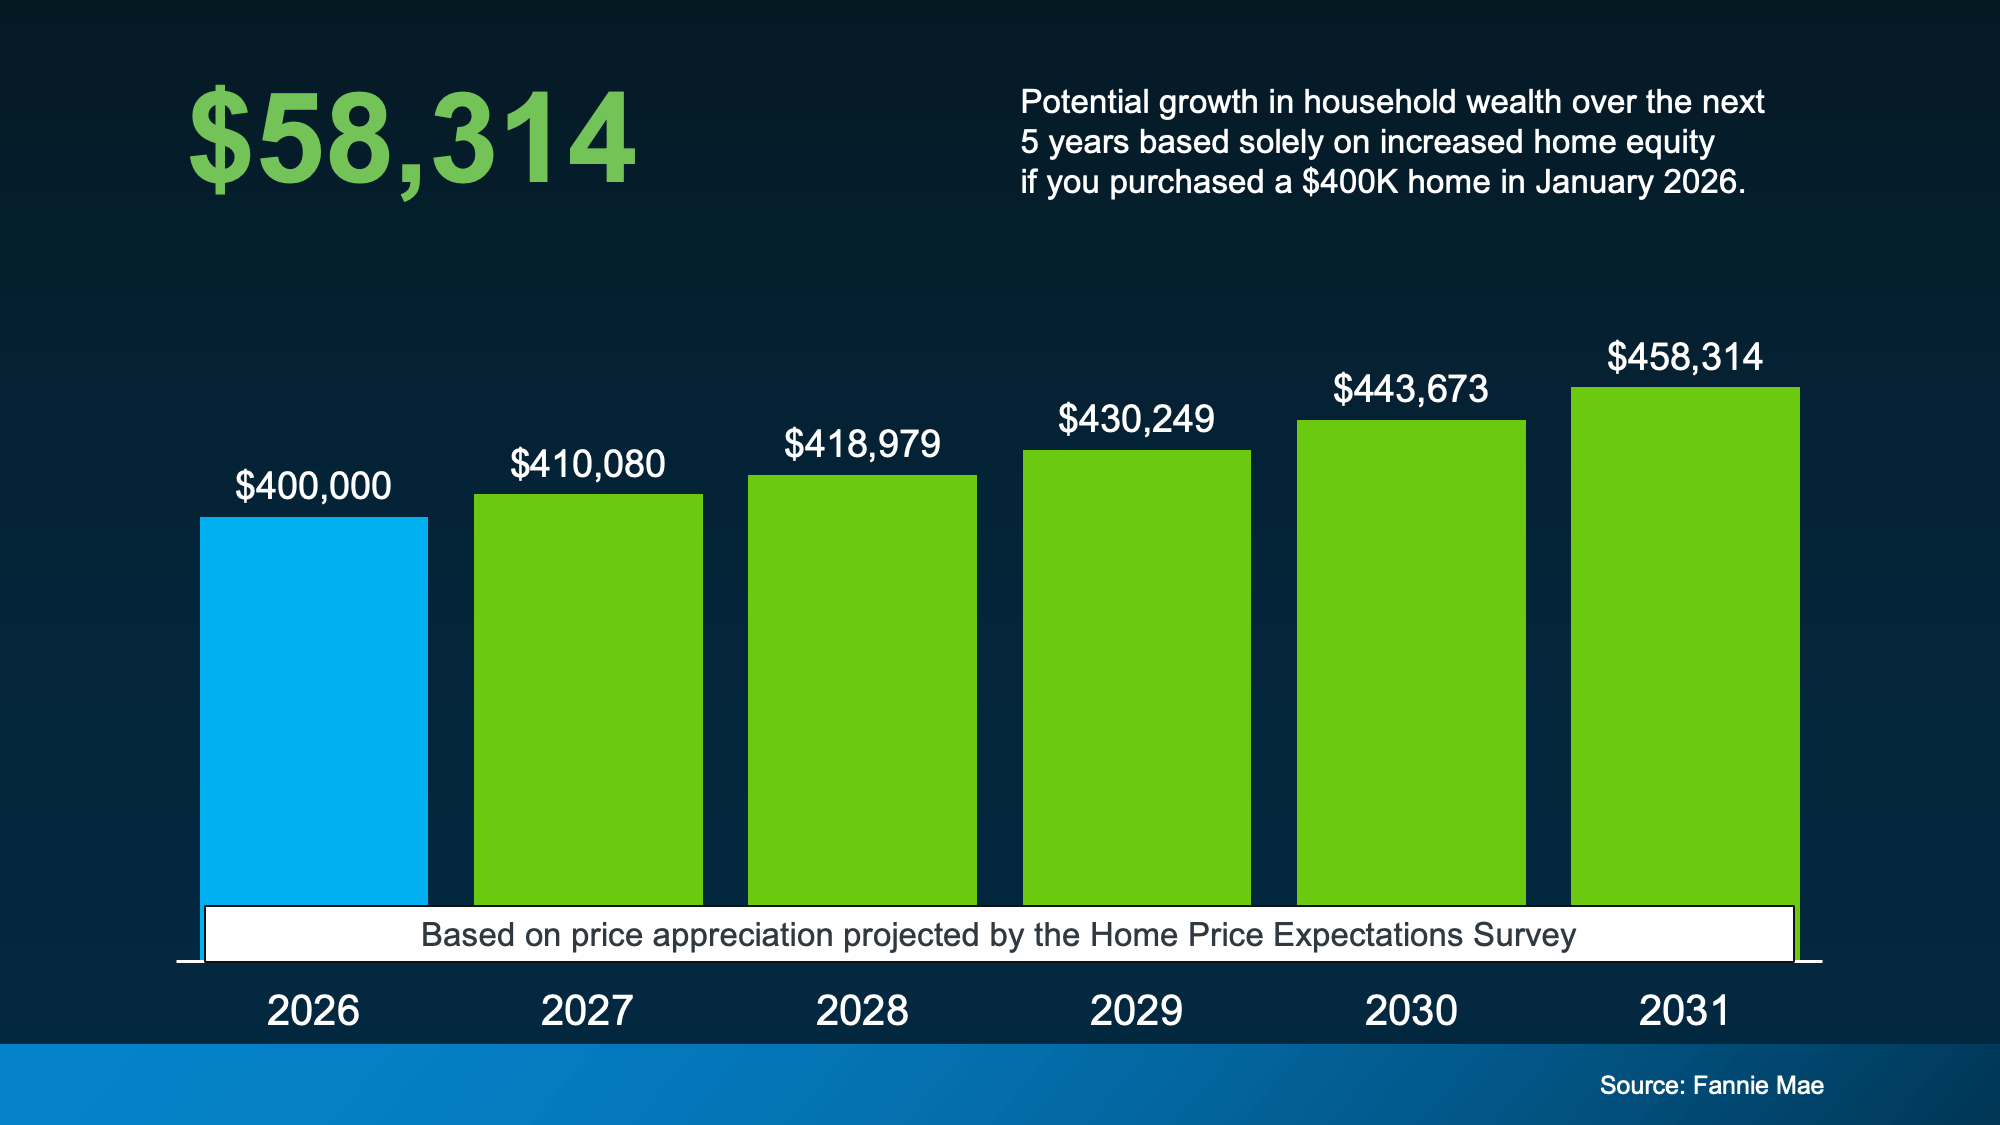
That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.
Bottom Line
Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

Imagine waiting a year to buy a home, only to find mortgage rates haven’t changed much. That may sound frustrating.But it’s a real possibility.
A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today’s forecasts, that may not happen. And you should know that before you decide what to do.
Let’s look at why experts don’t expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.
1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way
If you’re waiting for rates to fall, you’re not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.
The challenge is, that’s not what the experts who study mortgage rates every day are expecting.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):
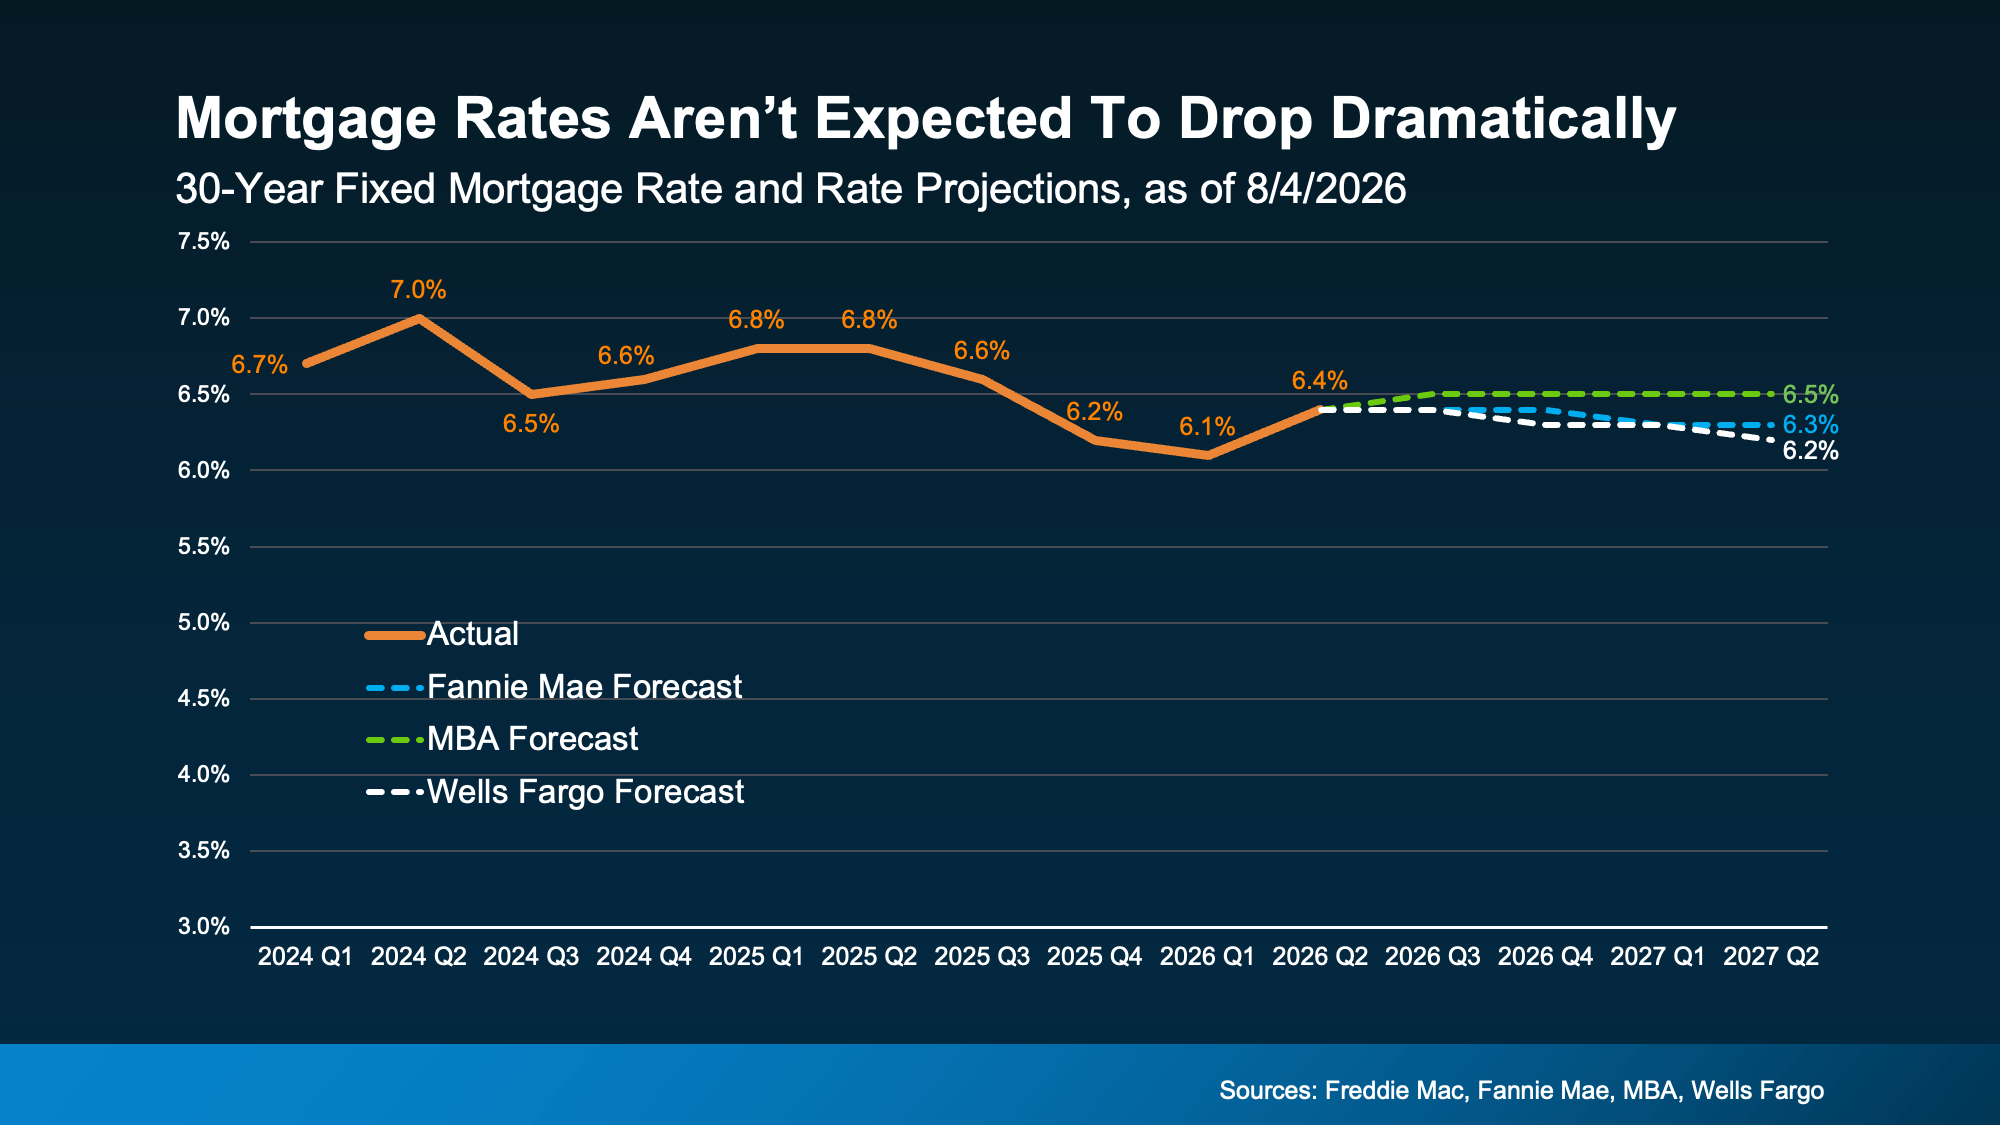
Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren’t pointing toward the kind of dramatic rate drop many buyers are waiting for.
Could rates move a little? Of course. But if you’re holding out for a bigger drop, today’s forecasts suggest you may be waiting a lot longer than you expect.
2. Inflation Is Still Elevated – And That’s Working Against Lower Rates
One reason experts aren’t expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn’t in place today. That helps explain why experts aren’t forecasting the kind of meaningful decline so many buyers are hoping for.
3. Today’s Rates Aren’t High, They’re “Normal”
And this may be the biggest mindset shift of all. The reality is, while today’s rates may feel high compared to a few years ago, they’re not high. They’re normal.
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):
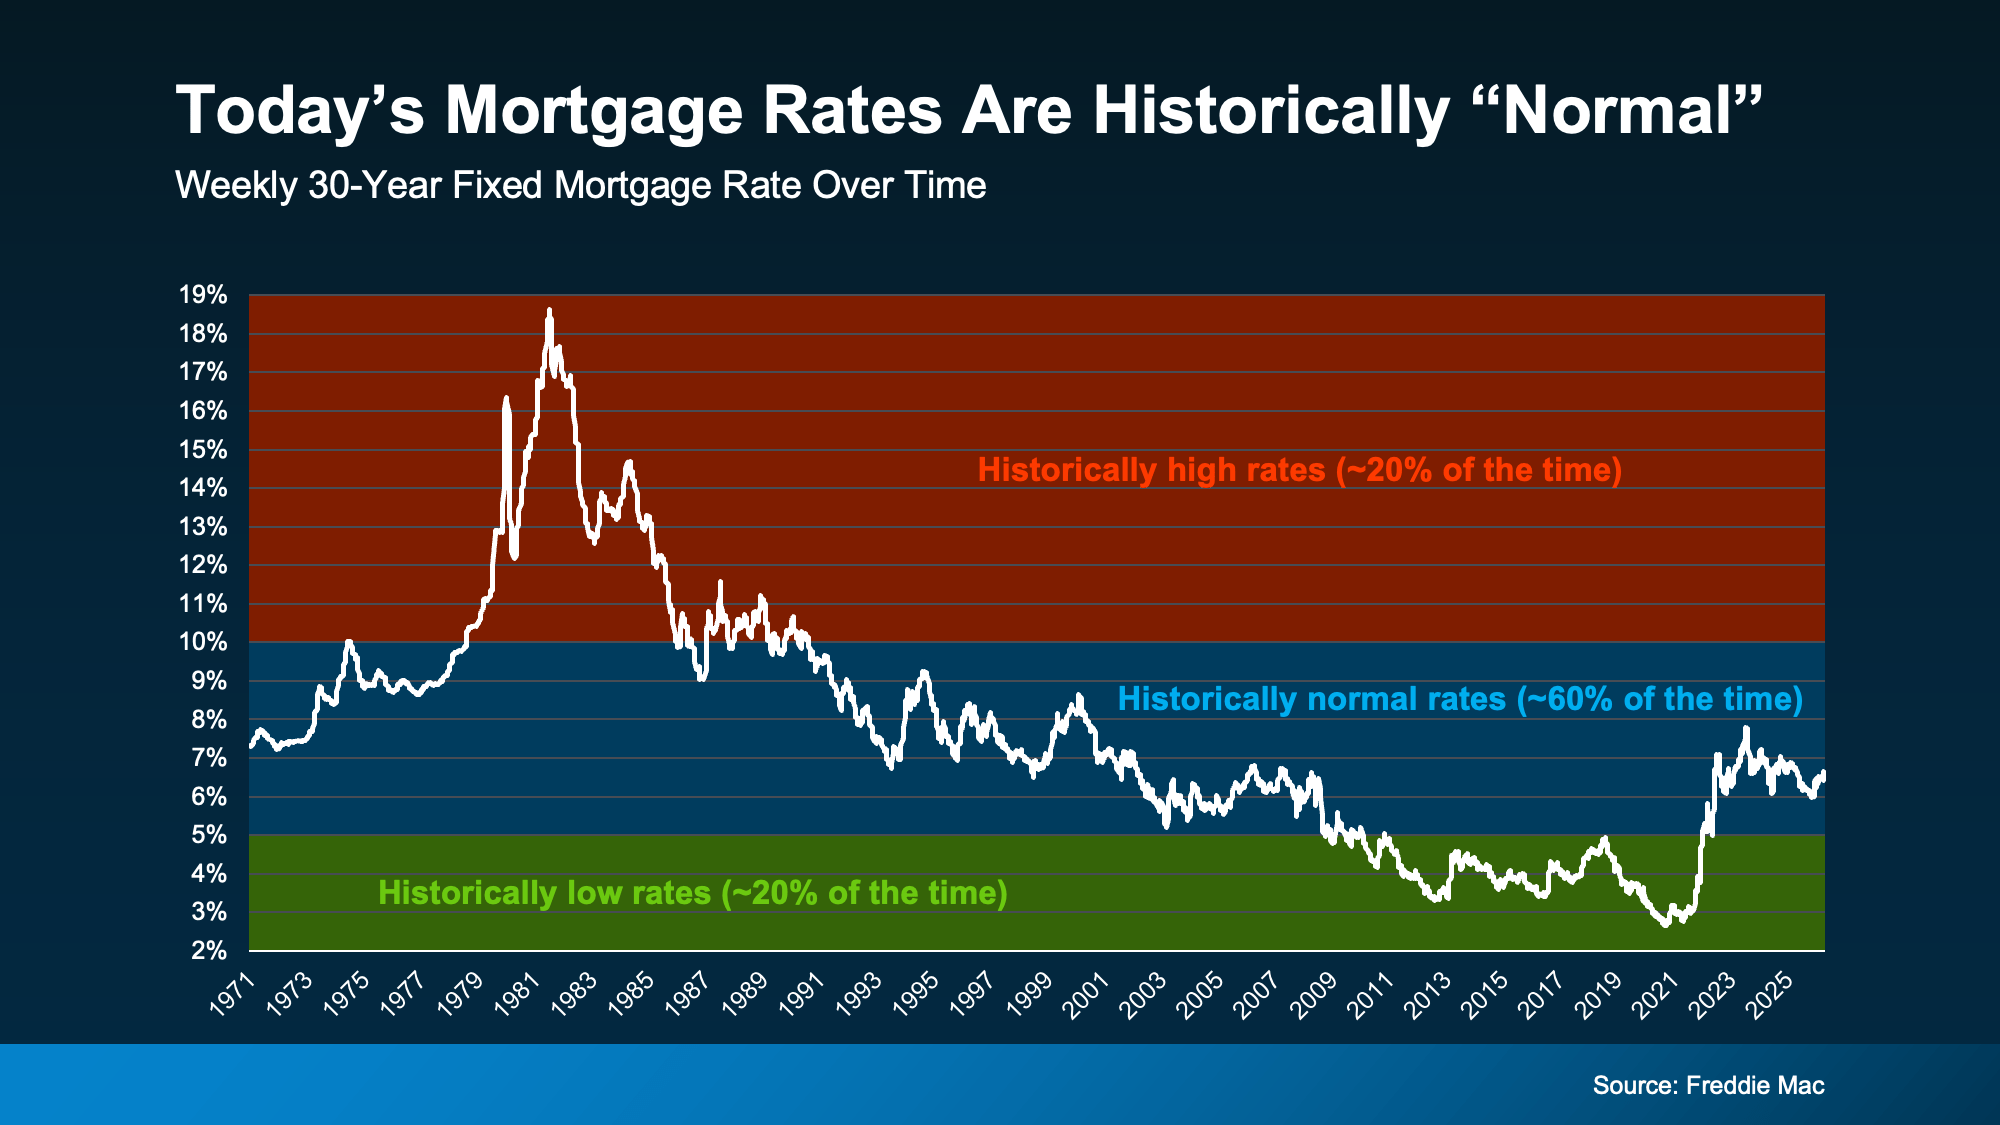
Now, this doesn’t suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.
So… What Should You Do Instead?
None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.
-
Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.
-
Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It’s not the right choice for everyone, but it’s worth asking a lender if it fits your plans.
-
Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.
-
Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.
The important thing is you shouldn’t assume waiting is your only option.
Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.
Bottom Line
If you’ve been putting your home search on hold because you’re convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.
Connect with an agent or lender so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.
If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.
That’s why so many people are asking the same question: Will the second half of the year be any better for the housing market?
While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here’s what to watch.
Mortgage Rates Could Be Near a Turning Point
One of the biggest reasons mortgage rates haven’t come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?
Oil prices have already started coming back down.
That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.
Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:
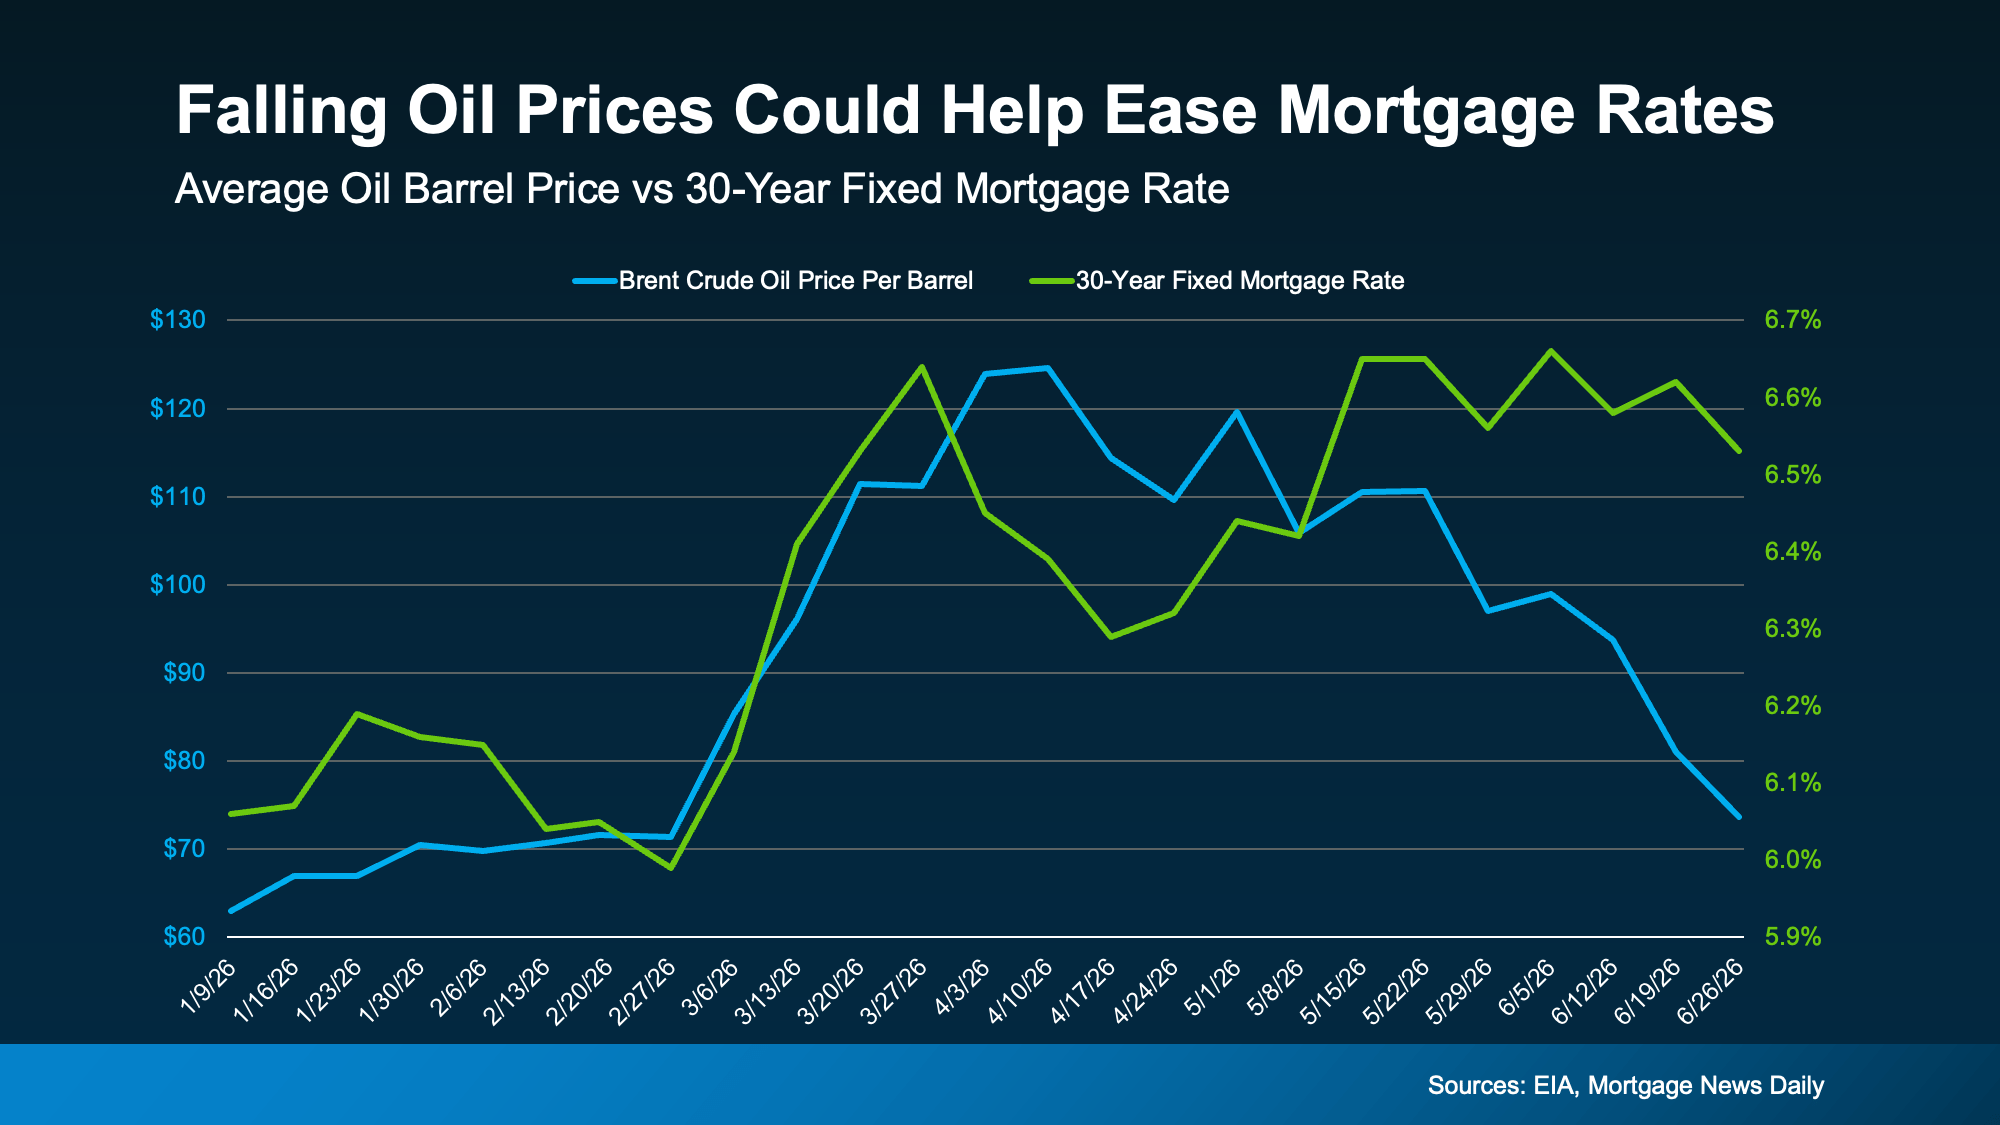
It’s too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.
And that’s good news for anyone thinking about moving. The first half of the year tested everyone’s patience. The second half may finally reward it.
Home Prices Could Pick Back Up
A lot of people want home prices to fall too. But that’s not what most forecasts show.
While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):
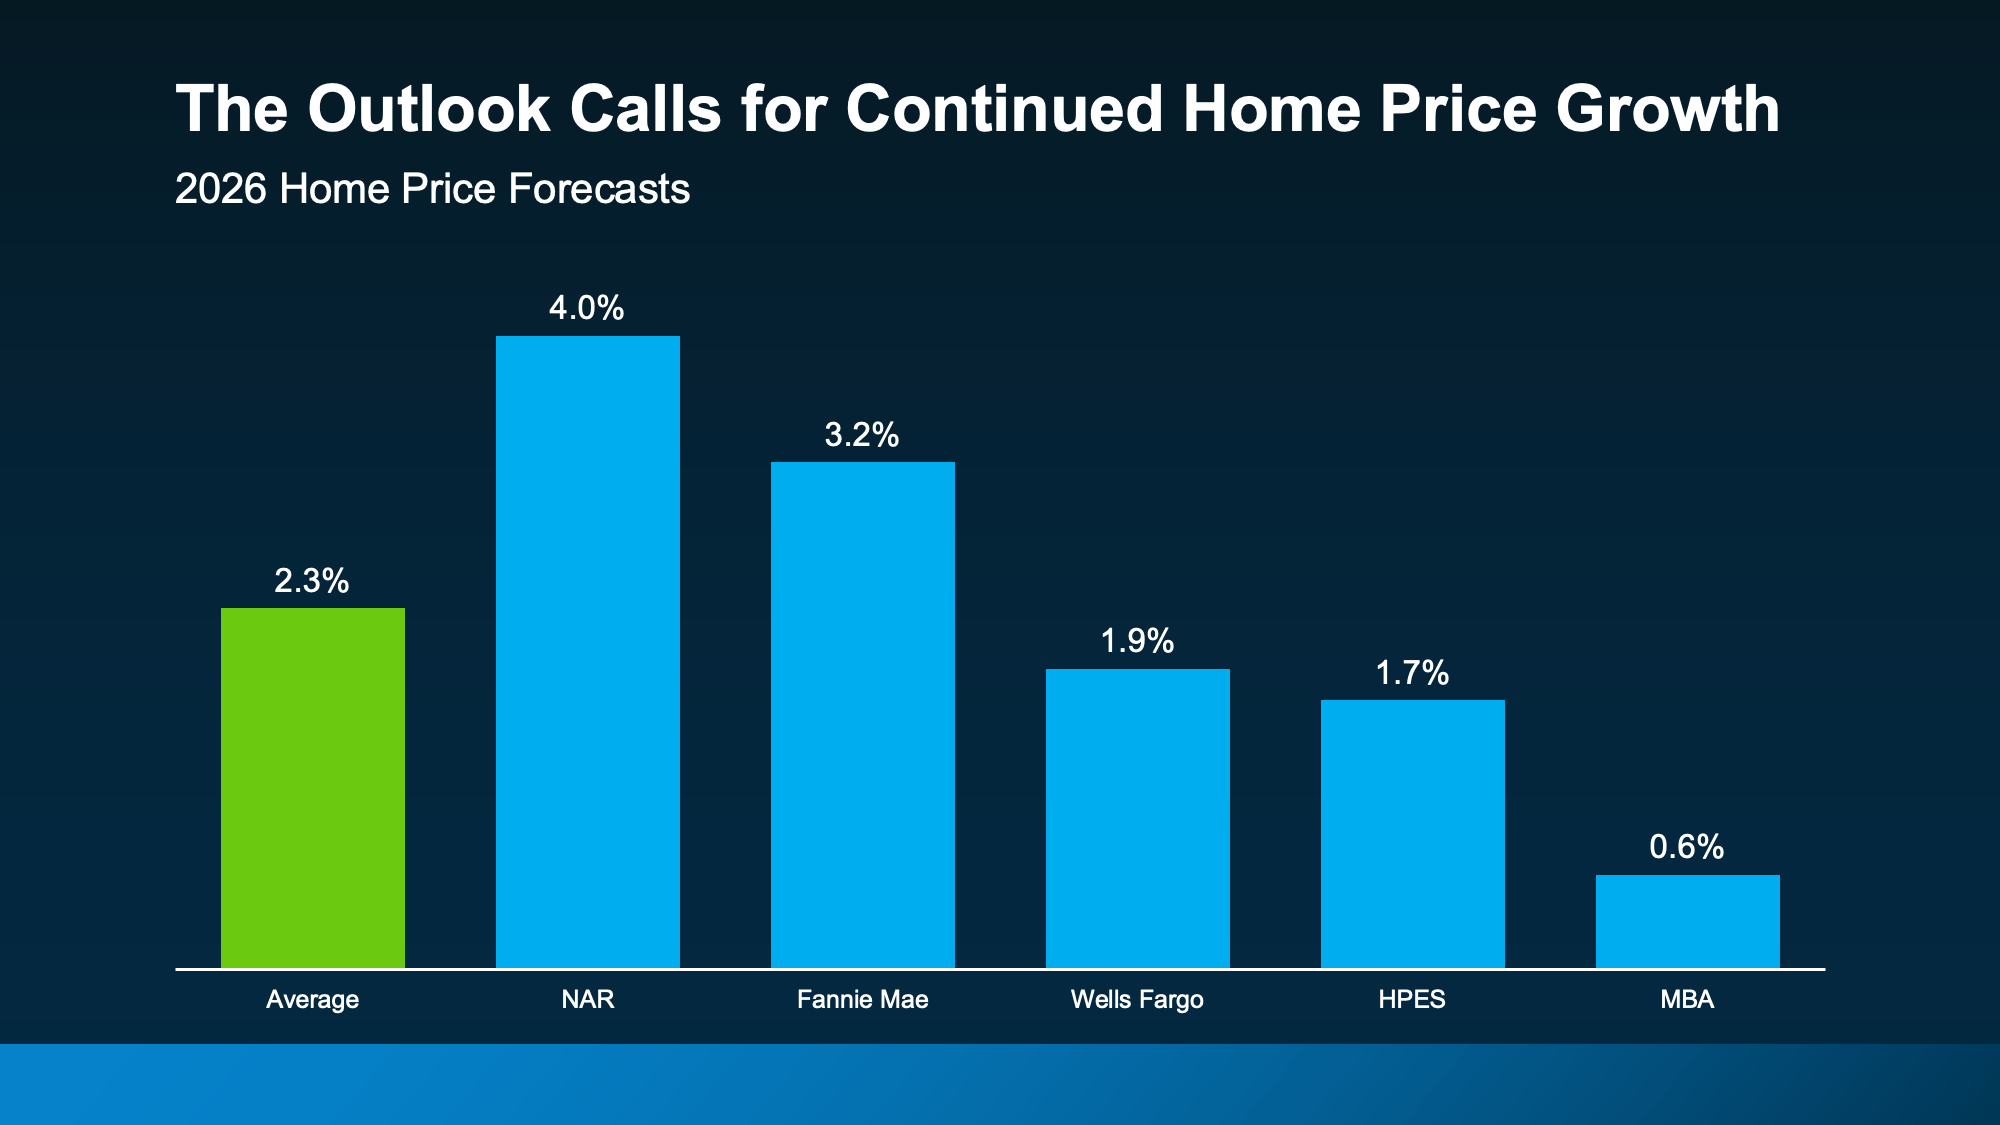
What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.
Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.
Here’s why that’s possible.
The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.
That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.
More Homes Are Expected To Sell
If you’ve been wondering why the housing market has felt quieter lately, you’re not imagining it. Home sales have been slower than many experts expected. But that doesn’t mean people have stopped wanting to move.
A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon.
If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:
“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.”
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):
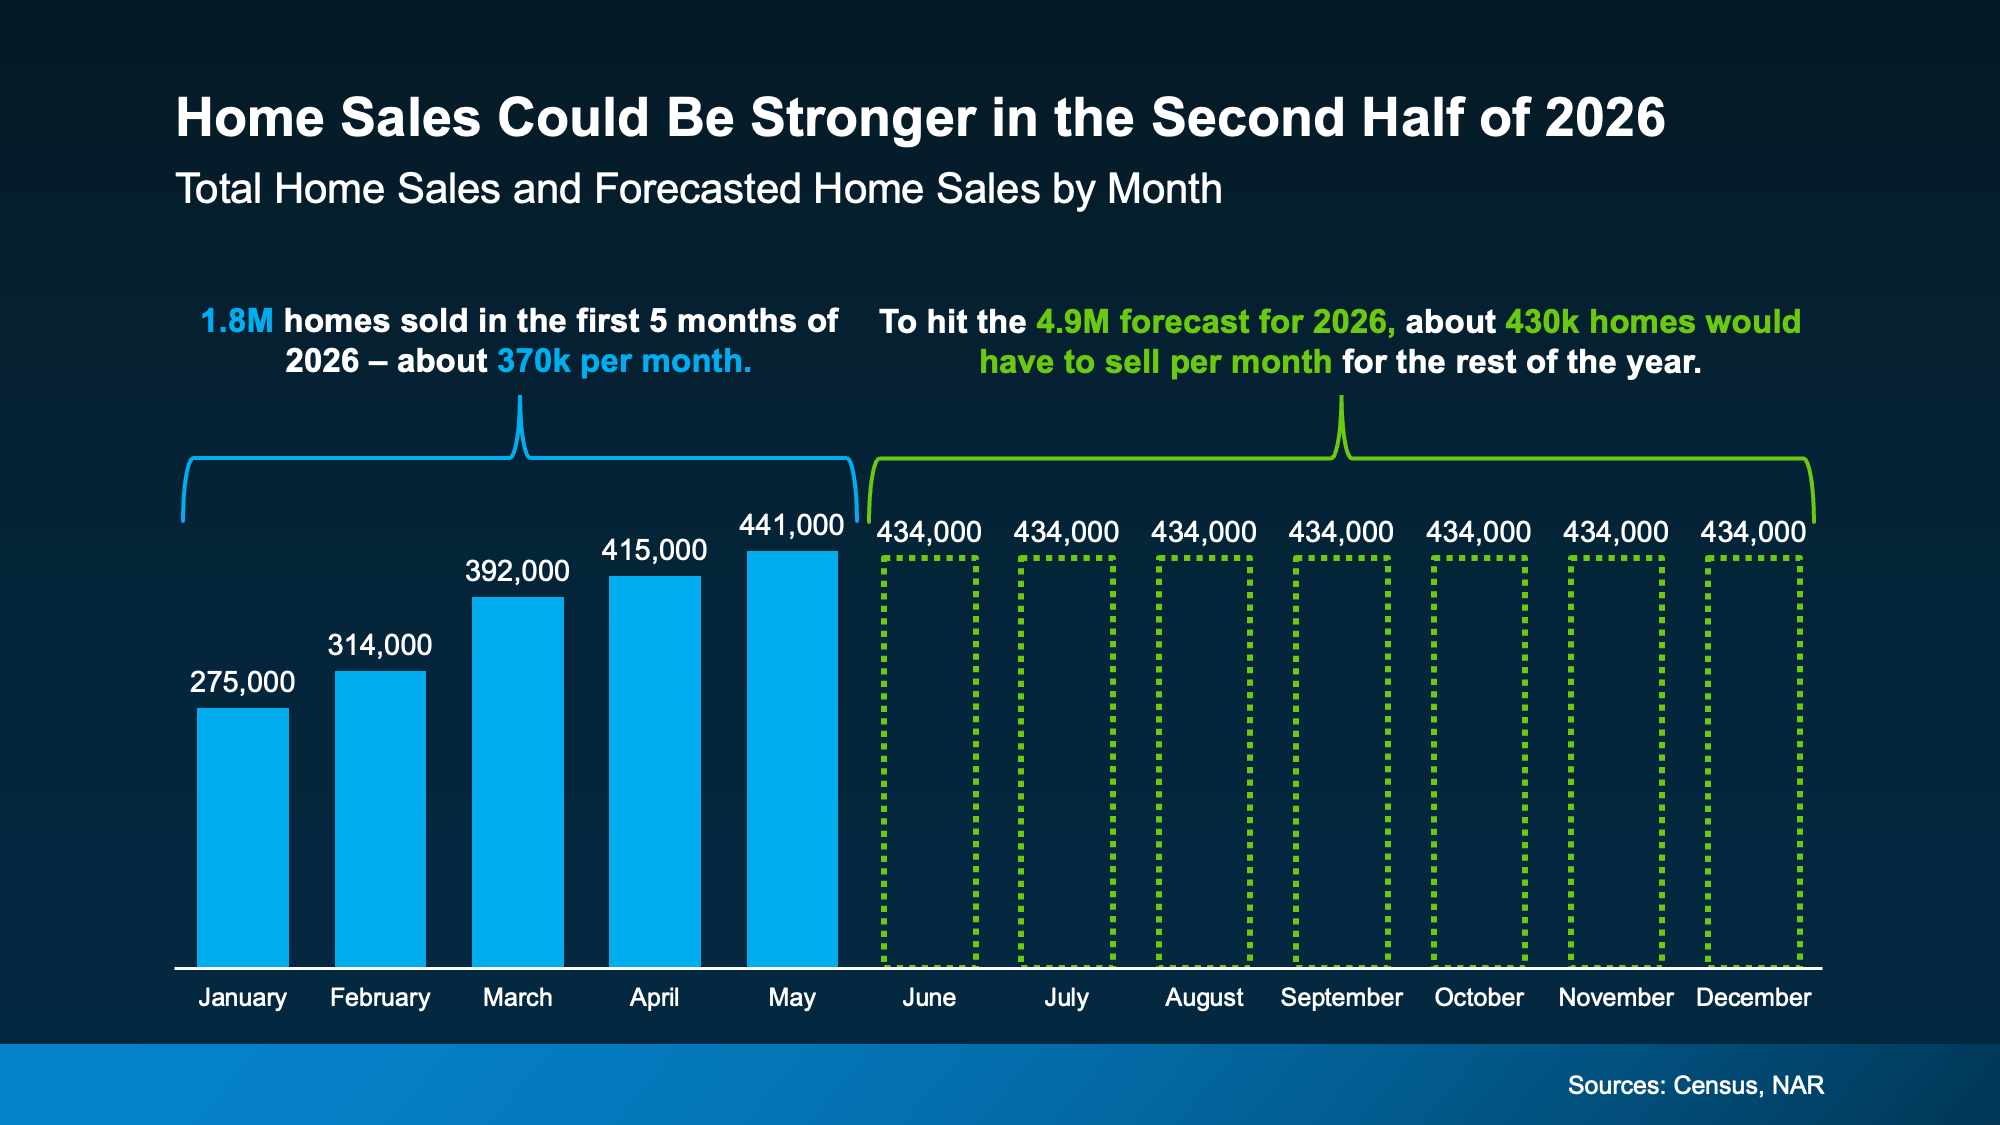
In fact, each month for the rest of 2026 would have to come close to matching the best month we’ve had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.
More people will finally make their move happen – and you’ve got the chance to be one of them.
Bottom Line
The second half of the year probably won’t be perfect. But it could be better.
Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you’ve been waiting for signs of progress, this is it.
If you want to understand what these forecasts mean for your plans and what’s happening in your local market, connect with an agent.

What Higher Mortgage Rates Mean for Home Sellers

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.


-
 Affordability4 weeks ago
Remote Work Could Be Your Affordability Answer
-
 For Buyers3 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
-
 Agent Value4 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
-
 For Sellers2 weeks ago
Selling This Fall? You Want To Get These 4 Things Right.
-
 Agent Value3 weeks ago
Selling This Fall? You Haven’t Missed Your Window
-
 Affordability2 weeks ago
3 Things You Can Actually Control About Your Mortgage Rate Right Now
-
 Affordability3 weeks ago
The Best Time To Buy a Home in 2026 Is Almost Here
-
 Agent Value2 weeks ago
There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?
You must be logged in to post a comment Login