Agent Value
The Secret To Selling Your House in Today’s Market
A few years ago, homes were flying off the shelves and getting multiple offers well over their asking price. It felt like you could name your price and still have buyers lined up at the door.
But today’s housing market is different. Buyers are getting more selective now that inventory has grown. Homes are sitting a little longer. And more sellers are having to cut their prices.
So, how do you still come out on top? It all starts with one thing, pricing your house right from the start. Today, that matters more than ever – and it can make or break your sale.
There’s a Real Price Disconnect Between Buyers and Sellers
A recent survey from Realtor.com shows 81% of home sellers believe they’ll get their asking price or more. But the actual sales data shows there’s a growing gap between what sellers expect and what buyers are actually willing to pay.
In fact, an annual report from the National Association of Realtors (NAR) shows 44% of recently sold homes went for less than the asking price. And 1 in 3 sellers had to cut their price at least once before the home sold. It’s a sign that expectations may be a little out of step with today’s reality.
Check out the graph below. It uses data from Redfin to show that asking prices (blue line) are higher than actual sales prices (green line) by a wider and wider margin:
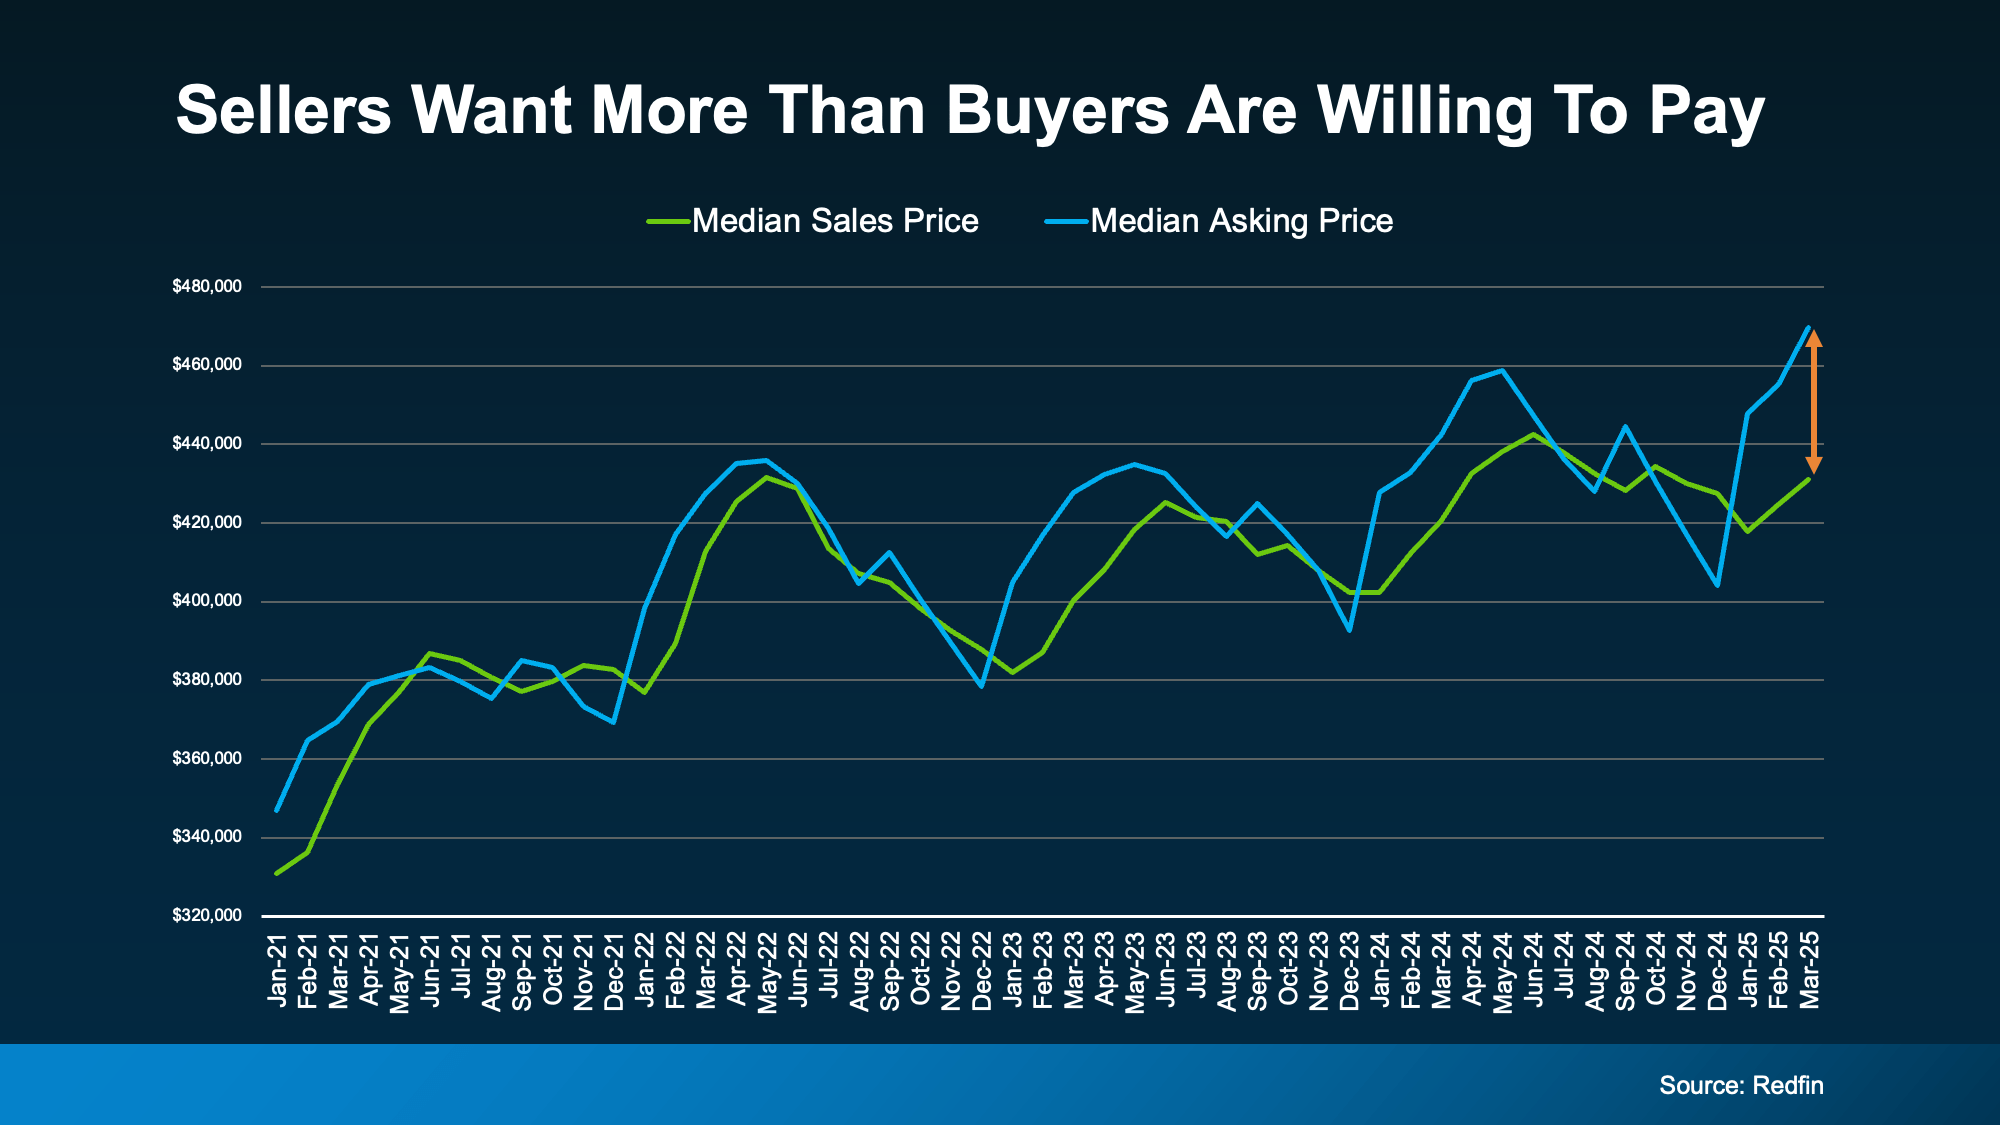 This tells you something important: not all buyers are willing to pay what many sellers are asking. That doesn’t mean you can’t sell for a great price – but it does mean you need to start with a price that reflects what people are willing to pay in today’s market.
What Happens When You Overprice Your House?
Pricing your house high initially may seem like a smart move, so you have more room to negotiate. But the reality is, an overpriced home can sit on the market and turn buyers away.
Buyers are smart. And when they see a house that’s been sitting for a while, they start to wonder what’s wrong with it. That can lead to fewer showings, less interest, and eventually, a price cut to re-ignite attention. As Realtor.com explains:
“By getting the right price early on, you can increase the odds buyers will be interested in the home. In turn, this decreases the chances the home will sit on the market for a lengthier timeline, also reducing the odds you’ll need to lower the listing price.”
The longer a house sits, the harder it can be to sell.
You Still Have a Great Opportunity – If You Price Your House Right
To avoid making this mistake, it’s important to lean on an agent who knows what’s happening locally when you set your asking price.
Your agent will look at recent local sales, buyer trends, and inventory levels to find that pricing sweet spot for your neighborhood – because it’s going to be different based on where you live.
And here’s something else to keep in mind, home prices have climbed more than 57% over the past five years. So, even if you price a bit below the number you had your sights set on, you’ll likely still be in a great position profit-wise.
With a local real estate agent’s help, you’ll attract more attention, avoid seeing your house sit on the market too long, and maximize your chances of getting a strong offer.
In today’s market, the right price works. As Mike Simonsen, Founder of Altos Research, explains:
“. . . the best properties, well priced are selling quickly in most of the country.”
Bottom Line
The market has changed, but your opportunity to sell hasn’t. You just need the right pricing plan. Talk to a local real estate agent to go over what’s happening with prices in your area and determine what price would help your house sell quickly and for top dollar.
Selling your house is a big step, and you want it to go smoothly. And with houses taking a little longer to sell these days, renting it out might start to sound like a nice backup plan.
But the reality is, while renting can work well for some people, it’s also a big commitment. So before you decide, it helps to see the whole picture first.
Why Some Sellers Are Deciding To Rent Instead
Lately, some sellers are choosing to hang on to their houses and rent them out instead. According to Parcl, around 9% of homes for rent right now were previously up for sale.
Here’s why.
Some homeowners put their houses on the market expecting a faster process than they got or a certain price buyers didn’t respond to. And when things didn’t go exactly as planned, they decided to rent instead. As Kara Ng, Senior Economist at Zillow, explains:
“Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price.”
But here’s the important distinction. Just because some sellers are choosing to rent doesn’t mean selling isn’t working. In many cases, the difference comes down to how well a house is priced, prepared, and marketed for today’s buyers.
Parcl data shows where these “accidental landlords” – owners who planned to sell but decided to rent instead – are most common (see graph below):
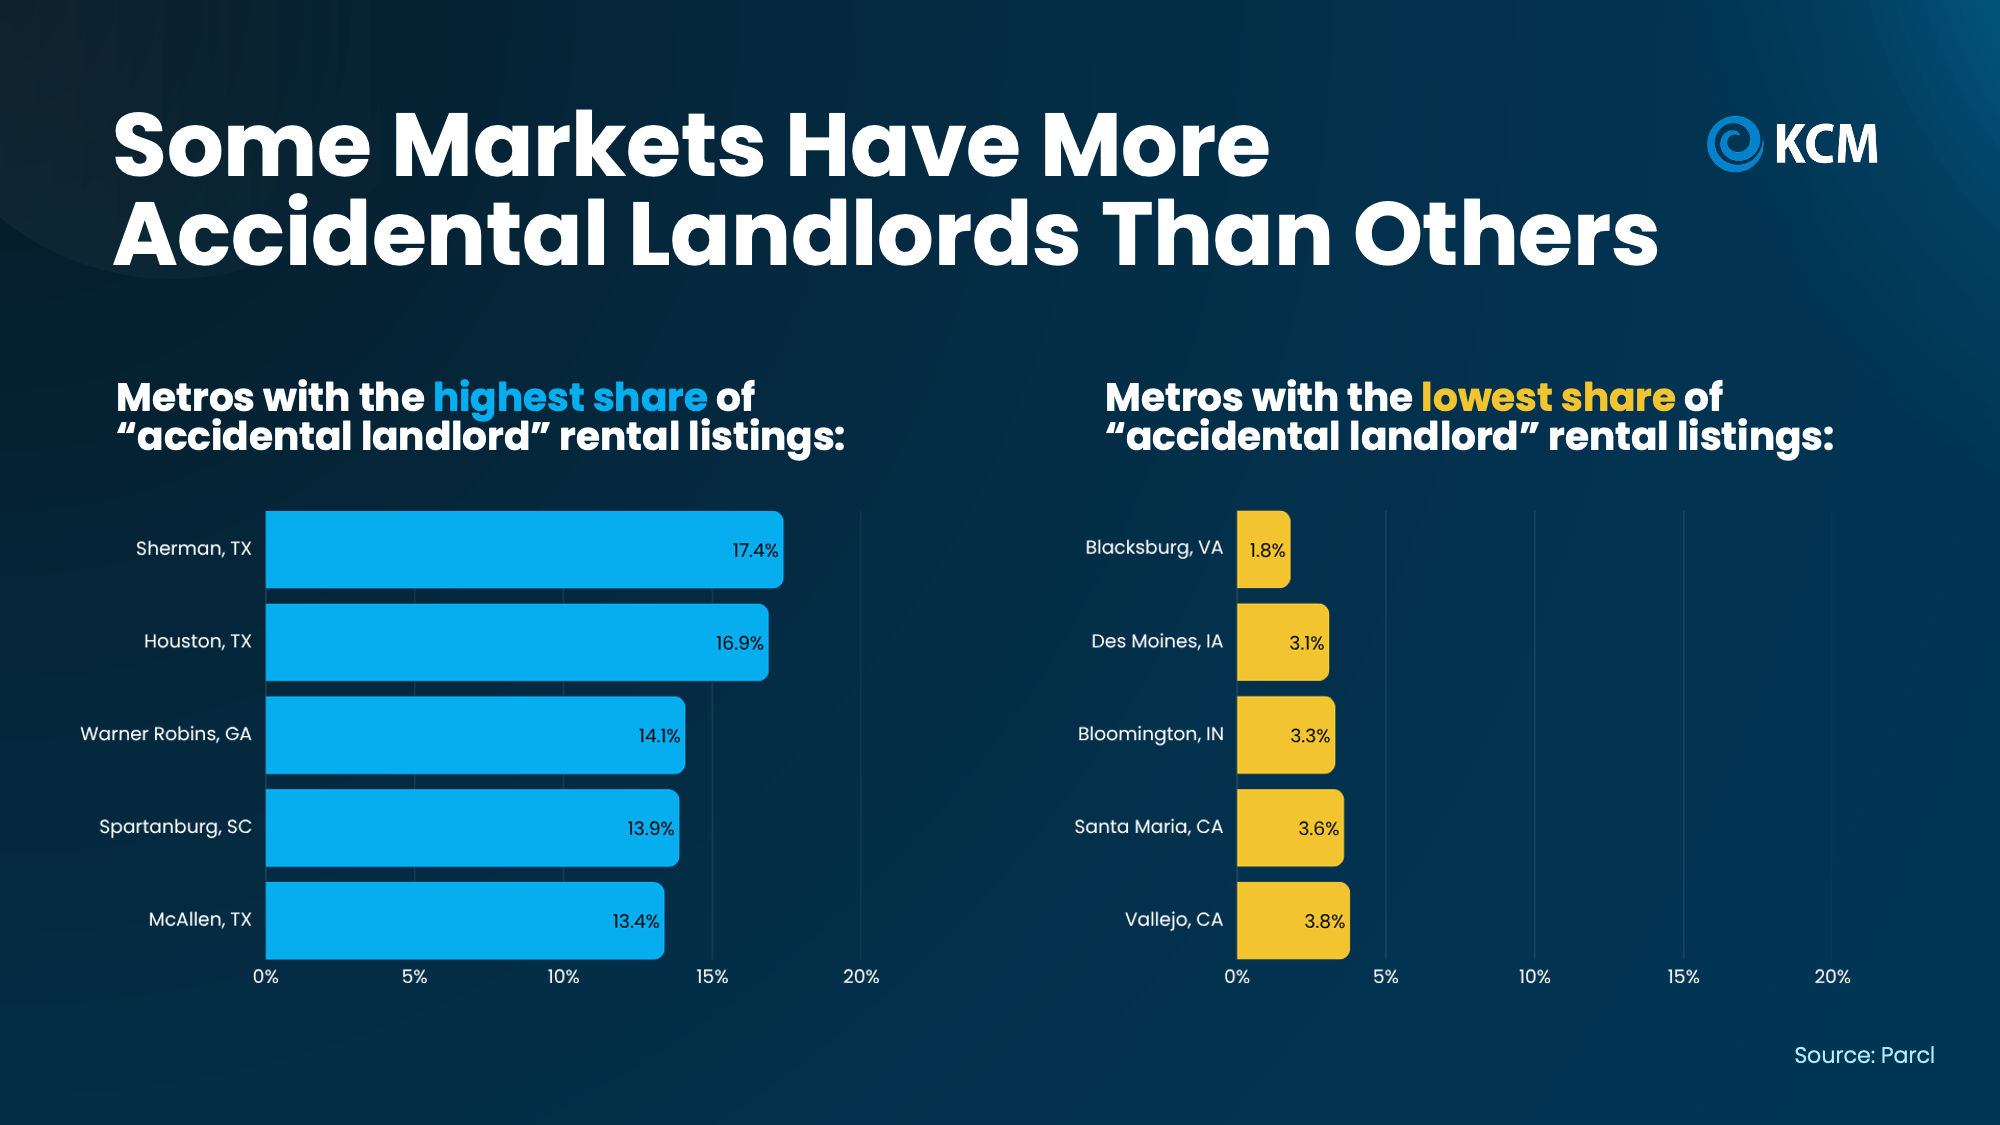
They make up around 17% of homes for rent in places like Sherman and Houston, TX, but less than 4% in markets like Des Moines, IA and Bloomington, IN.
That’s a pretty big difference. And it shows why you have to know what’s happening in your neighborhood. Your market, your asking price, and your strategy all play a role in how your sale goes.
A local agent can show you how houses like yours are selling, what strategies work best, and help you weigh your options – not to push you to sell, but so you at least have the full picture based on today’s market. And part of making an informed decision is understanding what renting your house would actually take.
What Being a Landlord Actually Looks Like
While renting might sound like easy passive income on paper, in practice, it’s a hands-on job with rules to follow. As Invest West Management puts it:
“Even if you never intended to become a landlord, the law still sees you as one — and you must meet all legal obligations that come with that role. This often includes registering the tenancy, providing tenants with certain disclosures, and ensuring the property meets safety standards.”
You’d also be the one chasing missed rent payments, fixing damage between tenants, and covering unexpected repairs. Not to mention fielding weekend calls about leaky dishwashers or broken AC units.
There are expenses beyond regular maintenance and repairs, too. According to Bankrate, these are a few of the biggest:
-
Insurance premiums (landlord insurance typically costs about 25% more than a standard homeowners policy)
-
Management fees (if you hire a property manager, they usually charge around 10% of the rent)
-
Gaps between tenants, when you pay the mortgage without rental income
How To Give Your House a Strong Start
If you want to be a landlord and you’re prepared for the responsibility, renting may be a great fit. But if you’d really rather sell, don’t let today’s market convince you that you can’t.
A great agent can make it happen. The key is having an open conversation up front with your agent about pricing and how to market your house. Nailing those details from day 1 helps your house make a great first impression, so renting doesn’t have to be your fallback.
Bottom Line
Renting can be a good fit for the right person with the right house, but it isn’t the only option. A smart sales strategy can help your house stand out to buyers from day one.
So, if you’re on the fence, a local real estate agent can help you compare what selling and renting would each look like for you.
Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.
One says home prices are falling. The next says they’re still climbing.
So, which one’s right? It comes down to where you live.
What’s Really Going on with Asking Prices
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):
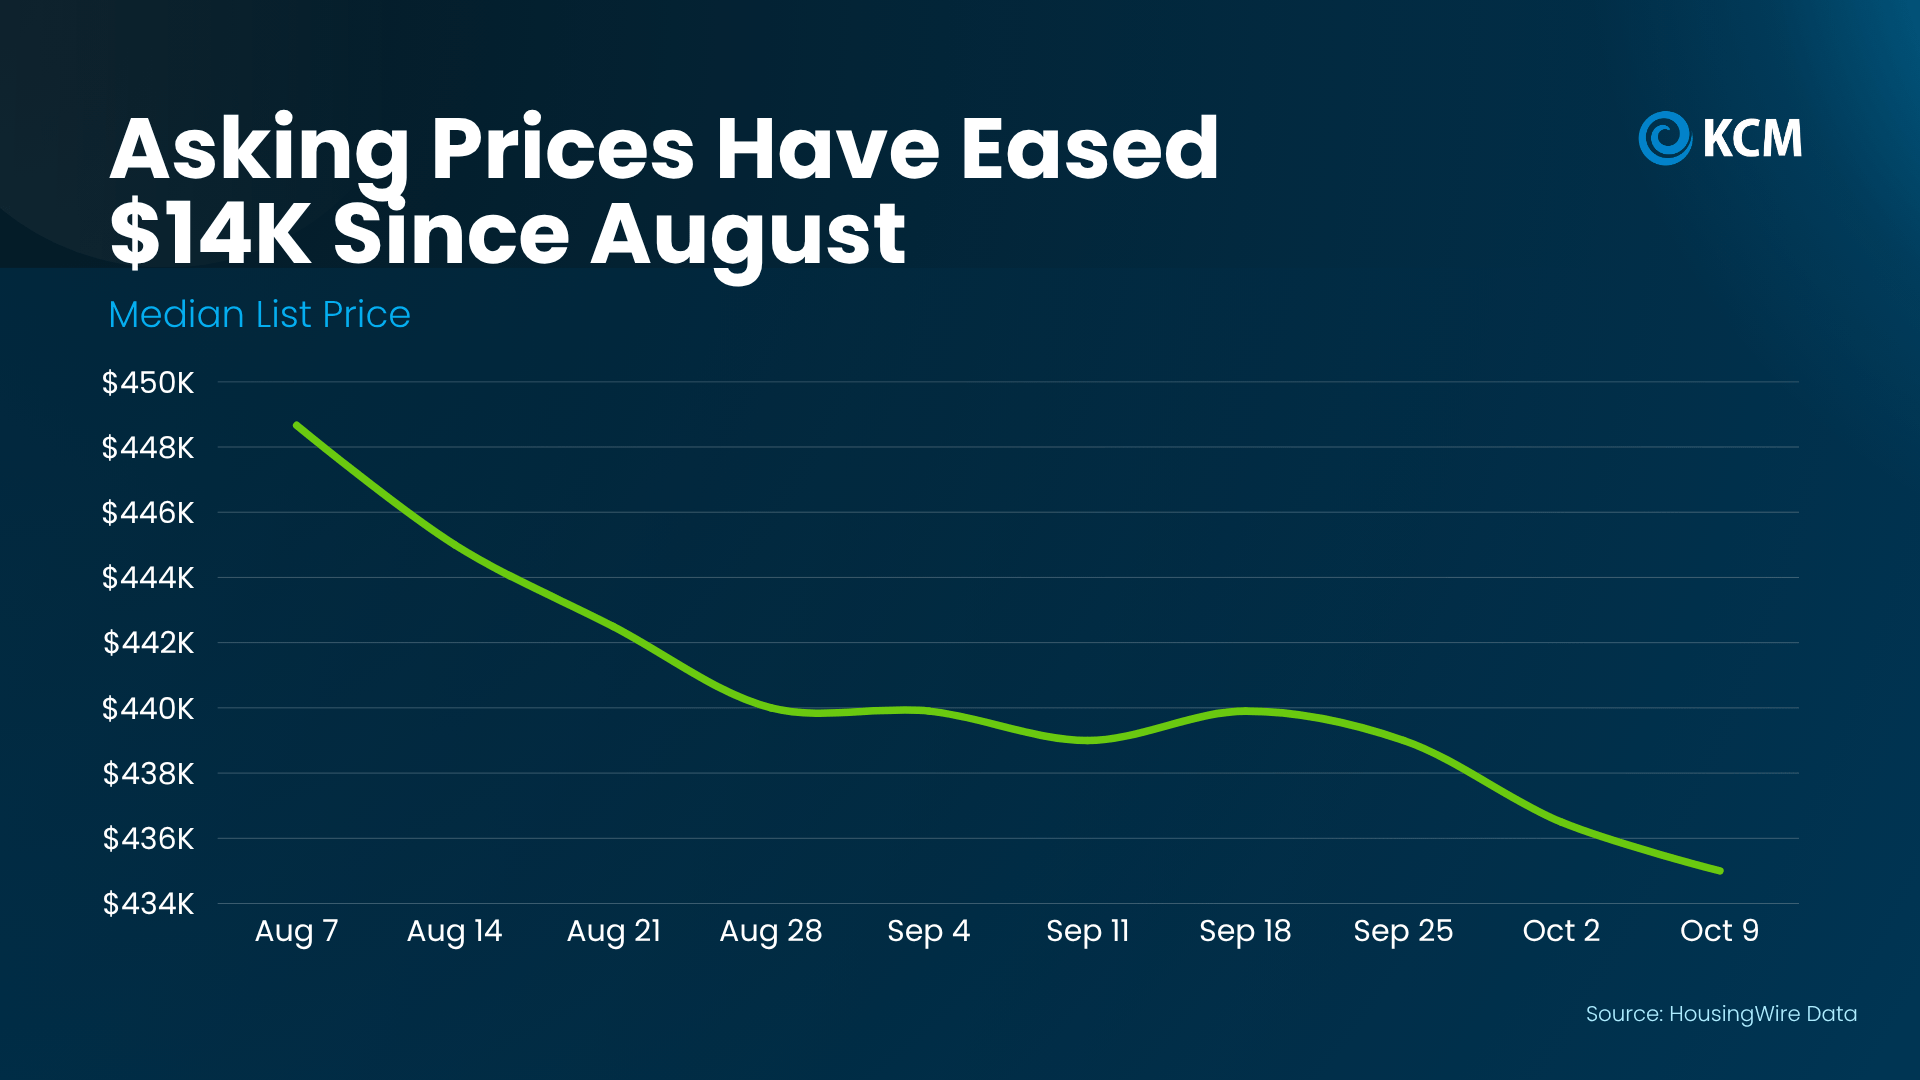
That’s a dip of about 3%, and a lot of it is normal for this time of year.
Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.
Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.
Where You Live Changes Everything
Realtor.com explains:
“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):
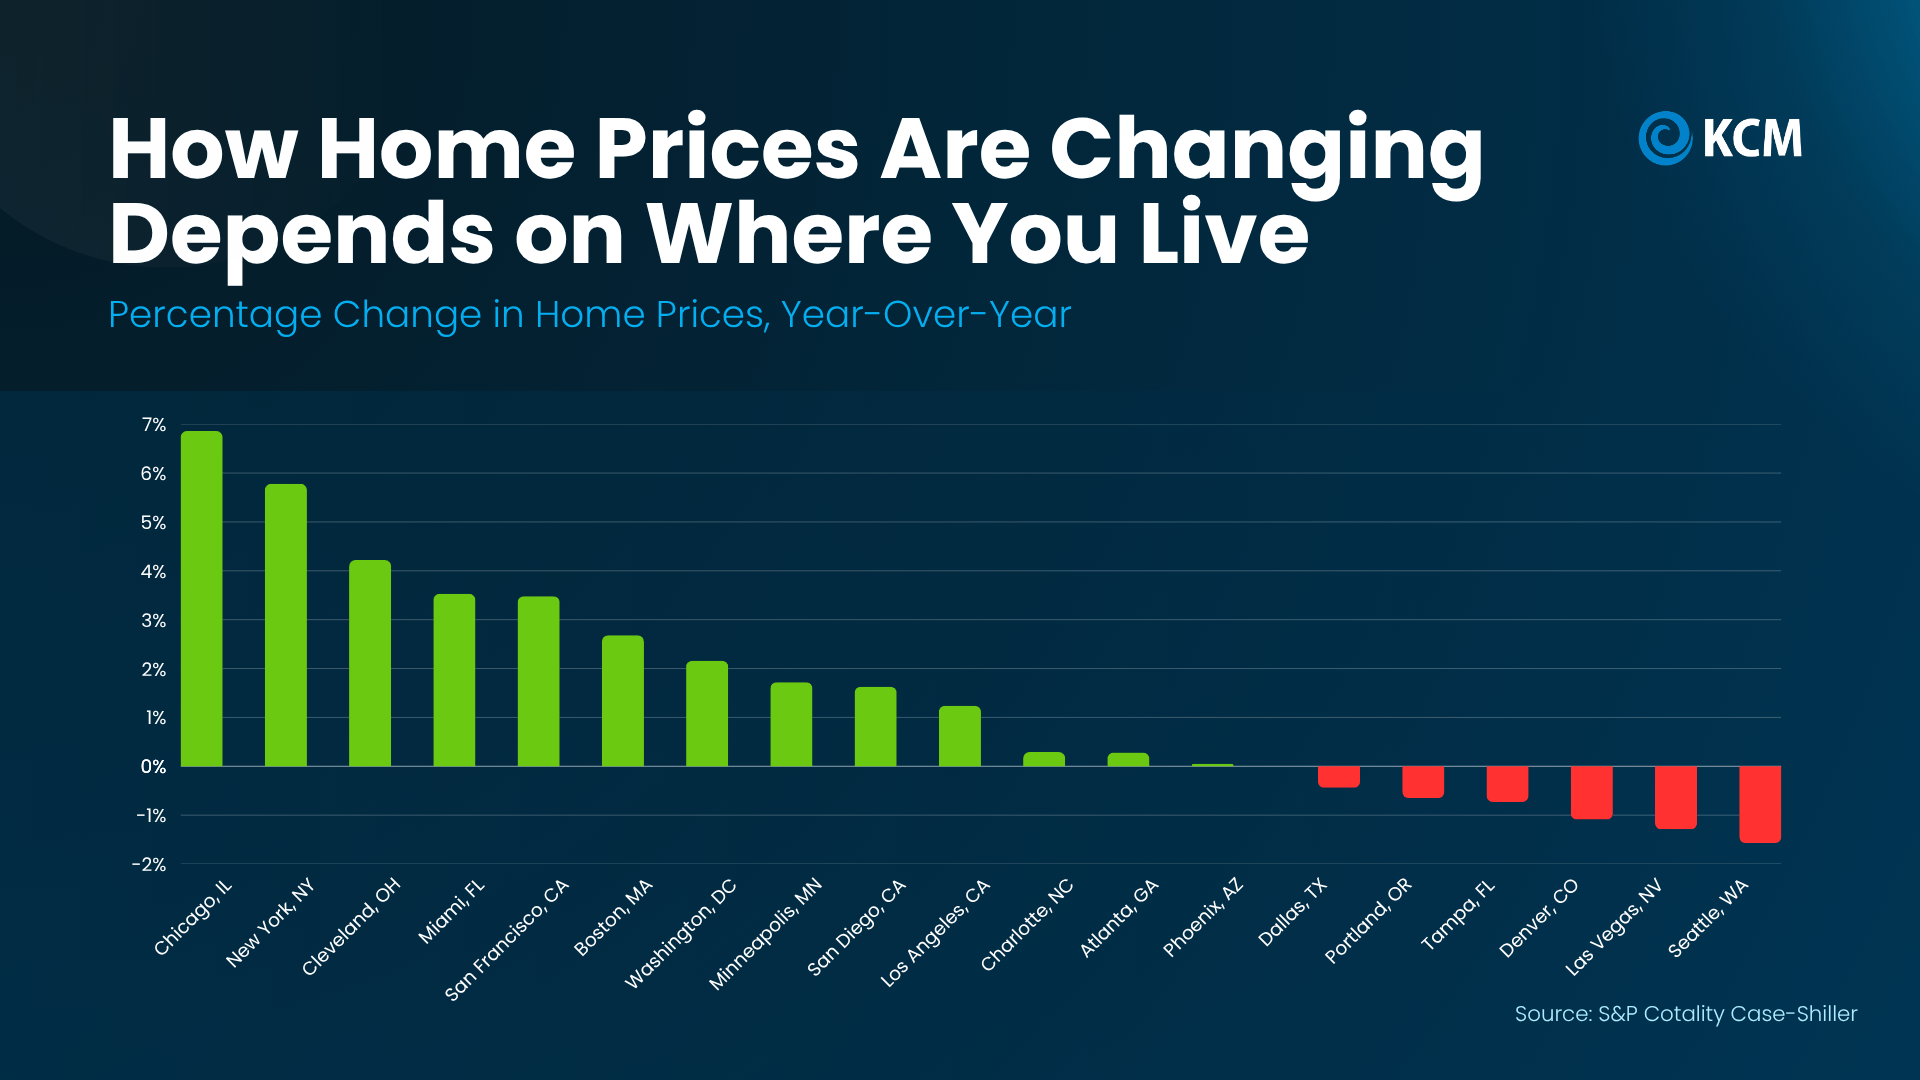
That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.
Why You Don’t Need To Worry About a Crash
Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.
And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):
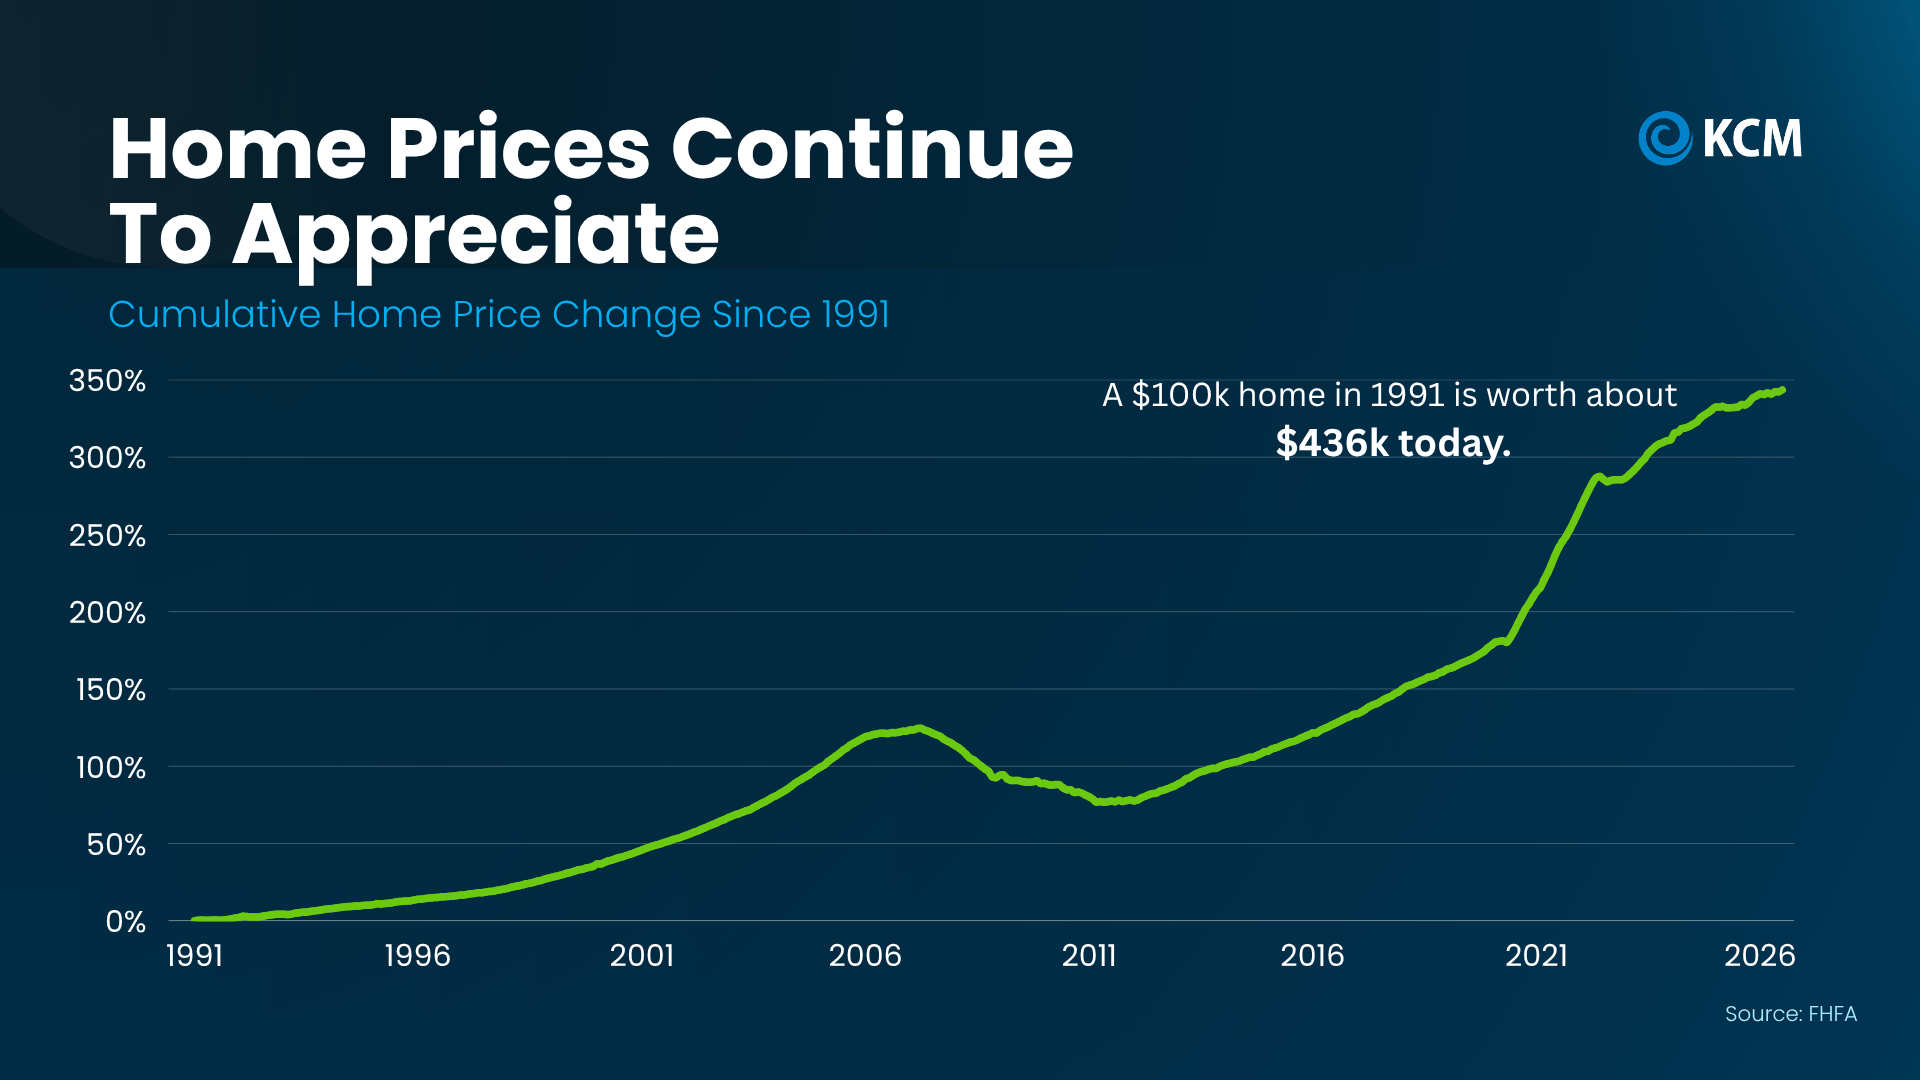
So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.
Bottom Line
National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.
You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.
With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.
So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.
Why the Fed Is Raising Rates
It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.
So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.
-
MYTH: The Fed controls mortgage rates.
-
REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.
As NerdWallet explains:
“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”
Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.
Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
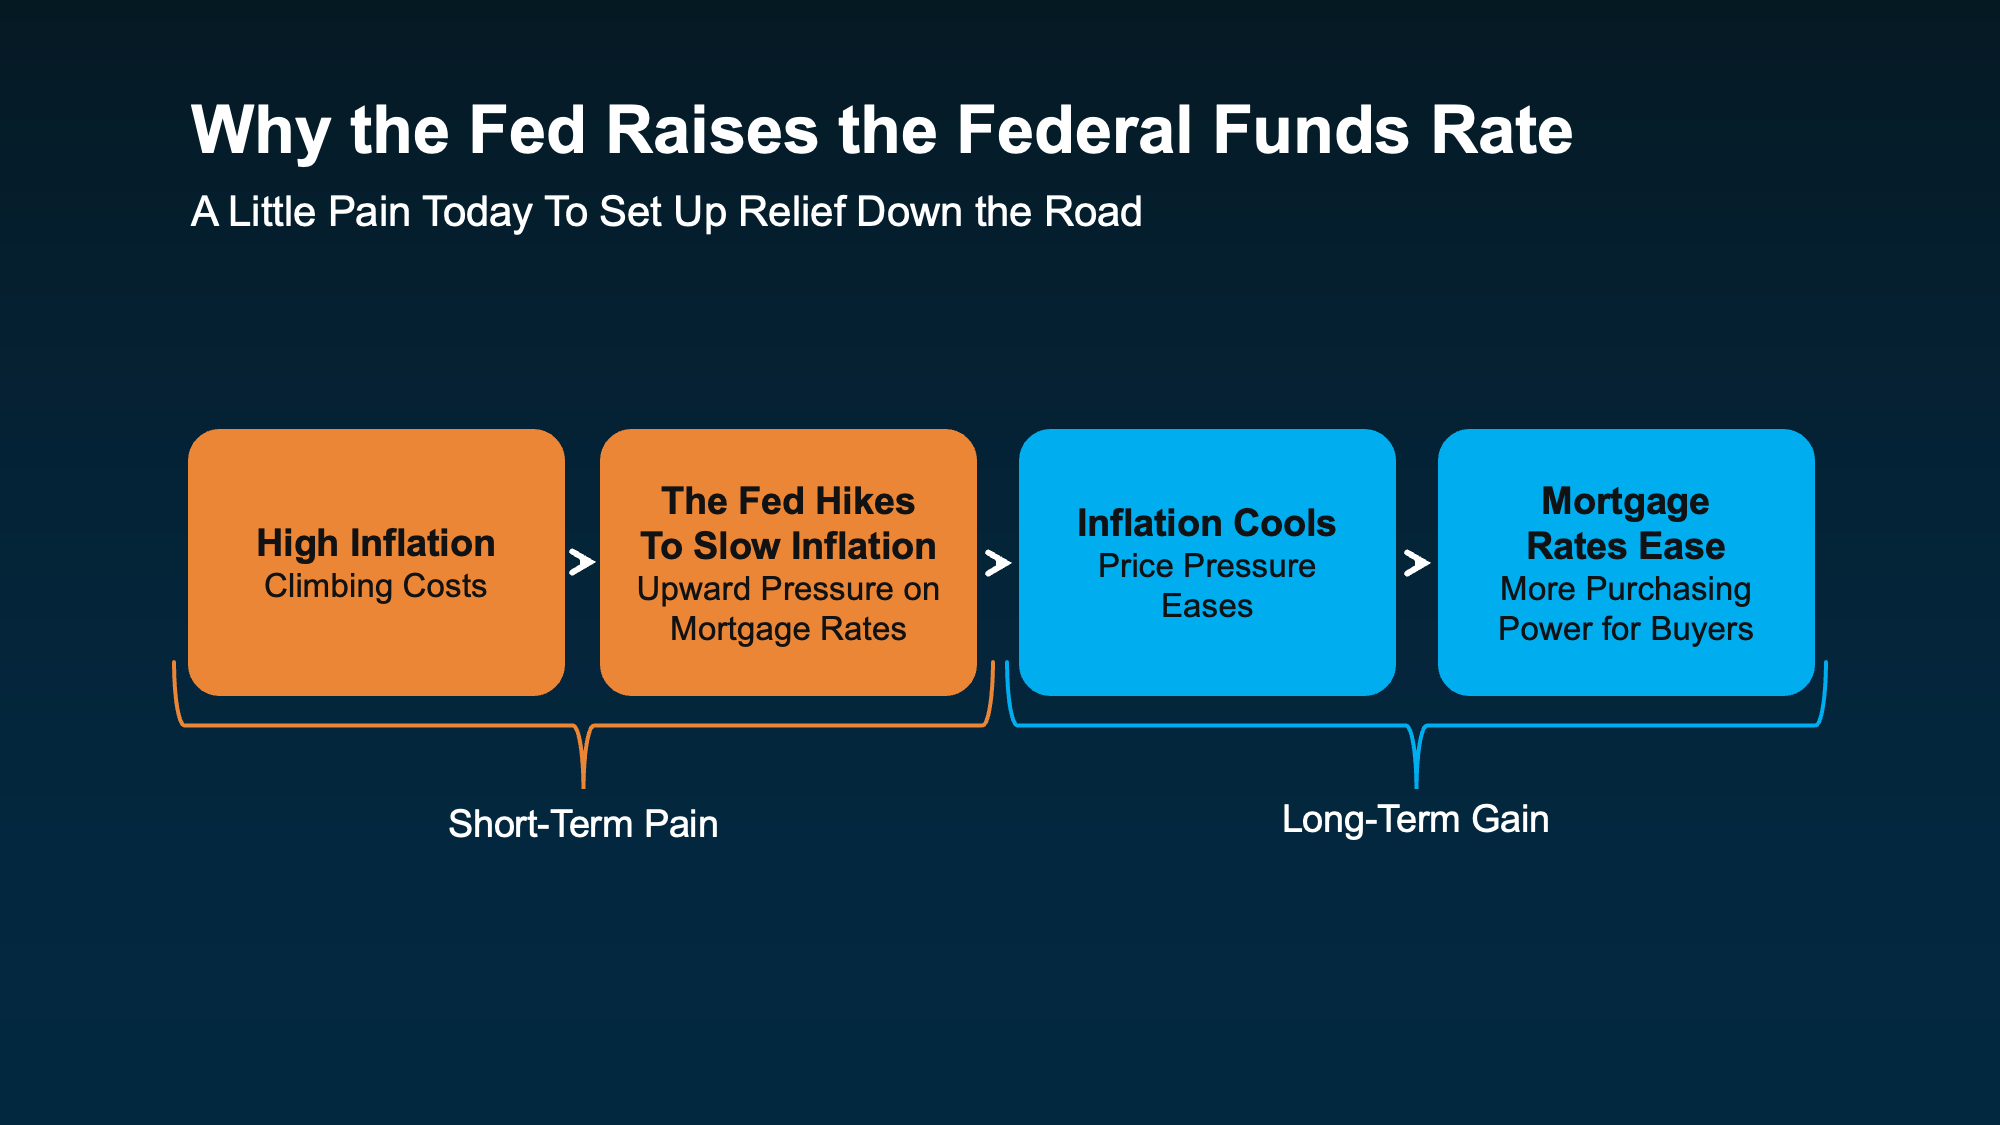
Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.
There’s a Strong Possibility the Fed Will Hike Again This Year
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:
“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“
And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:
-
PCE inflation dropped to 3.4%, down from 3.7% in July.
-
Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.
That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.
How To Make Your Move Work Right Now
While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.
-
If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.
-
If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.
Bottom Line
The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today

To Sell or Rent? How To Choose the Best Path for Your House.

Confused by Home Price Headlines? Here’s Why.


-
 Buying Tips3 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 For Sellers3 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability4 weeks ago
Why So Many Sellers Are Cutting Their Price Right Now
-
 Affordability4 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Affordability2 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Affordability3 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Downsize2 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
-
 Affordability2 weeks ago
Why Most People Are Still Glad They Bought a Home
You must be logged in to post a comment Login