Economy
Is the Housing Market Going To Crash? Here’s What Experts Say
If you’ve seen headlines or social posts calling for a housing crash, it’s easy to wonder if home values are about to take a hit. But here’s the simple truth.
The data doesn’t point to a crash. It points to slow, continued growth.
And sure, it’s going to vary by local area. Some markets will see prices rise more than others. And some may even see small, short-term declines. But the big picture is: home prices are expected to rise nationally, not fall, over the next 5 years.
The Real Story Is in the Expert Forecasts
In the Home Price Expectations Survey (HPES) from Fannie Mae, each quarter over 100 leading housing market experts weigh in on where they project home prices will go from here. And in the report that was just released, the experts agree prices are projected to climb nationally through at least 2029 (see graph below):
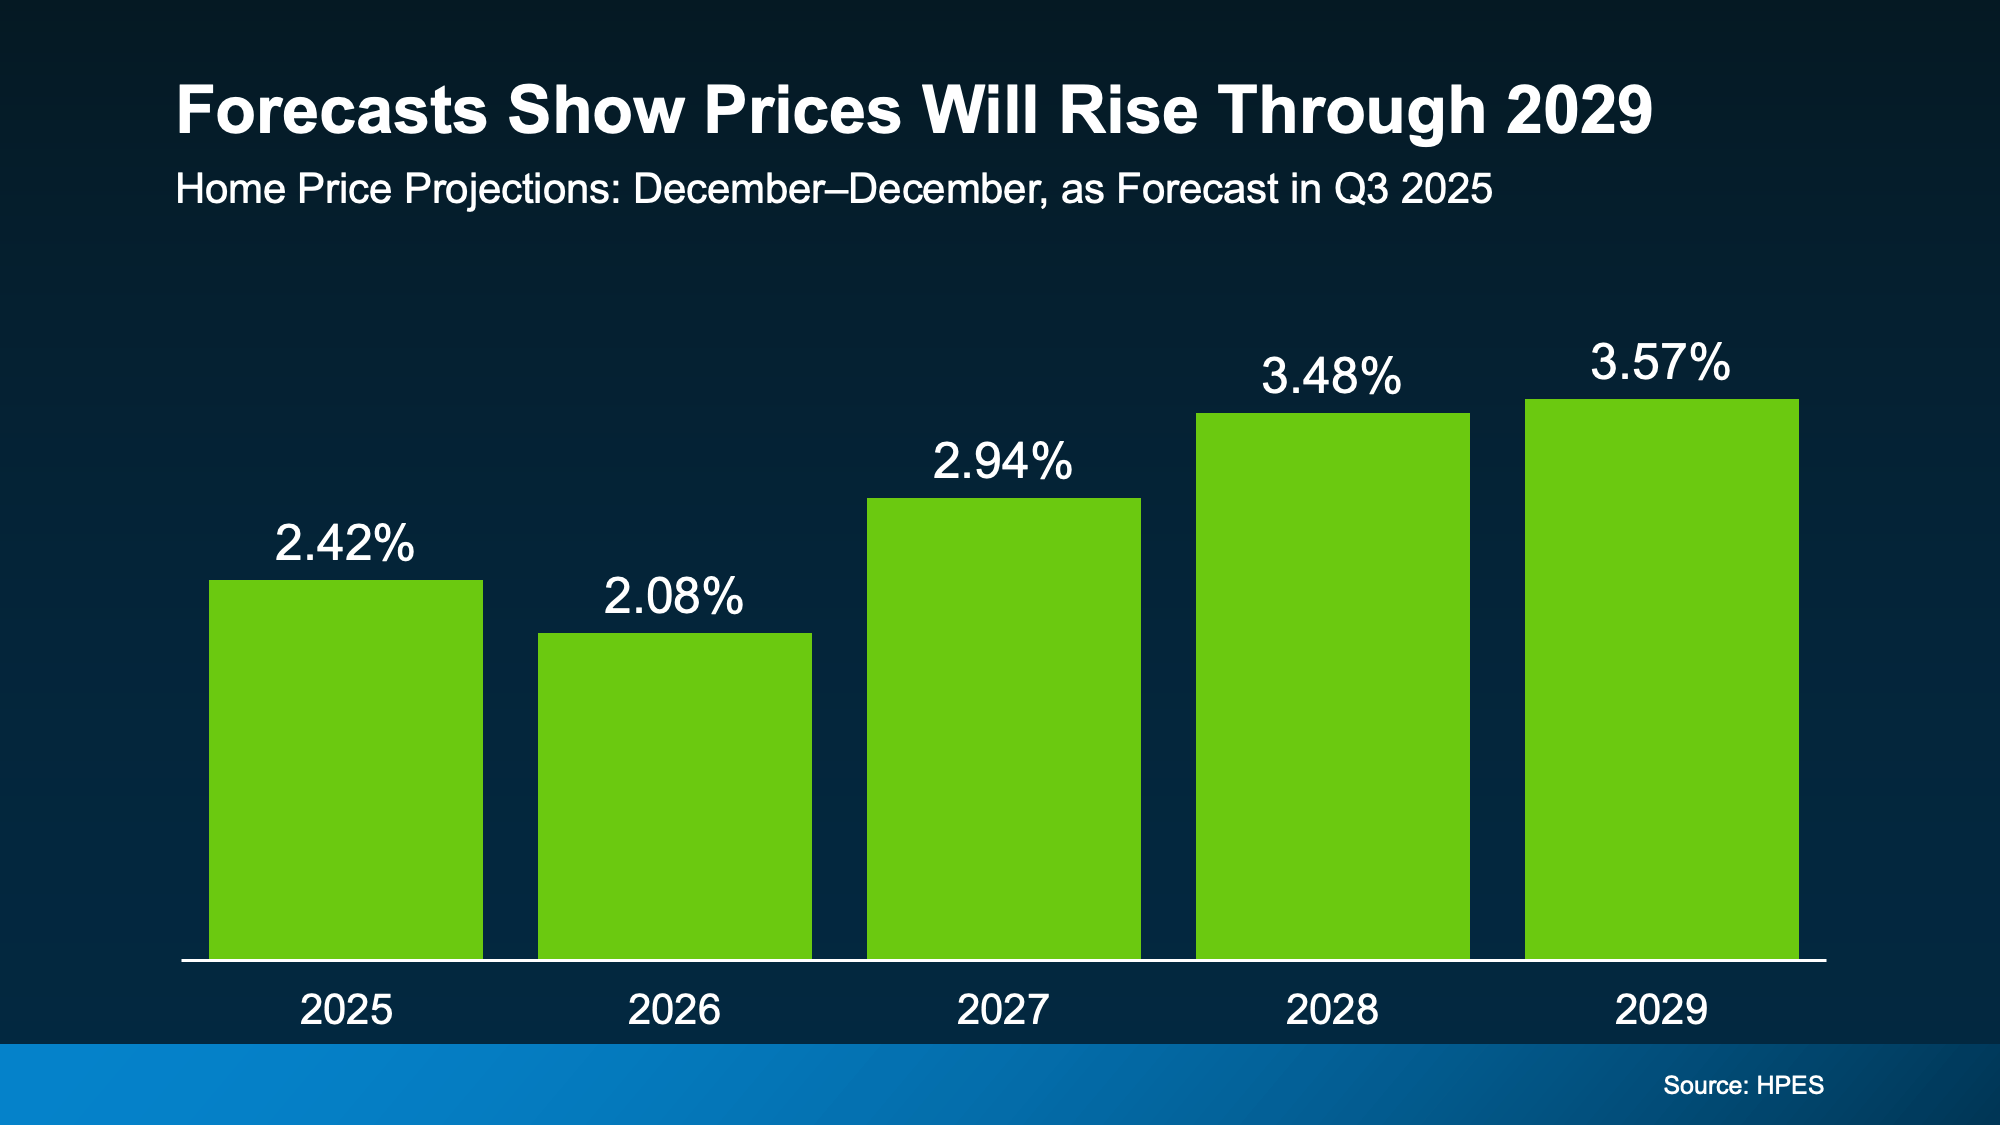 Here’s how to read this visual. Each bar in that graph shows an increase, not a loss. It’s just that the anticipated pace of that appreciation varies year-to-year.
And to further drive this home, let’s look at another view of where prices are and where they’re expected to go. In this version, the expert forecasts are broken into 3 categories: the overall average, the most optimistic projections, and the most pessimistic projections (see chart below):
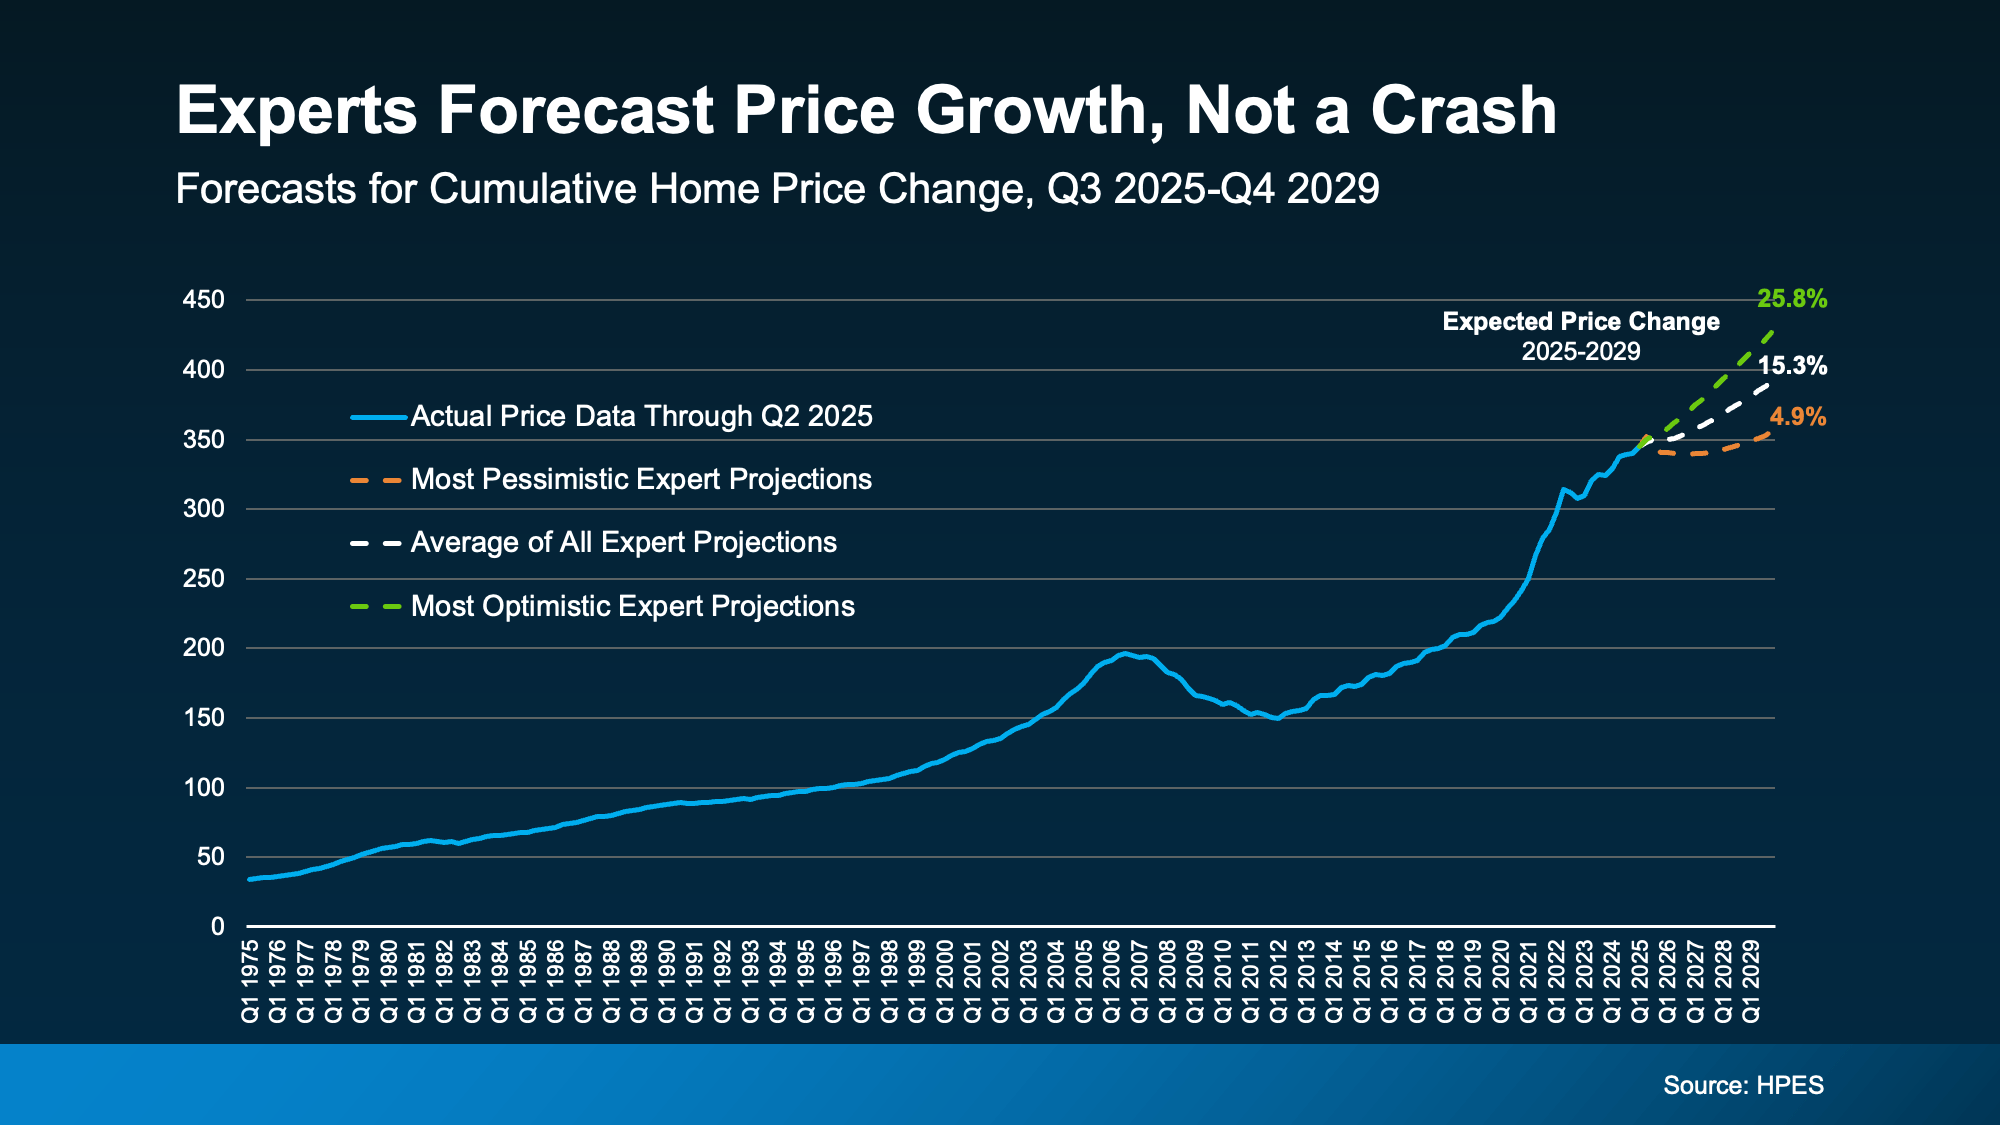 Notice how even the most pessimistic forecasters say we’ll see prices rise by almost 5% over the next few years.
- Overall, prices are expected to rise about 15% from now through the end of 2029.
- The optimists say we’ll beat that and see a roughly 26% increase.
- And even the pessimists anticipate prices will go up by 5% during that period.
What sticks out the most? None of these groups who study the market are forecasting a crash, or even a decline, over the next 5 years.
How This Compares to “Normal” for the Market
Now, focus back on the first graph. The projections call for 2-3.5% price increases in each of the next five years. For context, the average rate of appreciation for the last 25 years was closer to 4-5% annually.
So, while that’s slightly below the historical average, it’s much more sustainable and typical than where the market was in 2020, 2021, and 2022.
Back then, prices rose too much, too fast based on record-low supply and record-high demand. Some places even saw prices climb by 15-20%.
So, while it may feel like prices are stalling compared to those pandemic-era surges, what’s really happening is that the market is finally finding balance again.
Why Prices Aren’t Expected To Crash
A lot of the chatter about home prices today is based on that rapid rise and the old saying that what goes up, must come down. But historically, that’s not really true. Home prices almost always rise.
And the main reason we’re not heading for a repeat of 2008 is simple: supply and demand.
Even though affordability challenges have made it harder for some people to buy over the past few years, there still aren’t enough homes for everyone who wants one. And that ongoing shortage is keeping upward pressure on prices nationally.
That’s why experts across the board can confidently agree: we’re not headed for a price collapse, but for steady, long-term appreciation.
And just in case it’s the economy that’s got you worried, remember this. Over the past 50 years, there have been plenty of economic events that have impacted the market. And one thing that’s consistently been true throughout time is the housing market always recovers. And we’re coming through that turn right now and going into a recovery.
Bottom Line
If you’ve been waiting to buy or sell because you’re worried about a crash, it’s time to look at the data – not the headlines.
The question isn’t if home prices will rise, it’s by how much.
Connect with an agent who can show you what’s happening in your local market and what these forecasts mean for your next move.
If you’re waiting for mortgage rates to fall a lot before you buy, you may be waiting a while. But before you get discouraged, there’s a number working behind the scenes that’s actually good for you right now. It’s called the spread, and once you understand it, you may see today’s rates in a whole new light.
The Pattern That’s Held for 50+ Years
For starters, mortgage rates don’t move on their own. They tend to follow the 10-year treasury yield, a number tied to how investors feel about the economy.
It’s not an exact science, since plenty of other factors can move it day to day, but broadly speaking, when the economy looks strong, that yield tends to climb over time. When the outlook gets shaky, it tends to ease. For over 50 years, the 10-year treasury yield and mortgage rates have moved almost in lockstep (see graph below):

The gap between them is called the “spread.” On average, that gap runs about 1.76 percentage points. And that spread impacts your mortgage rate. A wider spread tends to push mortgage rates higher than the treasury yield alone would suggest, while a narrower spread keeps rates closer to the treasury yield.
One of the Big Reasons Rates Likely Won’t Drop Dramatically Anytime Soon
If you’re hoping mortgage rates will drop a lot, here’s the reality – they probably won’t, at least not anytime soon. One of the big reasons why comes down to that spread between the 10-year treasury yield and mortgage rates.
A few years ago, that gap got a lot wider as uncertainty in the economy pushed it as high as 3.19 points in 2023.
Now here’s the part worth noting – that gap has been narrowing lately. It’s down to about 2.01, just above the long-term average of 1.76 (see graph below):

When the gap is wide, there’s more room for rates to fall. But when it’s relatively normal, like it is now, there’s less wiggle room for rates to fall.
Why Mortgage Rates Aren’t Higher Right Now
Today’s mortgage rate is basically the treasury yield plus the spread. So, when either one moves, your rate moves with it. Here are 3 different rates, all built off today’s 10-year treasury yield of 4.68% to show you just how much the spread matters for your bottom line (see graph below):

If the spread were still stretched out like it was in 2023, rates would be pushing close to 8% right now. That’s because the spread was over a full point wider than it is today.
But now, thanks to the spread narrowing recently, today’s rate sits around 6.69%. That’s the middle scenario in that visual. That’s a big difference in your monthly payment compared what we could see if the spread was as big as it was 2023. As Logan Mohtashami, Lead Analyst at HousingWire, put it:
“Of course, mortgage spreads being better in 2026 is the housing hero story of the year . . .”
Now compare that middle bar to the 3rd one. If the spread were sitting at its exact long-term average, rates would be around 6.5%. That’s only about a quarter of a point away from where rates actually are today. That means most of the improvement in mortgage rates we should realistically expect from a shrinking spread has already happened.
In other words, the same narrowing spread that’s the reason rates aren’t close to 8% today is also a big reason why they’re not likely to fall a lot further.
Bottom Line
That’s the trade-off with a narrowing spread. Rates may not be where you want them, but they’re better than they could’ve been. If you want help figuring out what that means for your monthly payment, reach out to a local lender

Imagine waiting a year to buy a home, only to find mortgage rates haven’t changed much. That may sound frustrating.But it’s a real possibility.
A lot of people are putting their plans on hold because they believe much lower mortgage rates are right around the corner. But, based on today’s forecasts, that may not happen. And you should know that before you decide what to do.
Let’s look at why experts don’t expect a dramatic drop in rates – and the options that could help you buy anyway. Because even if rates don’t fall, you can still move. Here’s how.
1. Mortgage Rates Aren’t Expected To Fall in a Meaningful Way
If you’re waiting for rates to fall, you’re not alone. A recent survey from Clever-Best Interest found 42% of people believe mortgage rates will drop below 5% this year.
The challenge is, that’s not what the experts who study mortgage rates every day are expecting.
Forecasts from Fannie Mae, the Mortgage Bankers Association, and Wells Fargo all show mortgage rates staying relatively steady in the low-to-mid 6% range through at least mid-2027 (see graph below):
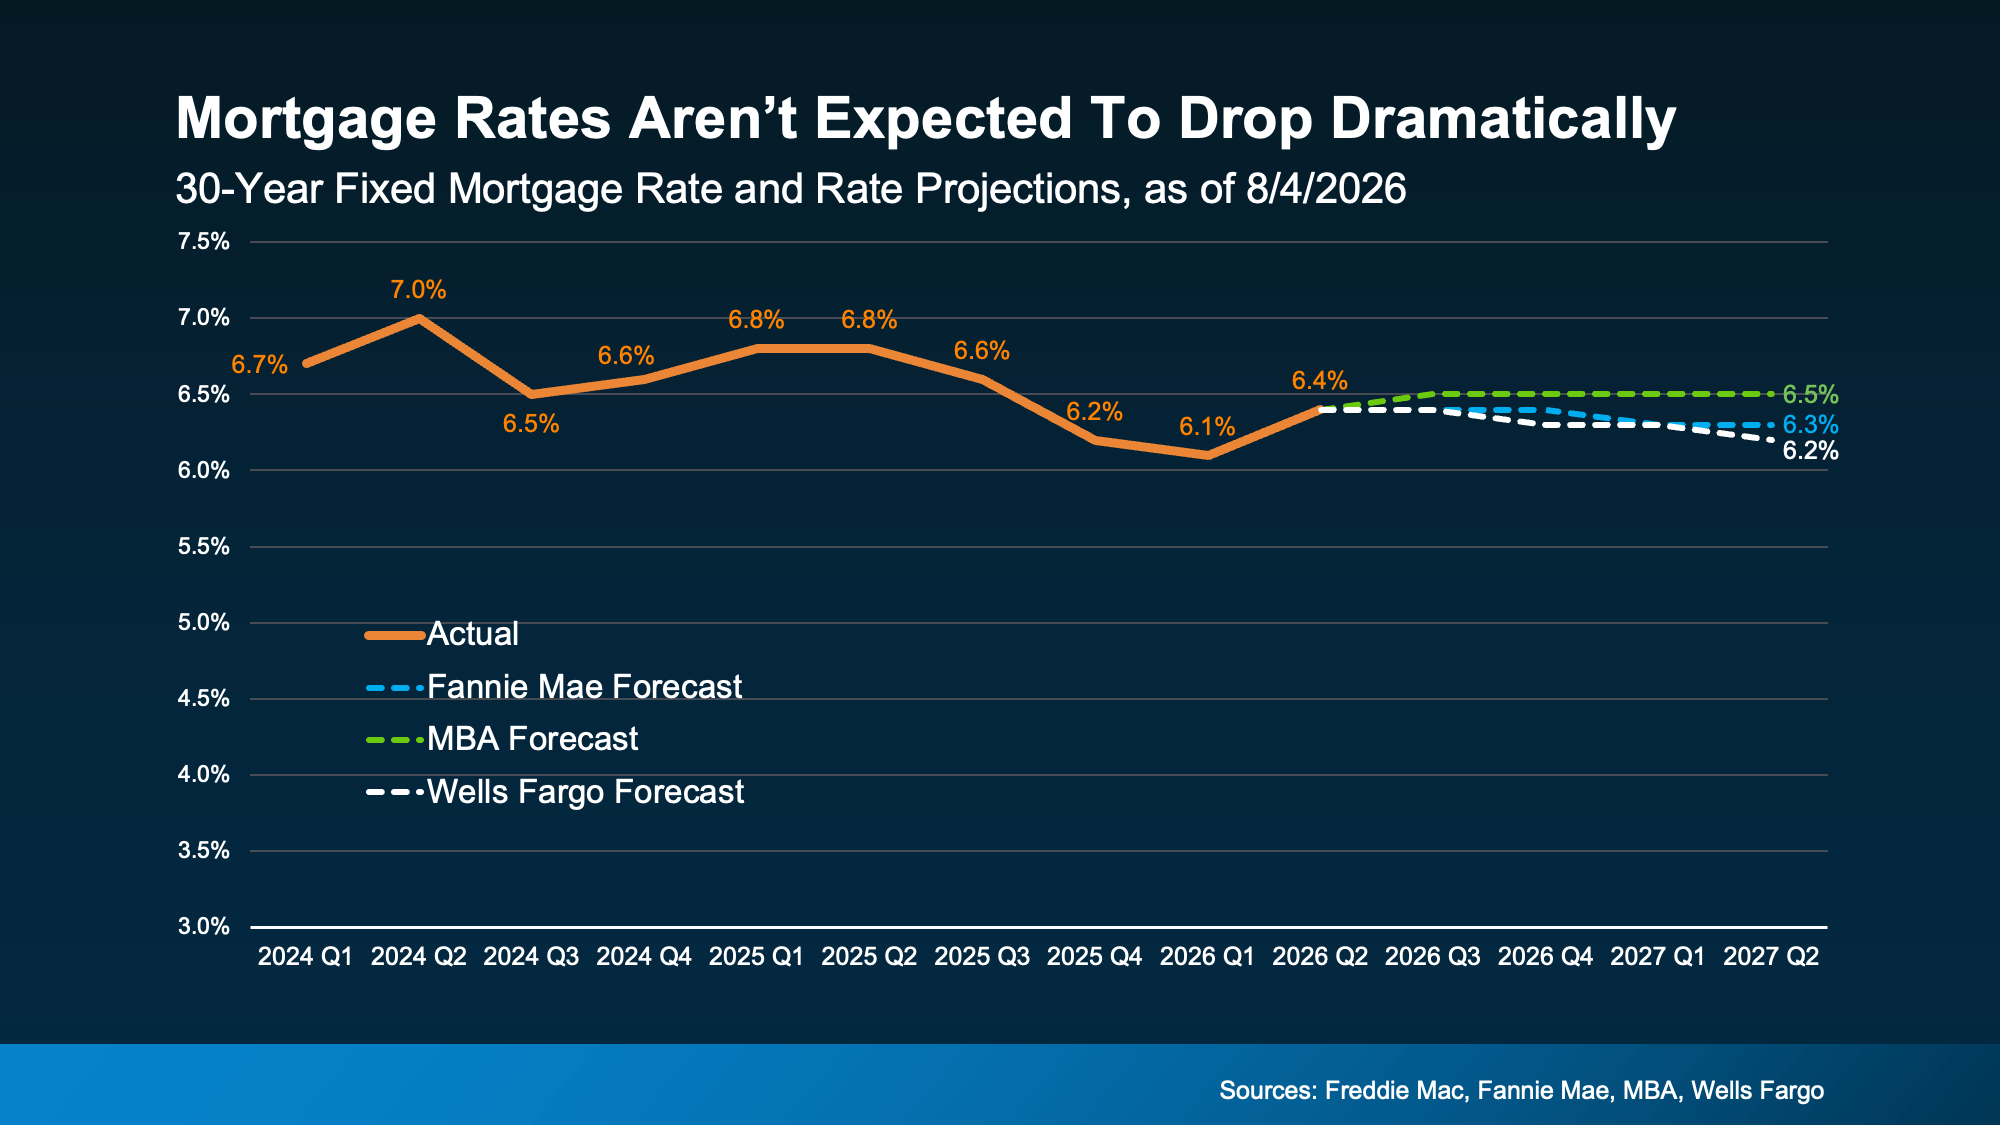
Why? Rates are influenced by inflation, the overall economy, Treasury yields, Federal Reserve policy, global events, and a lot of other moving pieces. And right now, those factors simply aren’t pointing toward the kind of dramatic rate drop many buyers are waiting for.
Could rates move a little? Of course. But if you’re holding out for a bigger drop, today’s forecasts suggest you may be waiting a lot longer than you expect.
2. Inflation Is Still Elevated – And That’s Working Against Lower Rates
One reason experts aren’t expecting rates to fall much? Inflation. Generally speaking, high inflation is the enemy of lower mortgage rates.
And after a period of relative stability from mid 2023 to late 2025, recent data shows inflation has actually been trending higher lately (see graph below):

In other words, one of the biggest ingredients needed for much lower mortgage rates simply isn’t in place today. That helps explain why experts aren’t forecasting the kind of meaningful decline so many buyers are hoping for.
3. Today’s Rates Aren’t High, They’re “Normal”
And this may be the biggest mindset shift of all. The reality is, while today’s rates may feel high compared to a few years ago, they’re not high. They’re normal.
Historically, mortgage rates have spent the majority of their time somewhere between about 5% and 10%. And data from Freddie Mac shows we’re actually well in that range today. It just feels high because we all remember the ultra-low rates homeowners got during the pandemic (see graph below):
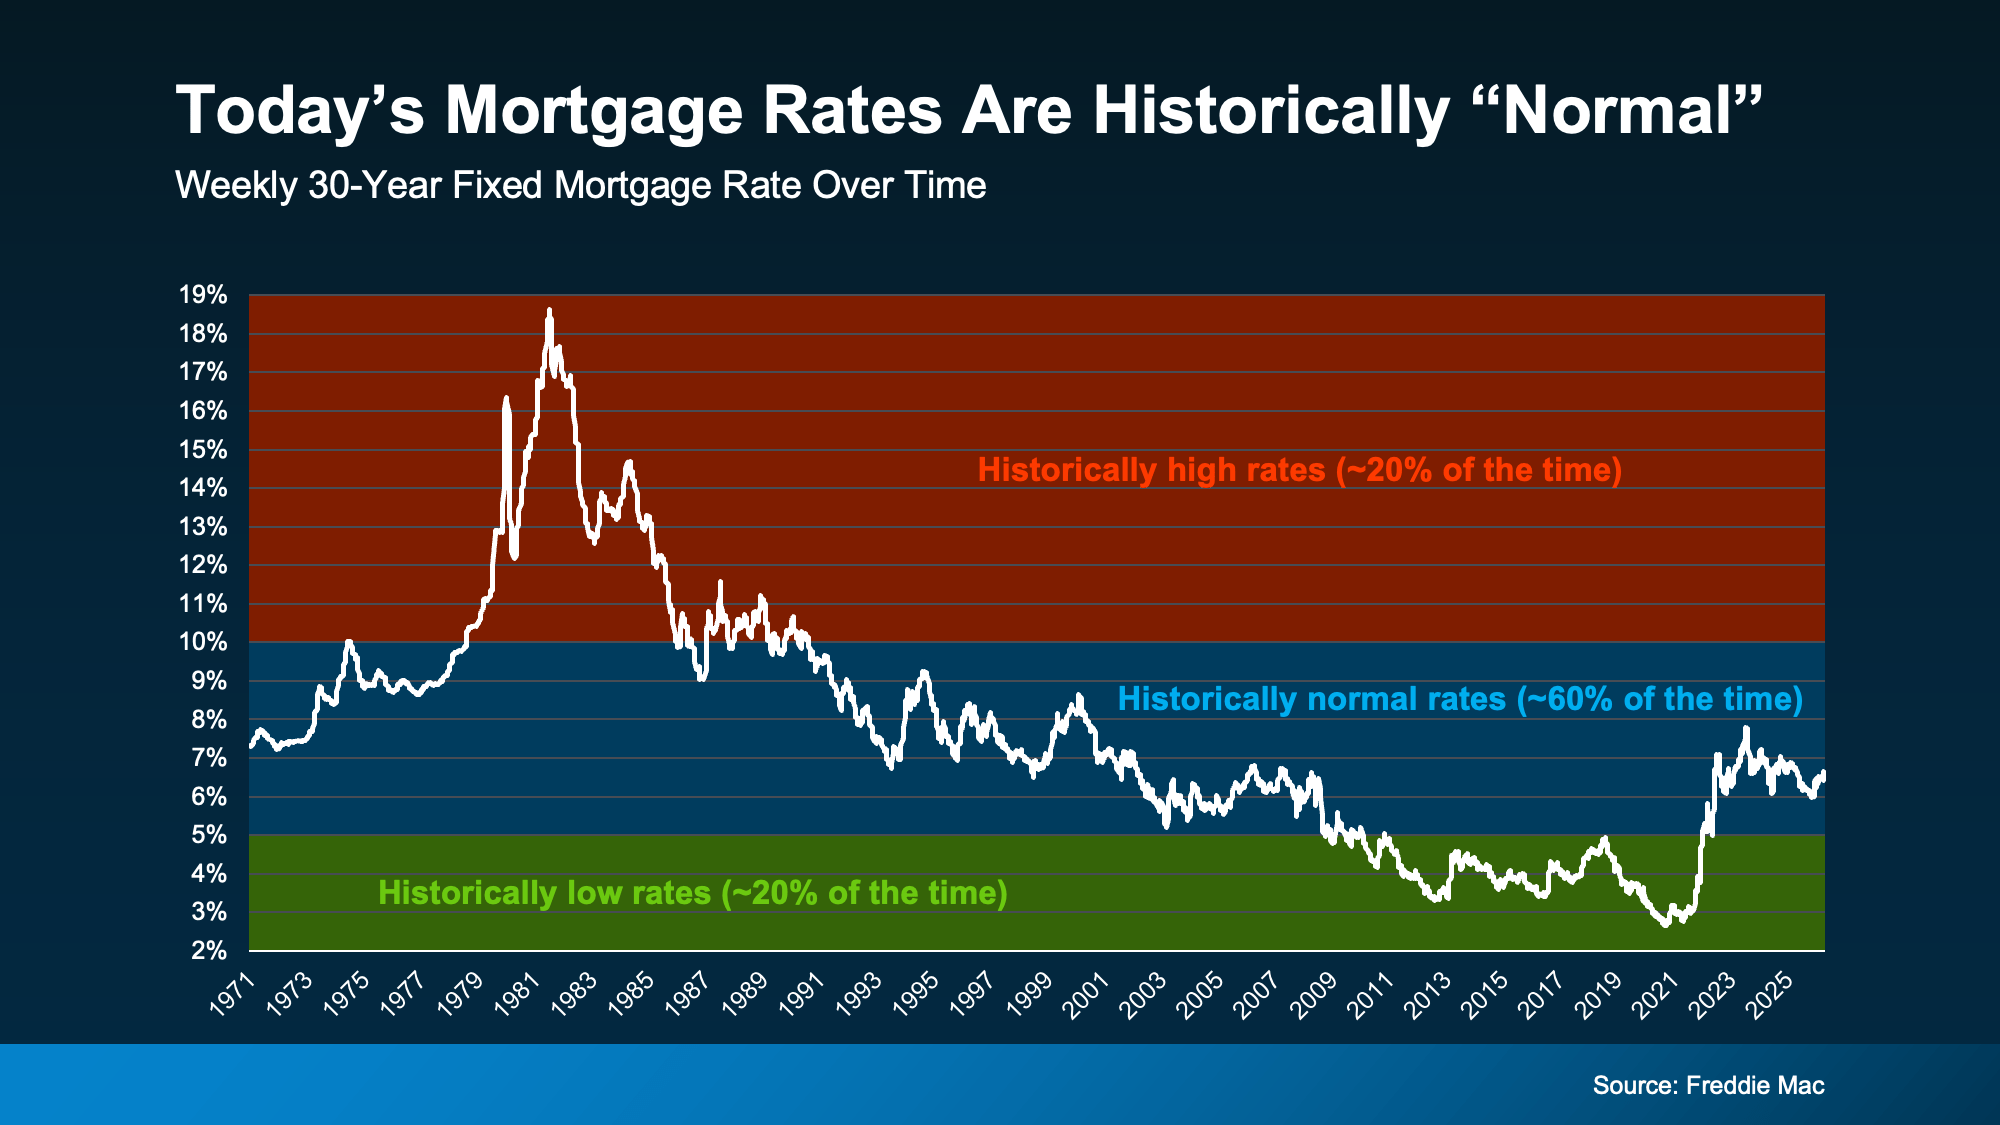
Now, this doesn’t suddenly make a 6% mortgage feel exciting. But it does remind us that waiting for super low rates again may not be a realistic strategy.
So… What Should You Do Instead?
None of this is meant to convince you that you have to buy today. You don’t. But if you need to because something in your life’s changed, there are still ways to find better affordability without waiting for mortgage rates to fall.
-
Check out newly built homes. Many builders are offering incentives to attract buyers, including price cuts, potentially lower rates, free upgrades, and more.
-
Ask about an adjustable-rate mortgage (ARM). If you don’t plan to stay in the home long-term, an ARM may offer a lower initial interest rate than a traditional 30-year fixed mortgage. It’s not the right choice for everyone, but it’s worth asking a lender if it fits your plans.
-
Look into mortgage rate buydowns. This is when you pay upfront to reduce your mortgage rate so you can get for a lower monthly payment without waiting for rates to fall.
-
Find out about assumable mortgages. An assumable mortgage allows you to take over the seller’s existing loan, including its lower mortgage rate.
The important thing is you shouldn’t assume waiting is your only option.
Talk with your real estate agent and lender about whether one of these strategies could be a good fit for you.
Bottom Line
If you’ve been putting your home search on hold because you’re convinced mortgage rates will be much lower soon, it may be worth taking another look at that strategy.
Connect with an agent or lender so you have an expert who can at least walk you through your options and decide whether waiting really puts you in a better position – or just keeps you on the sidelines a little longer.
Buying or selling a home is a big financial decision. And right now, it feels even bigger. Inflation is high, costs are high, and you want to be sure the timing is right before you make your move.
But if you do decide to go for it, whether you’re buying or selling, here’s something reassuring to hold onto. Not only does your move change your own life, but it also gives your whole community a boost.
Real estate is a huge part of the economy. In 2025, it added up to about $5.6 trillion, according to the National Association of Realtors (NAR). A good share of that comes from everyday people buying and selling homes, just like you.
Your Move Puts Real Money Into the Local Economy
Every sale sends money flowing through your area. NAR data shows that buying an existing home (one that’s already been lived in) adds about $64,000 to the local economy. Buy a newly built home, and that number climbs to more than $134,000 (see graph below):
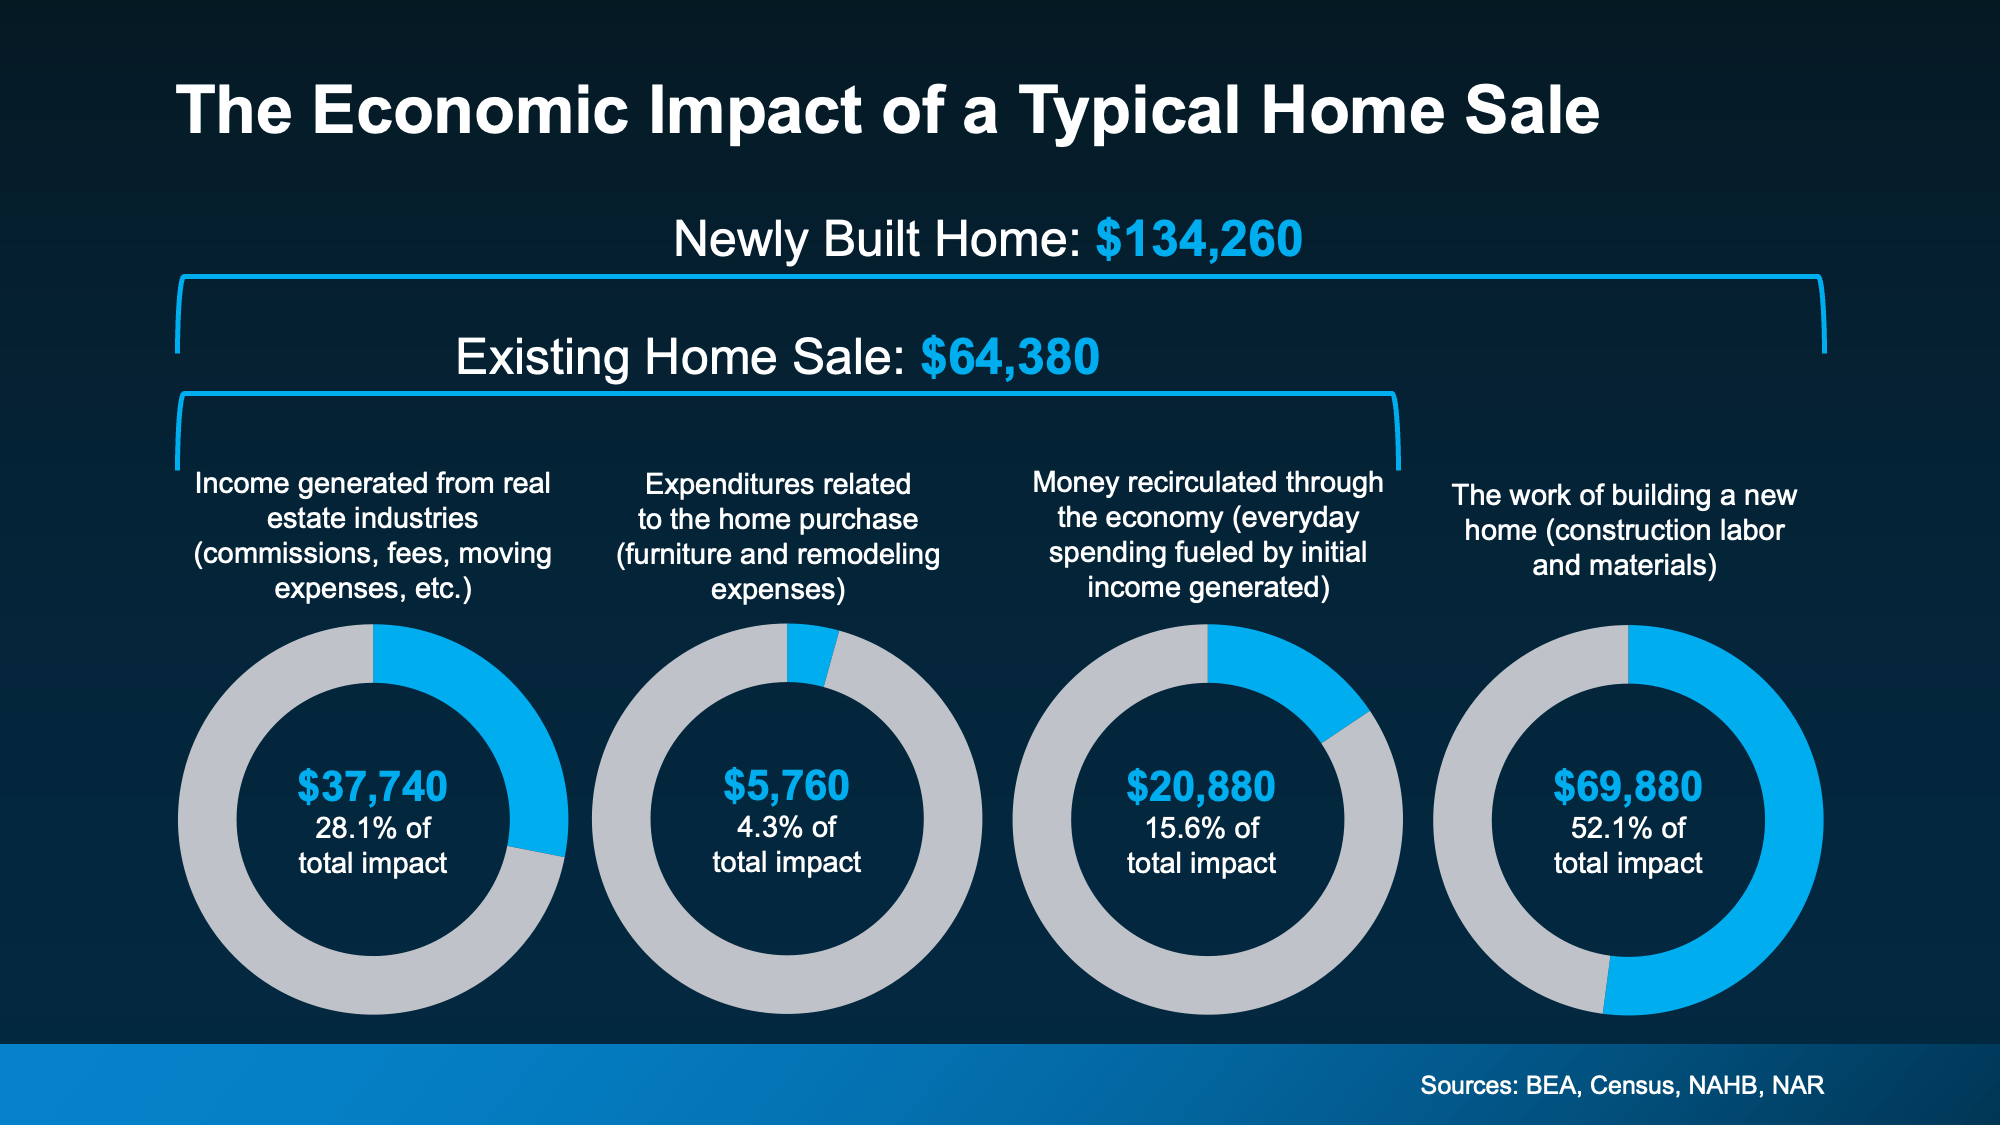
Over half of that comes from the work of building the home itself. The rest flows to real estate services, like agent and lender fees, plus what you spend settling in afterward, on things like furniture and remodeling.
And the money doesn’t stop there. As local businesses earn it, they spend it again in your area, so a single sale ripples further than the sale price alone.
One Sale Keeps a Lot of People Working
Behind every sale is a whole network of people doing their jobs. Contractors, lenders, inspectors, movers, and more. When you buy or sell, you help keep them busy. Lawrence Yun, Chief Economist at NAR, puts it this way:
“Increased home sales mean more economic activity — lawn care, furniture purchases, moving services, mortgage originations and other related business activities all get a boost.“
So, your move supports your neighbors’ livelihoods, too. The deal that gets you into your next home also helps a local crew make payroll. In a year when every paycheck counts, that’s no small thing.
Your Local Impact May Be Even Bigger
What your move financially adds to your community depends a lot on where you live. To help you see how it can vary, here’s a look at the impact of a typical newly built home sale by state.
The national average for a newly built home is about $134,000, but some states see far more (see map below):
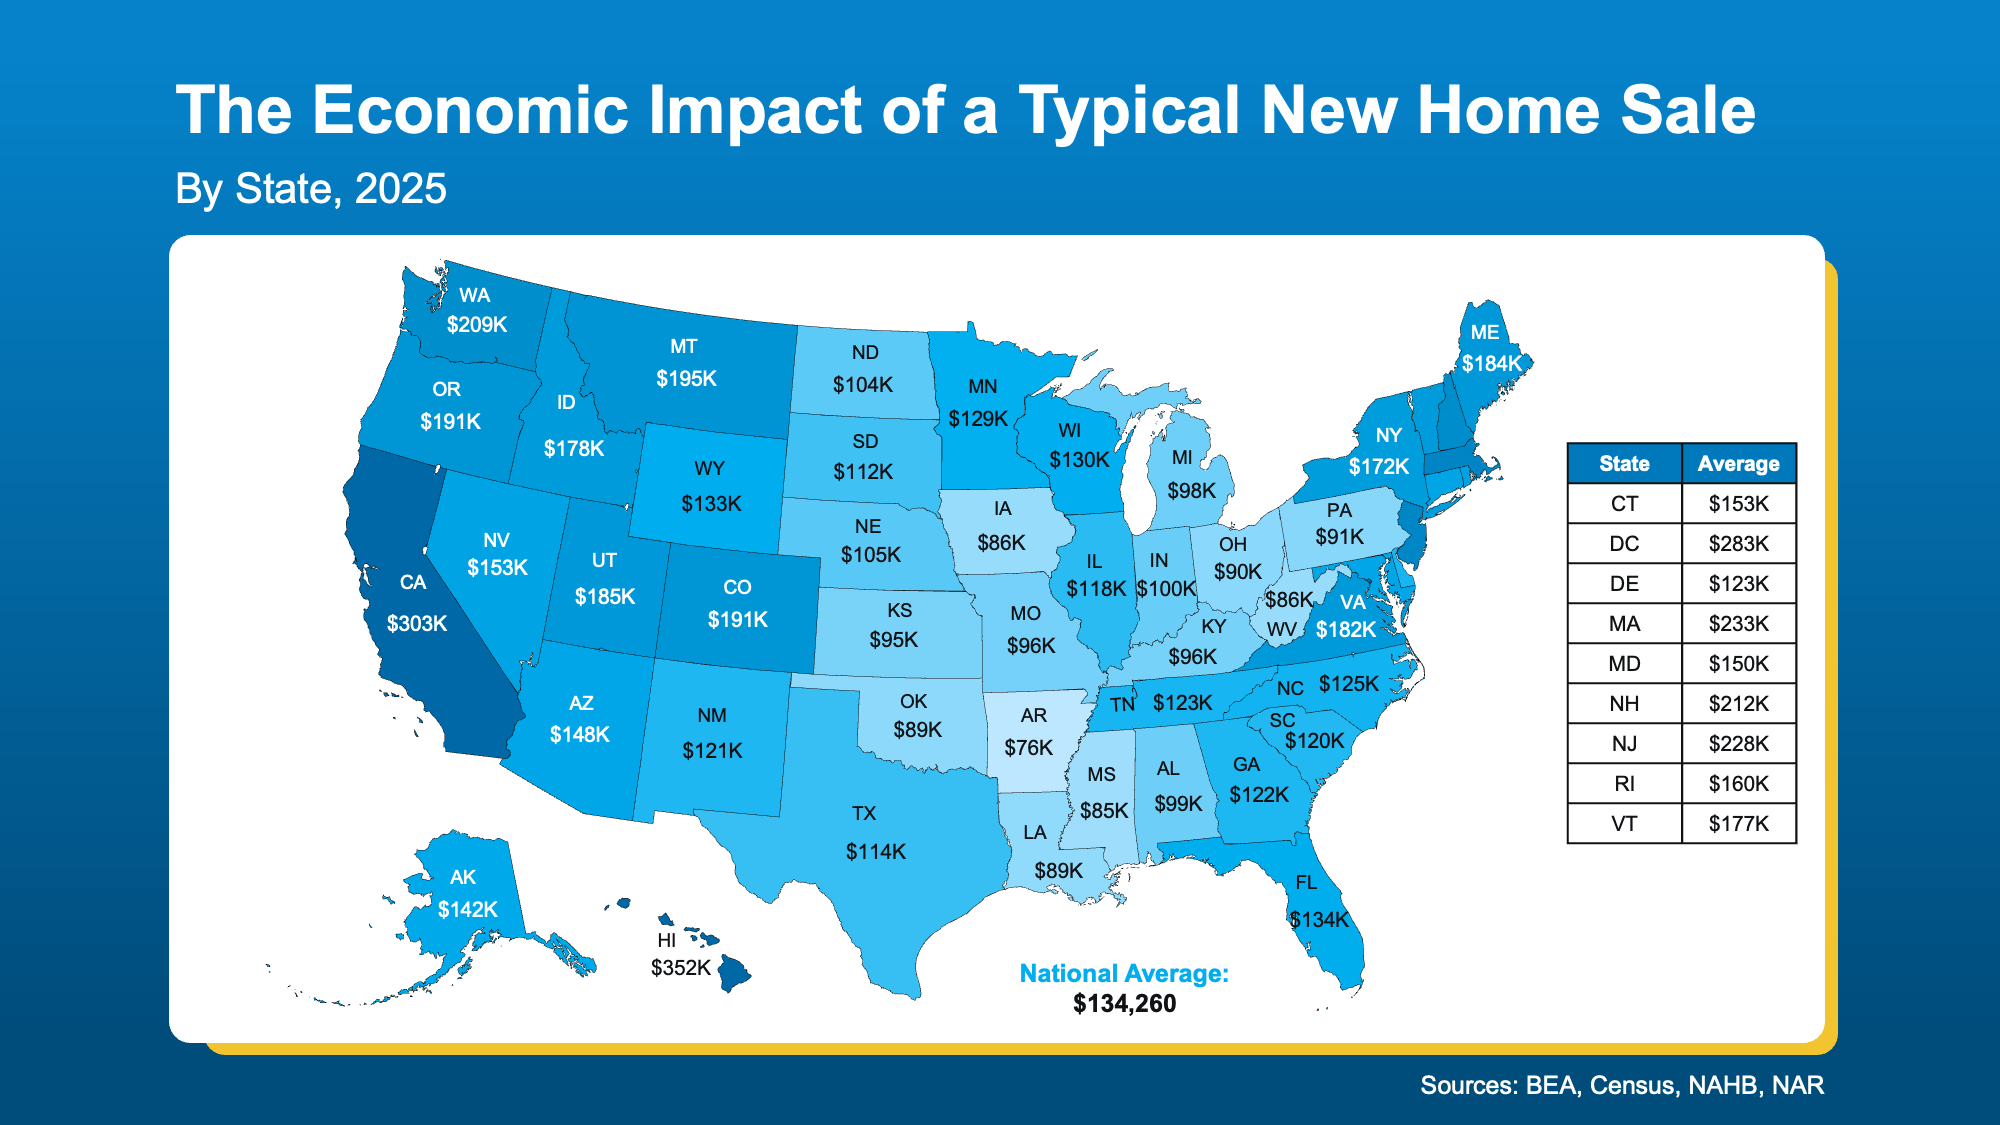
In California, a single sale adds more than $300,000 to the local economy. In Hawaii, it’s over $350,000. Even in the most affordable states, the number lands in the tens of thousands.
Want to know what a move would mean where you live? A local agent can show you the figure close to home.
Bottom Line
Moving is both a personal milestone and an investment in your community. So, if the time is right for you, connect with a local agent. You’ll make a difference for more people than you know.

Why So Many Sellers Are Cutting Their Price Right Now

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

3 Things You Can Actually Control About Your Mortgage Rate Right Now


-

 For Buyers4 weeks ago
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
-
 Affordability4 weeks ago
Sellers Are Cutting Prices To Meet Buyers Where They’re At
-
 Affordability4 weeks ago
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
-
 Affordability3 weeks ago
Why Buyers Shouldn’t Overlook a Fall Move
-
 Affordability3 weeks ago
Think New Homes Cost More? Not Right Now.
-
 Affordability3 weeks ago
Remote Work Could Be Your Affordability Answer
-
 For Buyers2 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
-
 Agent Value2 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
You must be logged in to post a comment Login