
Buying Tips
Who Has the Upper Hand in Today’s Housing Market?
Ask around and almost every homebuyer out there wants to know if there’s a way to get a better deal. And just about every seller wants to know if they’ll still get top dollar.
The interesting thing is… both can be right at the exact same time. It just depends on where you live.
That’s because today’s housing market isn’t moving in one direction anymore. Some markets clearly favor buyers. Others still favor sellers. But most are sitting somewhere in the middle.
And knowing which market you’re actually in can completely change the strategy you use to buy or sell (and what expectations you should have). Let’s break it down.
One Number Tells You Who’s Got Leverage
So how do you know which market you’re in? There’s one number that tells the story faster than anything else: the months’ supply of homes for sale. It’s the clearest signal of who’s got leverage – and what strategy you’ll need. Think of it like this.
Imagine no additional homes were listed starting today. Months’ supply tells us how long it would take to sell everything that’s currently on the market based on today’s demand.
Generally speaking, if months’ supply is:
-
Fewer than 4 months: Sellers usually have the advantage.
-
4 to 6 months: Buyers and sellers are on more equal footing.
-
More than 6 months: Buyers can usually negotiate for a better deal.
Right now, the National Association of Realtors (NAR) data says that number is 4.6 and that puts the overall market back in balanced territory (see graph below):
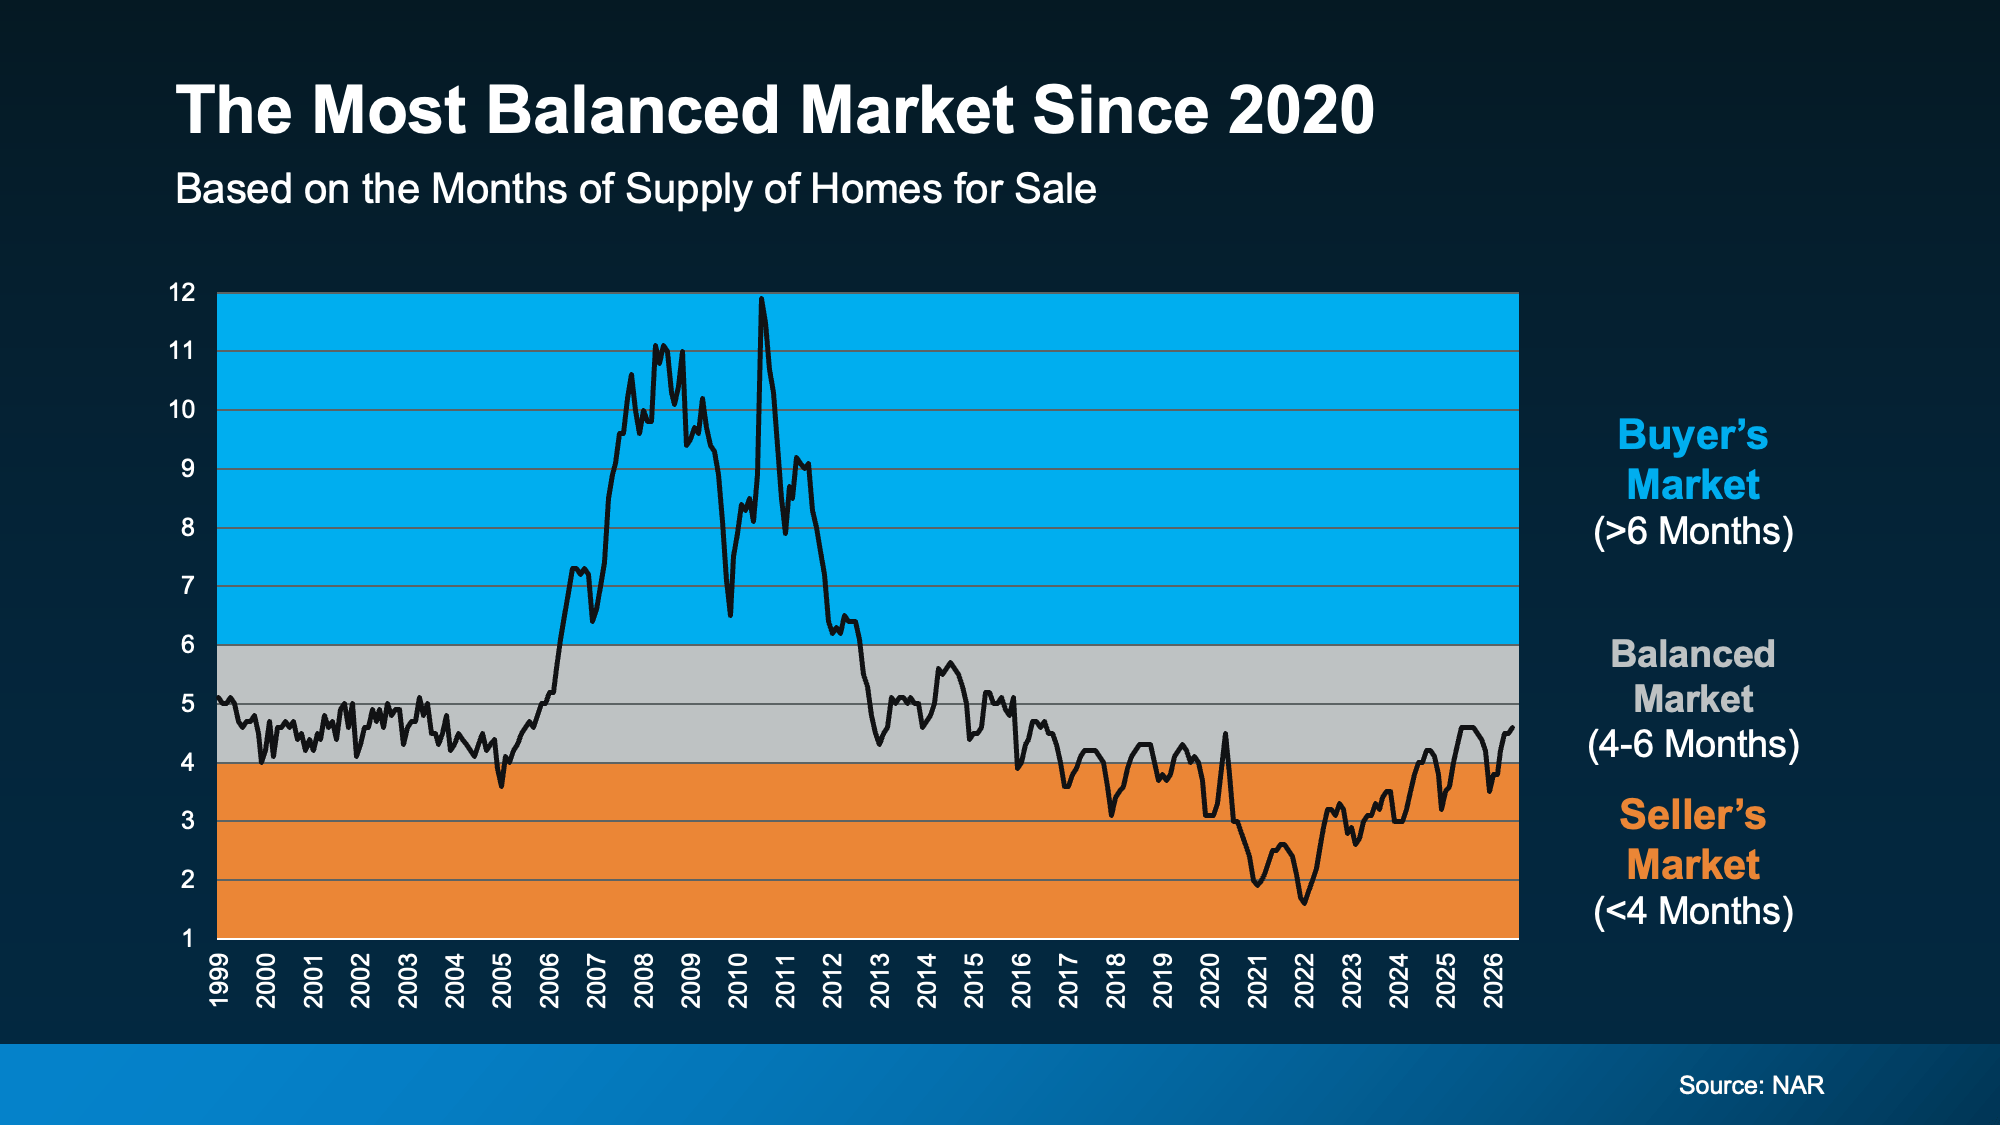
That means, as a whole, the market has finally moved back into a much more balanced range after years of being tilted in sellers’ favor. While that may look like the scales have tipped only slightly, it’s enough to make a real difference in what strategy you’ll need for your move – at least in most places.
The Tale of Two Markets: Why ‘Balanced’ Doesn’t Mean the Same Thing Everywhere
Redfin data helps shed some light on how this shakes out across the country. It breaks down which cities are leaning in either direction (see graph below).
-
Some markets give buyers more leverage. Those are in blue.
-
Some still favor sellers. That’s the orange.
-
Others fall somewhere in between. Those are gray.
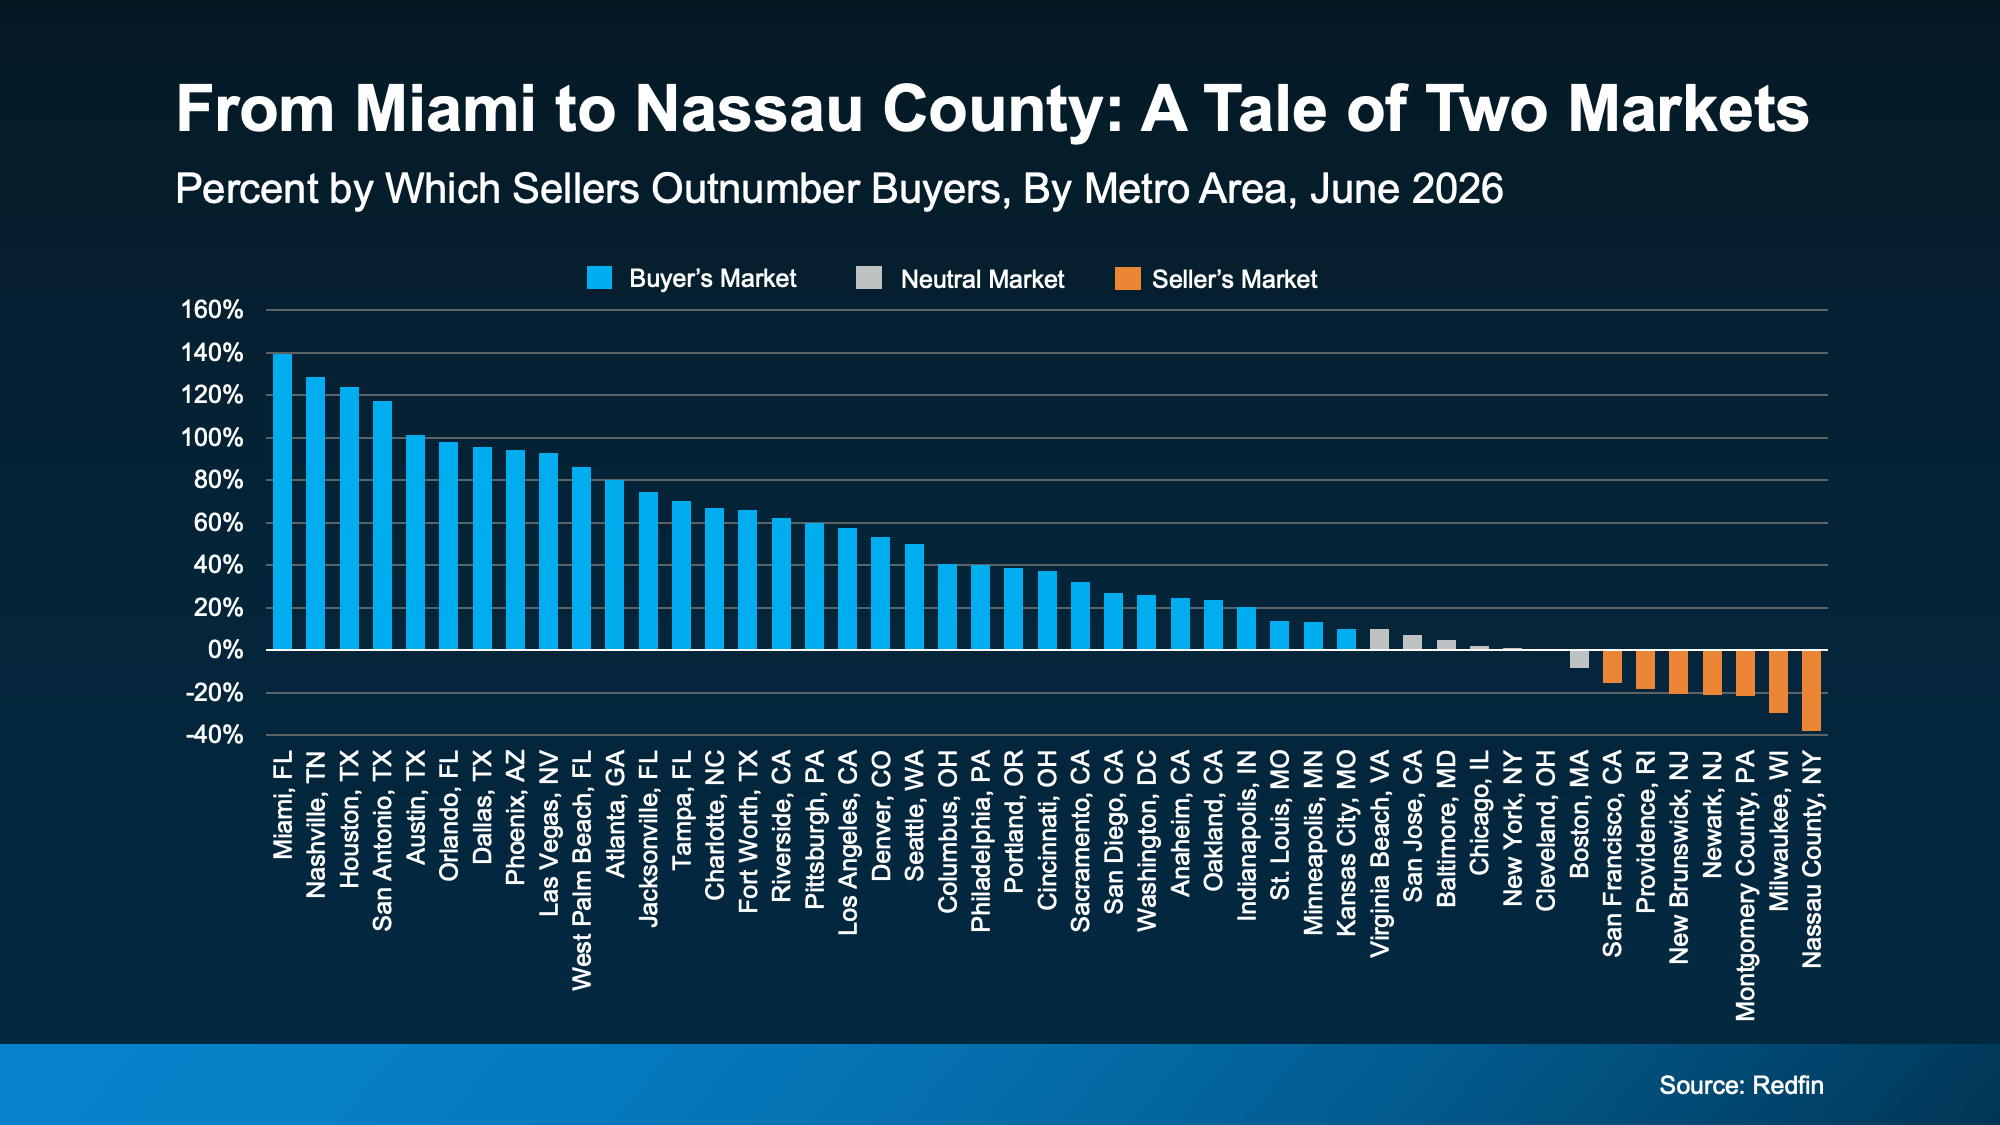 Notice anything? A lot more places are seeing more buyer-friendly conditions right now. In fact, this is the most buyer-friendly market we’ve seen in nearly 6 years.
But don’t take that as buyers have the upper hand everywhere.
There are still cities where sellers still have the power. And if you’re in one of them, your approach to selling or buying looks completely different than it would in a buyer-leaning market.
The Biggest Mistake You Can Make Right Now
That’s why the biggest mistake isn’t thinking it’s finally a buyer’s market. And it isn’t thinking it’s still a seller’s market either. It’s making any assumption without talking to an expert agent first.
Today’s market is incredibly local. In one market, a buyer may be getting thousands of dollars in concessions from a seller. And a homeowner may have to consider dropping their price.
But in another, a buyer may be stressed about coming in with their best offer, or they may lose out on the home to another buyer. And a seller may still be seeing strong demand and prices inching higher.
Same overall housing market.
Very different experiences.
The truth is what’s happening in your back yard affects everything from pricing your house to making an offer to negotiating repairs or concessions. And that’s why an agent’s local knowledge matters more now than ever before.
Your plan has to be based on your neighborhood – and only an agent has the expertise to get that right.
Bottom Line
This market isn’t one-size-fits-all.
If you’re wondering who has the upper hand where you live, talk to a local agent. They’ll help you understand what’s happening in your market, who’s got the leverage, and what strategy gives you the best shot at getting what you want.
For most first-time buyers, the hardest part of buying a home is making the numbers work. You budget, you save, and the finish line still feels far away.
But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don’t.
You’re not tied to living where the jobs are, so you can look where your money goes further.
Where You Work Doesn’t Have To Dictate Where You Live
Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth.
More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it:
“Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new.”
And you can use that freedom to look somewhere more affordable.
Your Paycheck Goes Much Further in Some States
Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford (see map below):
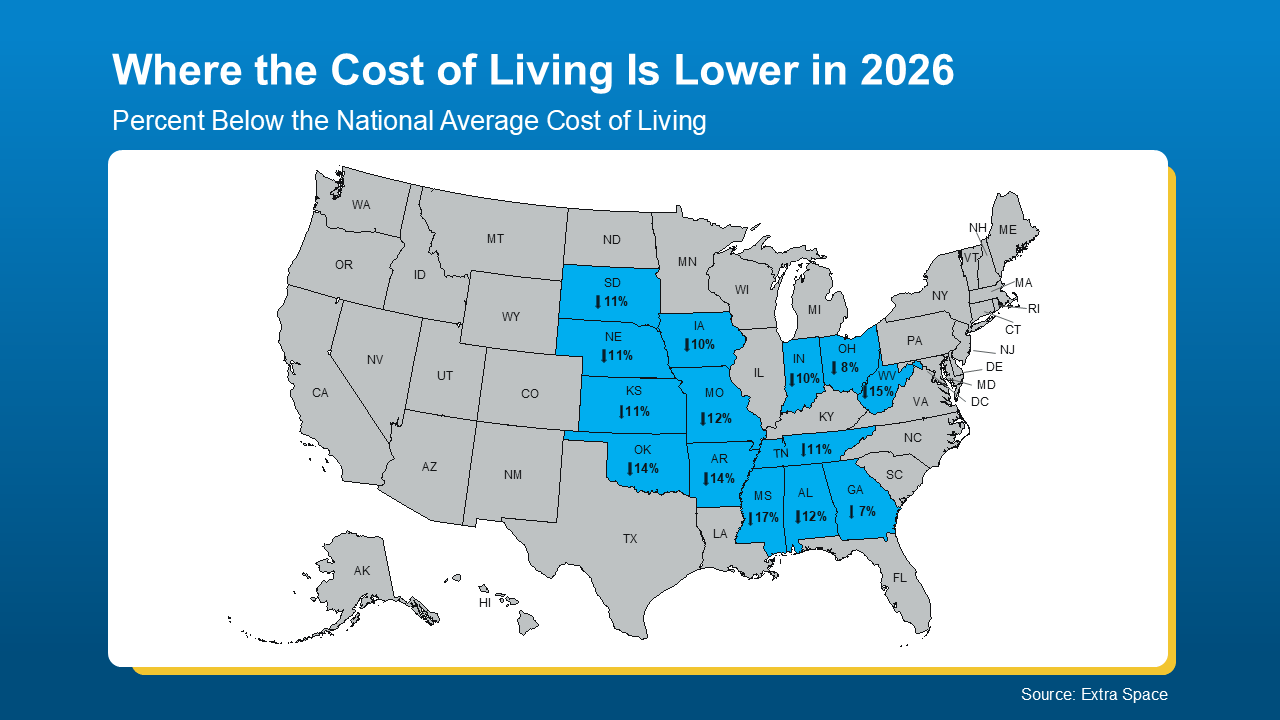 Take Mississippi, for example, where the cost of living sits about 17% below average, or West Virginia at roughly 15% below. When day-to-day life costs less, you can put more of your income toward your goals, homeownership included. Relocate Right describes it this way:
“Remote work has fundamentally changed the calculus of where to live. When your employer is in San Francisco, but you can work from anywhere, the question is no longer ‘where are the jobs’ but ‘where does my salary go furthest and what kind of life can I build.'”
For a first-time buyer, working remotely could be a chance to put down roots and finally buy. Because with that kind of flexibility, you get to choose where to live and which places work best for your life and goals.
What To Weigh Before You Go
A lower cost of living is a great start. But it’s also important to consider the things a budget spreadsheet won’t show you, because a place can look like a great fit on paper and still not feel like home.
-
Is the internet fast and steady enough to do your job without interruptions?
-
Will it be easy to make friends and settle into a routine once you arrive?
-
Does it have the amenities you want, like public transportation or decent takeout?
This is where a local real estate agent comes in. They can help you weigh a big move against a nearby one, because every state has more affordable pockets. Sometimes they’re closer than you think.
An agent will know which neighborhoods fit your budget and have the features you’re after, whether that’s walkability, good restaurants, parks, or a nearby farmer’s market.
Bottom Line
With remote work, where you live can be your decision instead of your employer’s. And that puts more affordable places within reach.
Want to explore where that could take you? Connect with a local real estate agent to see what’s possible.
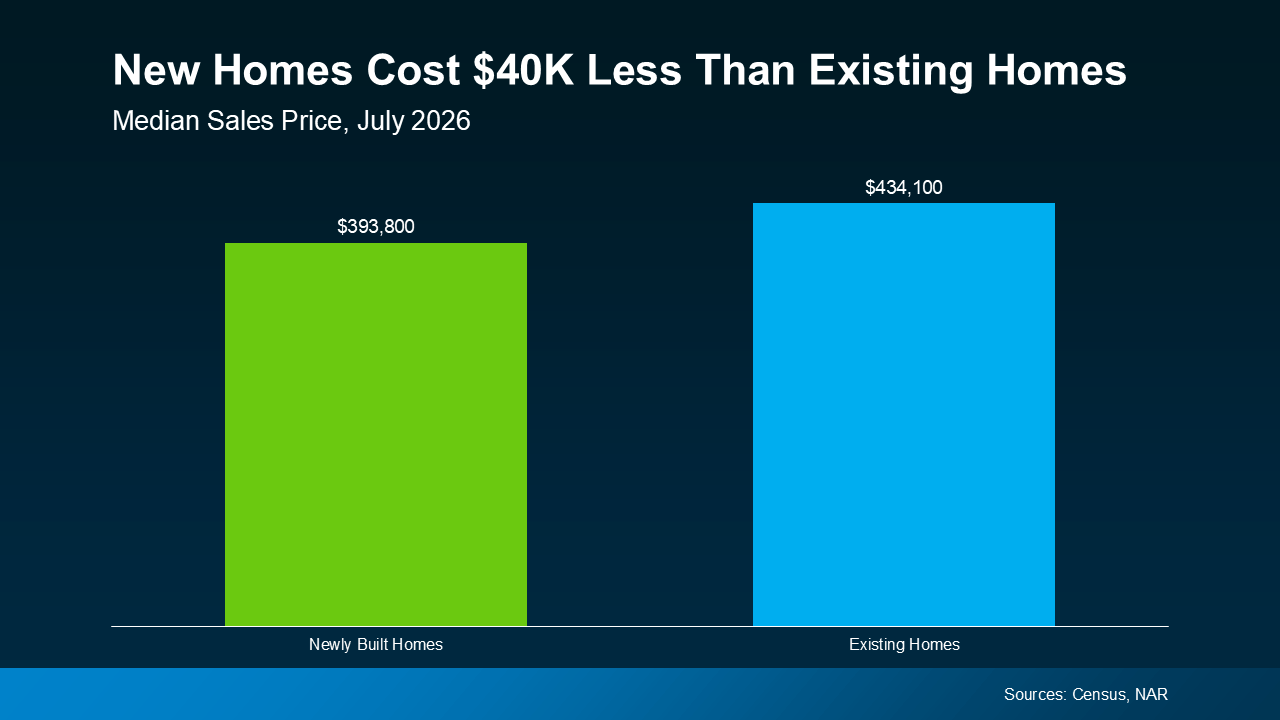
Most people think a newly built home costs more than an existing one. But right now, that’s actually backwards. Newly built homes are more affordable than existing ones in a lot of markets. And that’s because builders are cutting prices and stacking on incentives to try to keep their inventory moving.
Here’s why that’s really important for any would-be homebuyer to know.
Newly Built Homes Are the Better Deal Right Now
According to the latest data from the Census and the National Association of Realtors (NAR), a newly built home now typically costs about $40,000 less than an existing one (see graph below):
 Builders aren’t like homeowners who can wait for the right offer. Unsold homes cost them money as long as they sit empty. So, builders cut prices and add incentives to keep them moving. That trend has carried into August. NAHB’s latest numbers:
-
35% of builders cut prices, with an average reduction of 6%.
-
63% offered incentives like covering closing costs or buying down your mortgage rate.
And those incentives can make a real dent in what you pay upfront and every month after. Plus, since everything is new and many builders offer warranties, you could save on home maintenance costs too. And with affordability where it is, every dollar counts.
So, don’t cross new builds off your list just yet. Yes, you may think they cost more, but that’s not always the case.
If you can get brand-new everything for less than buying an existing home, isn’t that at least worth looking into?
Don’t Let the Builder Pick Your Teammate
But before you tour a single model home, there’s one thing worth figuring out first – who’s actually working for you once you walk through that door.
That friendly rep in the builder’s sales office works for the builder, not you. Their job is to protect the builder’s bottom line, not yours. Your own agent flips that.
They know the local market, so they can tell you if the builder’s price and upgrades stack up against other options nearby. They’ll negotiate on your behalf, whether that’s a lower price, free upgrades, or a rate buydown.
A good agent will also push for a home inspection. Builders won’t always bring it up, but it’s a step you shouldn’t skip, even on a new build. And your agent will be in your corner, so you know what you’re buying and get the best deal possible.
Bottom Line
New homes may actually cost less than an existing home right now. And that’s opening up a window for you to get brand-new for less.
If you want a list of new home communities near you that are currently offering incentives or doing price cuts, reach out to a local agent. When you have your own agent, you’ll have someone in your corner helping you get the best deal possible.
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is.
Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.
Why Dipping into a 401(k) Can Be Tempting
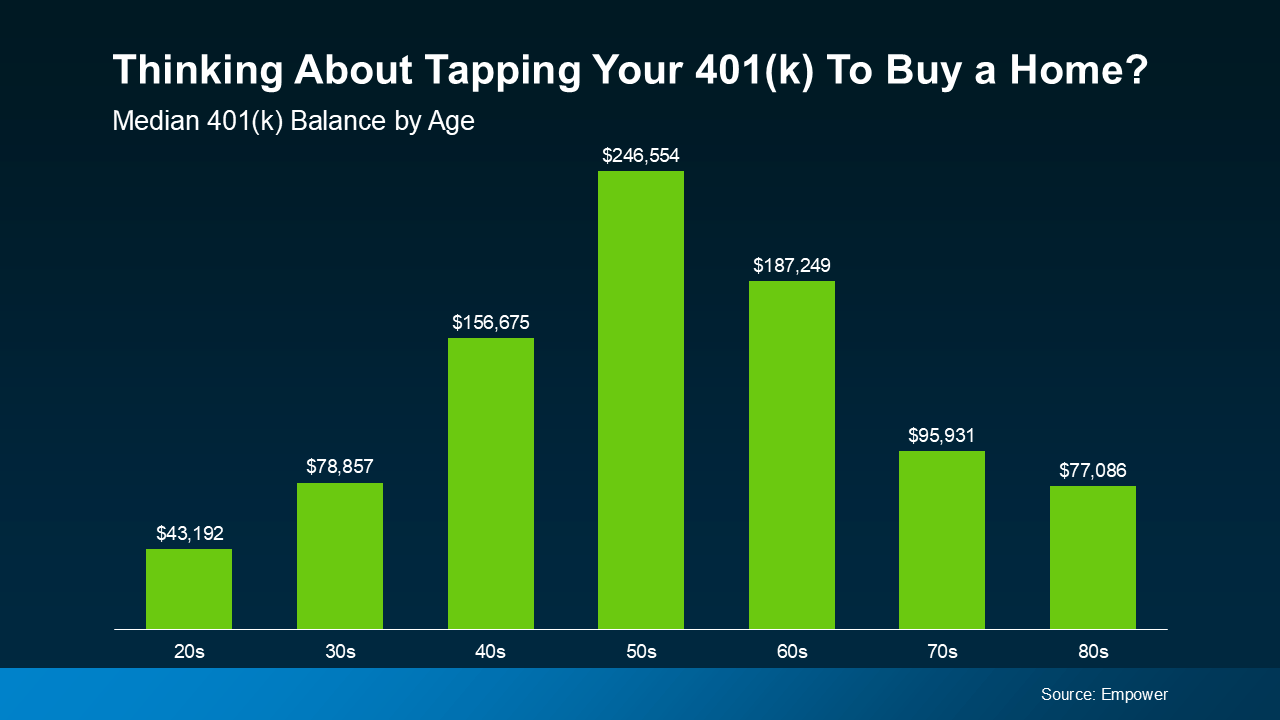
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
 And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:
“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.“
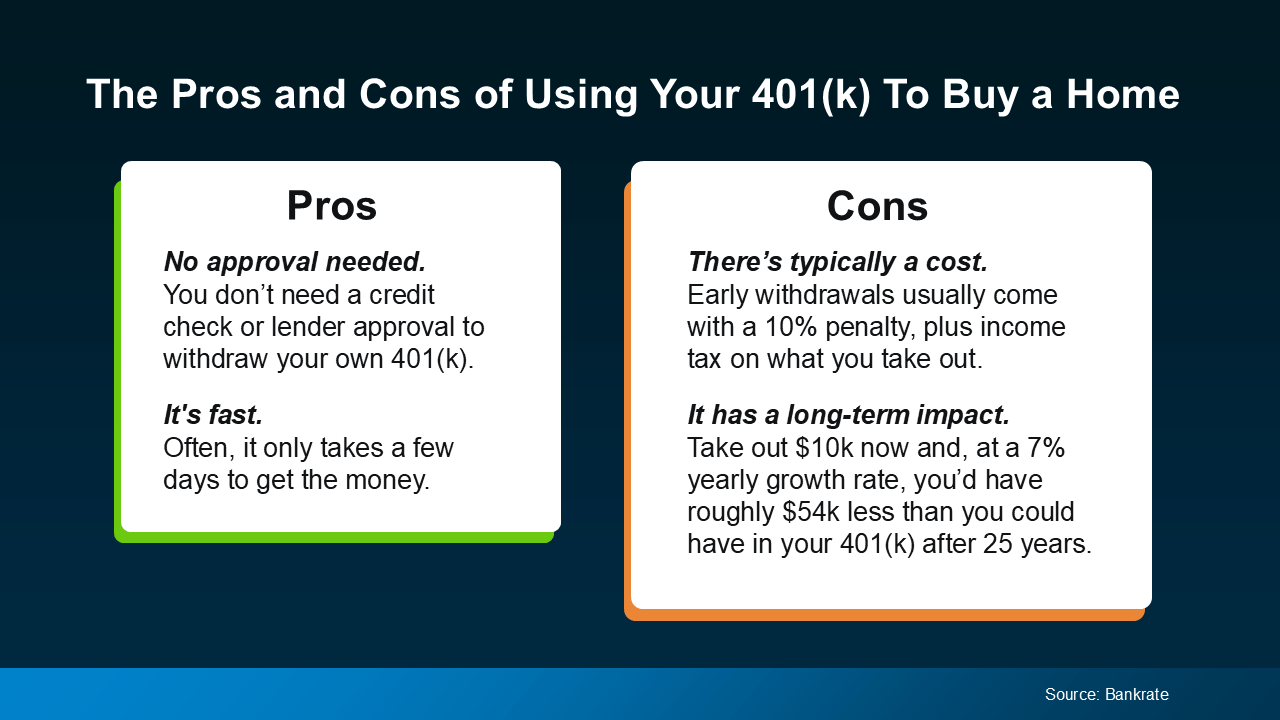
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):
Other Options Worth Exploring First
Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:
-
Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.
-
Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.
Make a Plan Before You Make a Move
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:
“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.“
Bottom Line
Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.
If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget.

Data Centers Are Moving Closer to Homes. What Does That Mean for You?

The Housing Market Split in 2. Which Side Is Your House On?

Remote Work Could Be Your Affordability Answer


-
 Downsize3 weeks ago
One Number Could Change Everything About Your Next Move
-
 Downsize4 weeks ago
The Kind of House Buyers Are Willing To Pay More For
-
 For Buyers3 weeks ago
Higher Rates Could Actually Help Housing Supply – Here’s How.
-
 Agent Value3 weeks ago
Most Home Sales Close – Here’s How To Keep Yours on Track
-

 For Buyers2 weeks ago
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
-
 Affordability2 weeks ago
Sellers Are Cutting Prices To Meet Buyers Where They’re At
-
 Affordability2 weeks ago
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
-
 Affordability1 week ago
Why Buyers Shouldn’t Overlook a Fall Move
You must be logged in to post a comment Login