Equity
How Home Equity May Help You Buy Your Next Home in Cash
Building equity in your house is one of the biggest financial advantages of homeownership. And right now, homeowners across the country are sitting on record amounts of it.
Here’s a look at how that equity could be a game changer for you, and why it’ll flip your perspective from “Why would I move right now?” to “Why wouldn’t I?”
Home Equity: What Is It?
Home equity is the difference between how much your house is worth and how much you still owe on your mortgage. For example, if your house is valued at $400,000 and you only owe $200,000 on your mortgage, your equity would be $200,000.
Why Equity Is Such a Big Deal for Homeowners Looking To Sell
Recent data from the Census and ATTOM shows how significant today’s home equity really is. In fact, more than two out of three homeowners have either completely paid off their mortgages (shown in green in the chart below) or have at least 50% equity in their homes (shown in blue in the chart below):
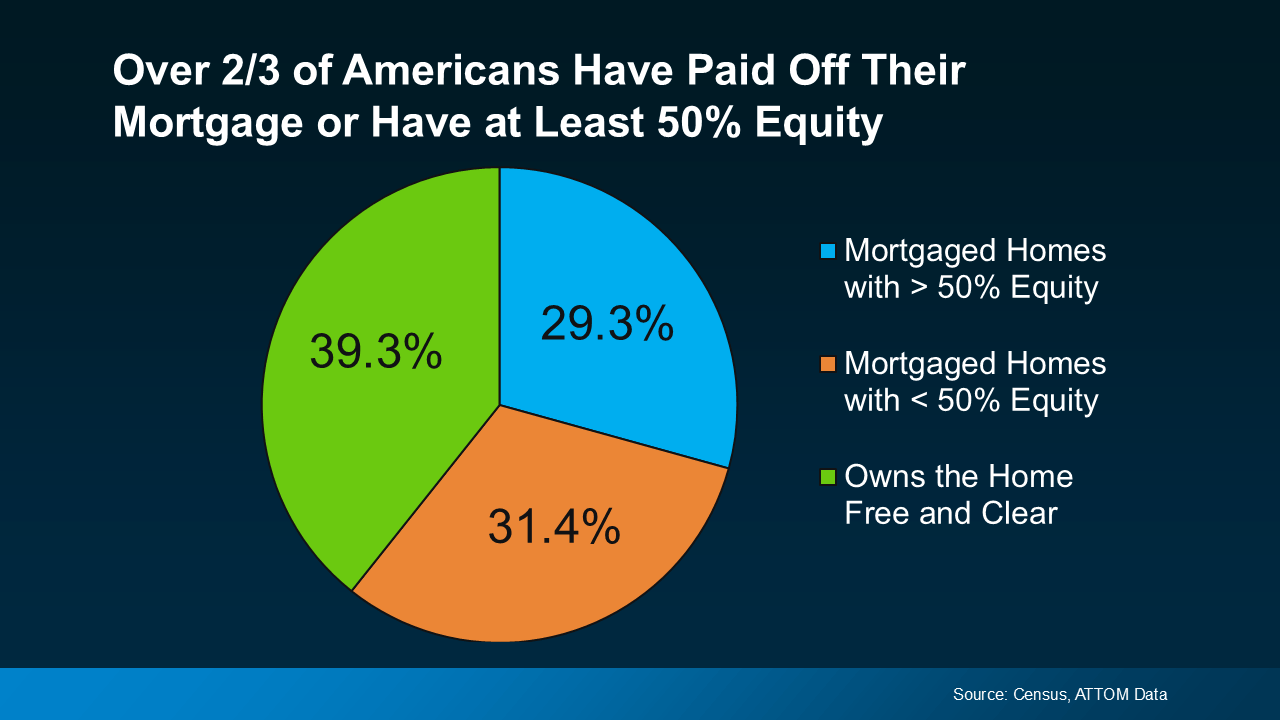 And that’s a big deal. Think about it: 2 out of 3 homeowners have at least 50% equity in their homes. To put a more tangible number on it so you can think about what that really means for someone like you, CoreLogic shows the average homeowner has $311,000 worth of equity built up. That kind of net worth can go a long way if you’re trying to make a move.
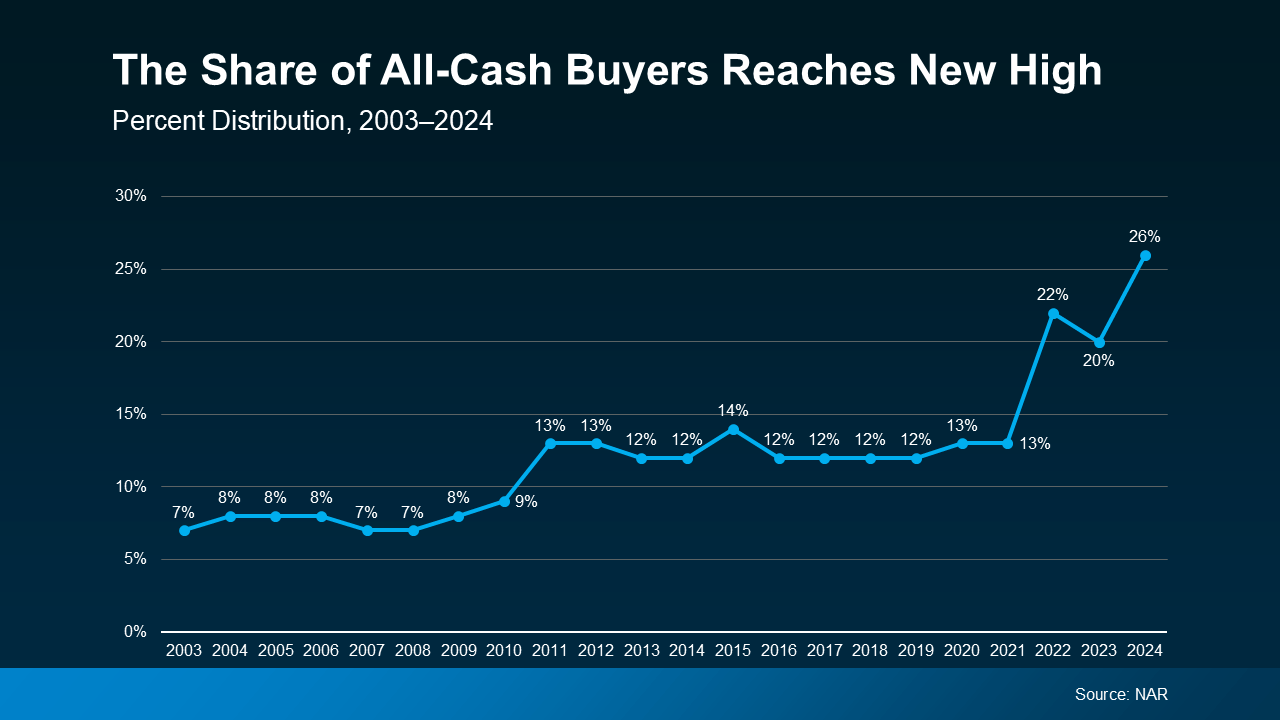
And that’s part of the reason why the share of all-cash buyers recently reached a new high. According to an annual report from the National Association of Realtors (NAR), 26% of buyers were able to buy without a mortgage (see graph below):
 Imagine buying your next house in cash. No mortgage. No monthly payment. No interest rate to mess with. If you want to find out how much equity you have to see if that’s an option for you, connect with a real estate agent and ask for a professional equity assessment report (PEAR).
Who knows, you may find out you have enough equity to buy your next place outright– and with today’s mortgage rates, not having to take out a home loan is pretty incredible. Even if you don’t have enough equity to buy in all cash, you may still have enough to make a larger down payment, which has its own benefits too.
Bottom Line
Homeowners have an incredible amount of equity today – and that’s why the share of all-cash buyers is on the rise. To see how much equity you have and talk through how it can help fuel your next move, connect with an agent.
Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.
A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.
So, what do the forecasts actually say?
Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.
What the Newest Numbers Actually Say
The panel’s latest forecast has prices climbing every single year through at least 2030.
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):
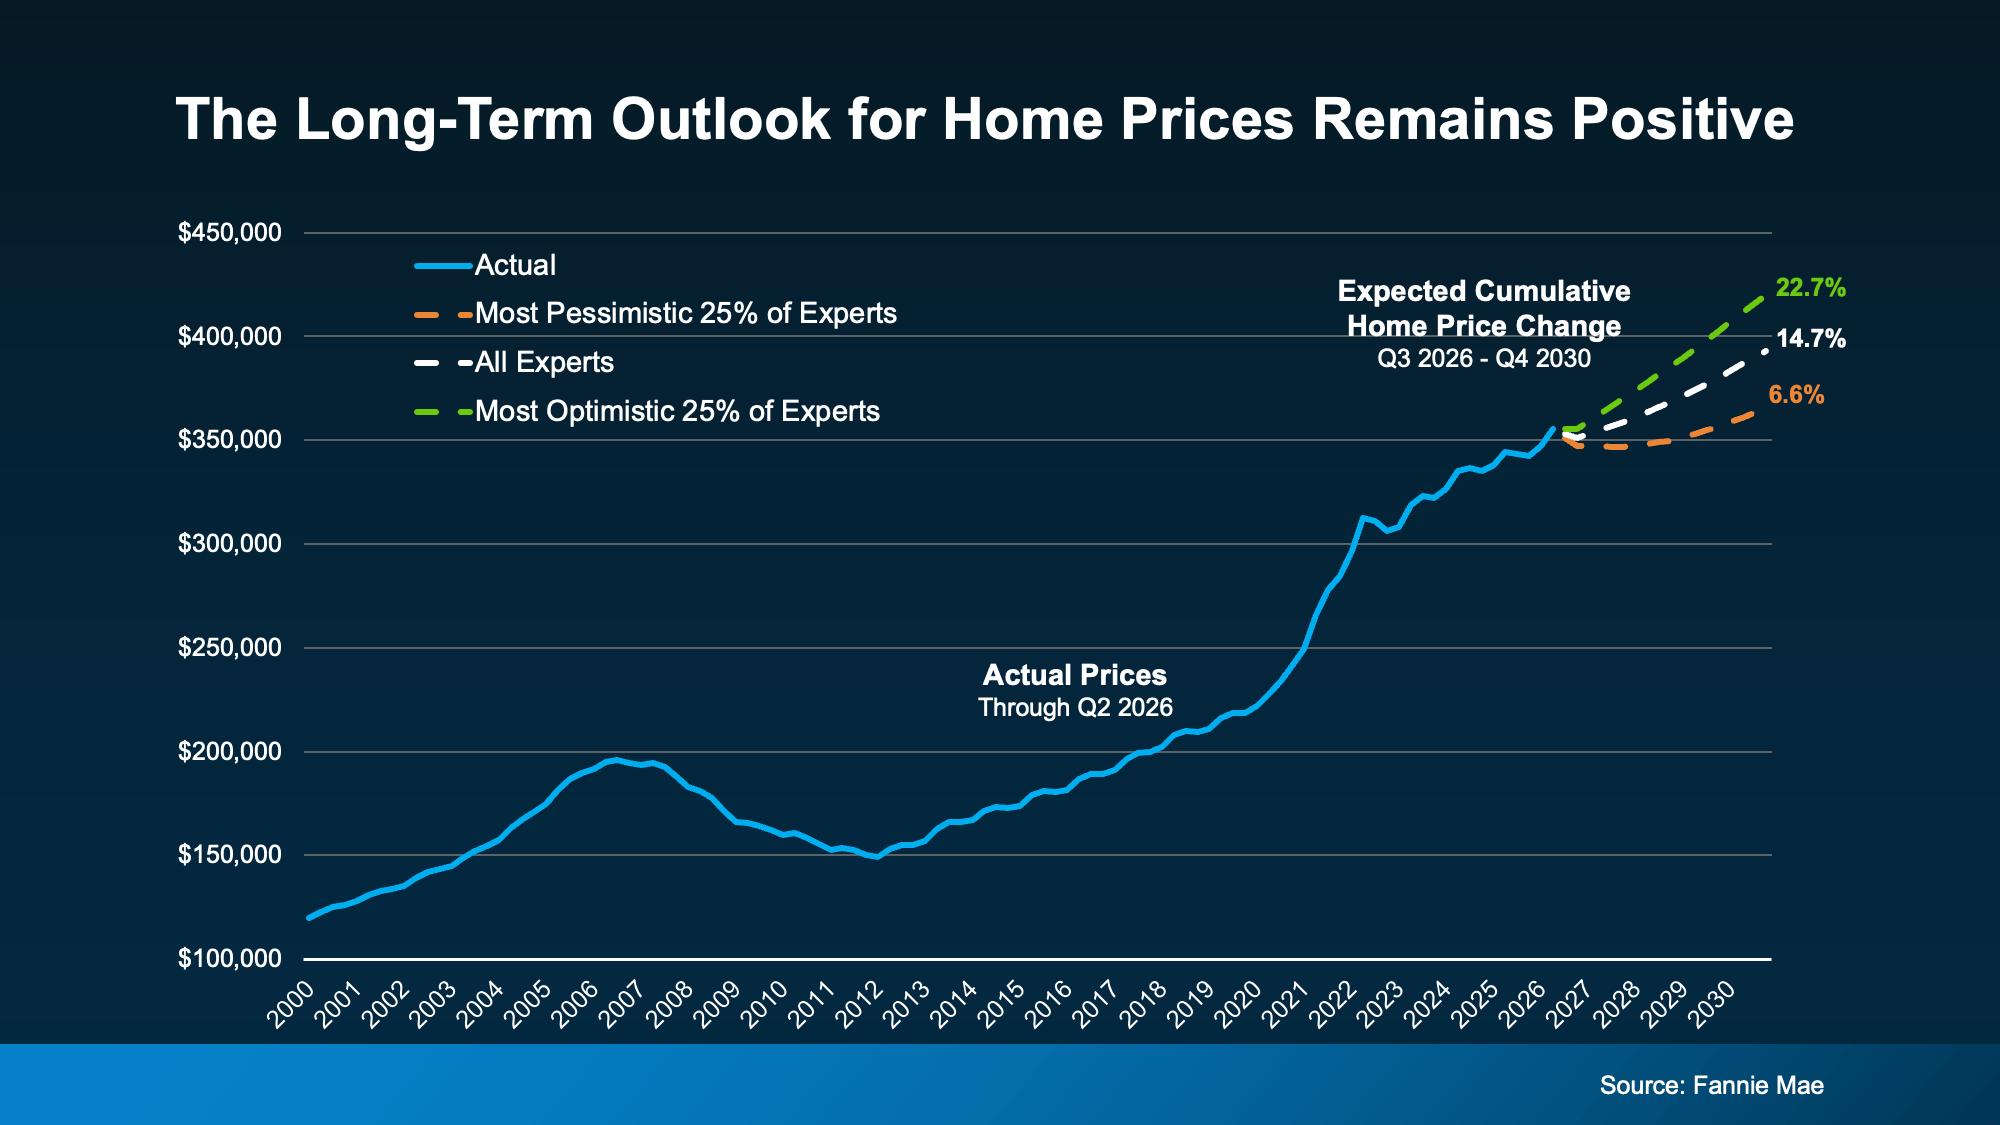
The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.
One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.
How This Quarter Compares to the Past
Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.
A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):
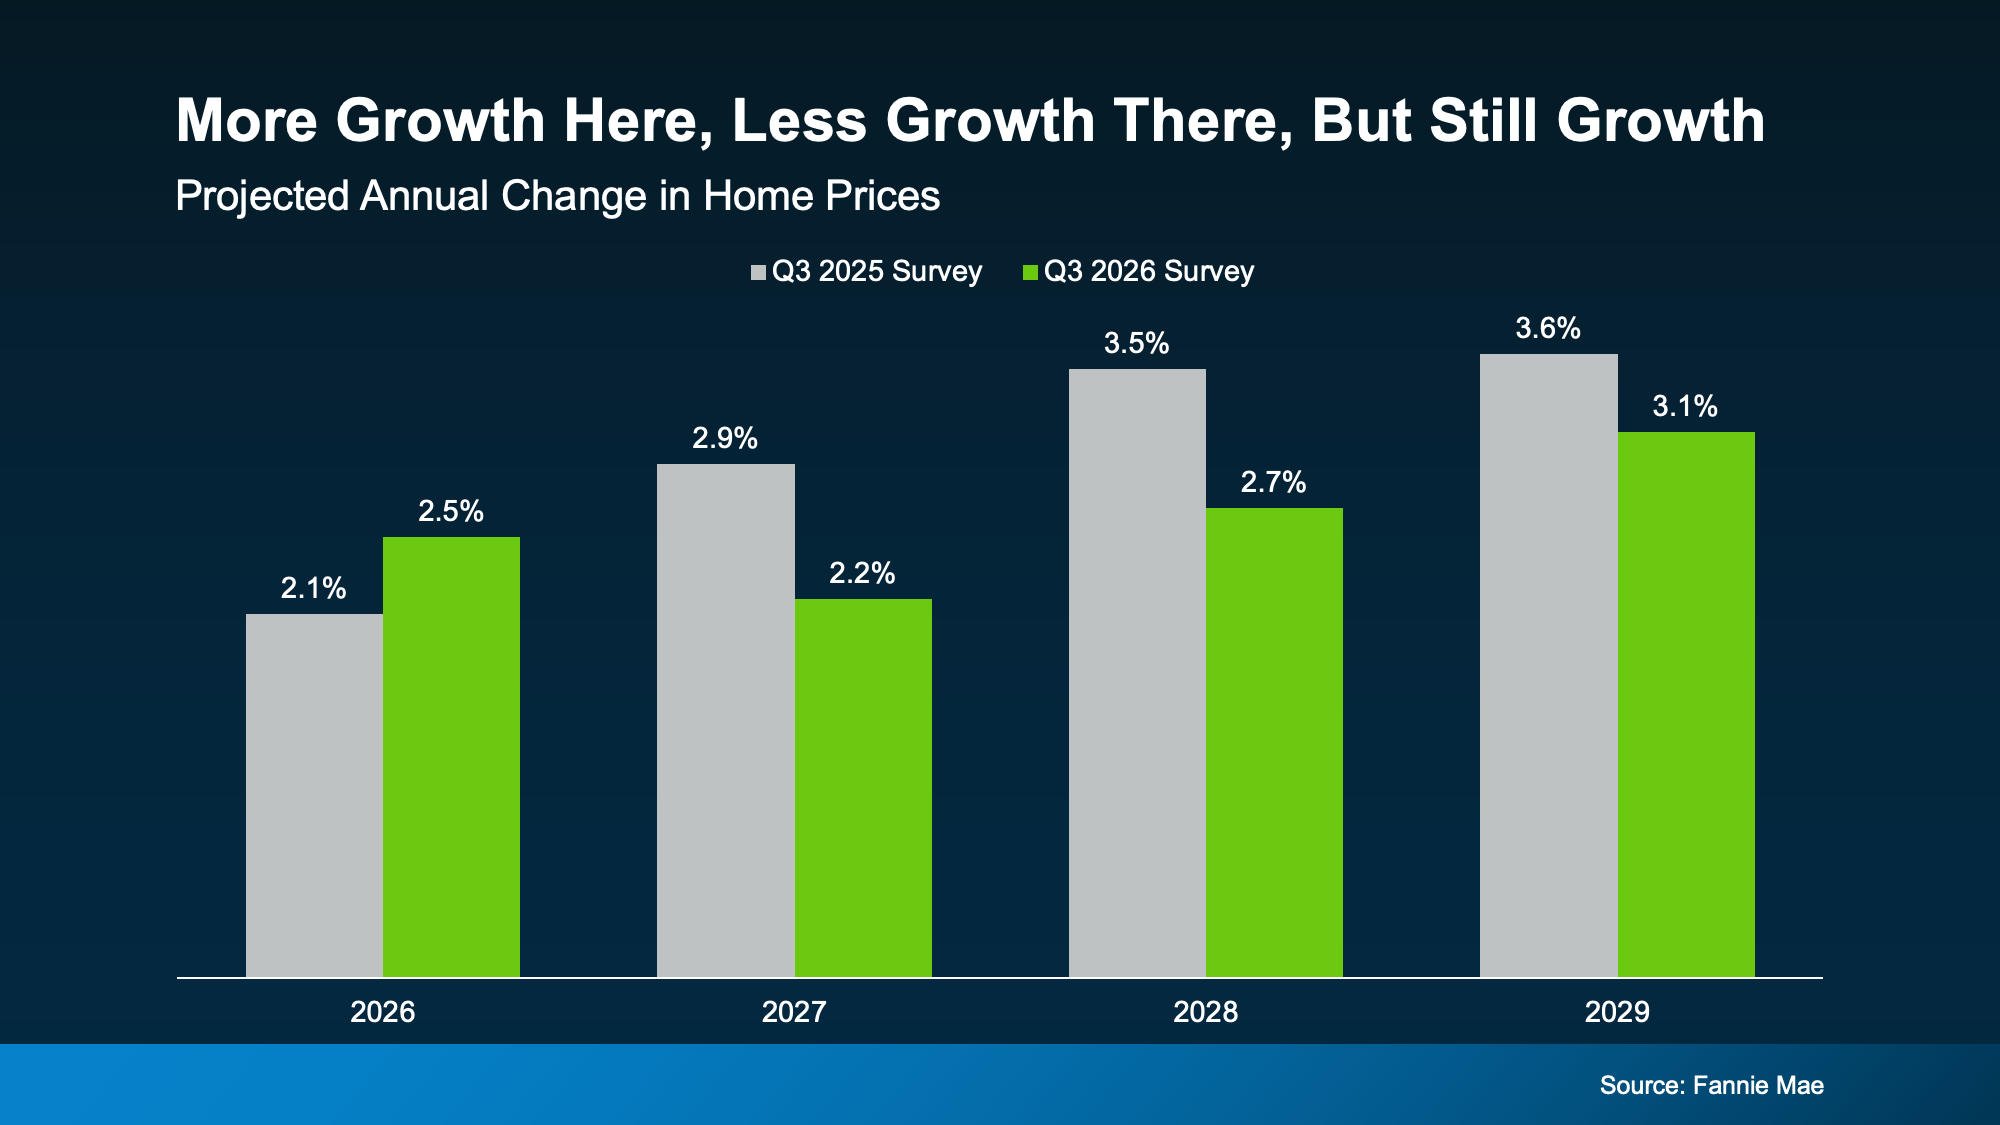
Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.
But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.
A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.
A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.
What It Means for Your Next Move
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.
Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):
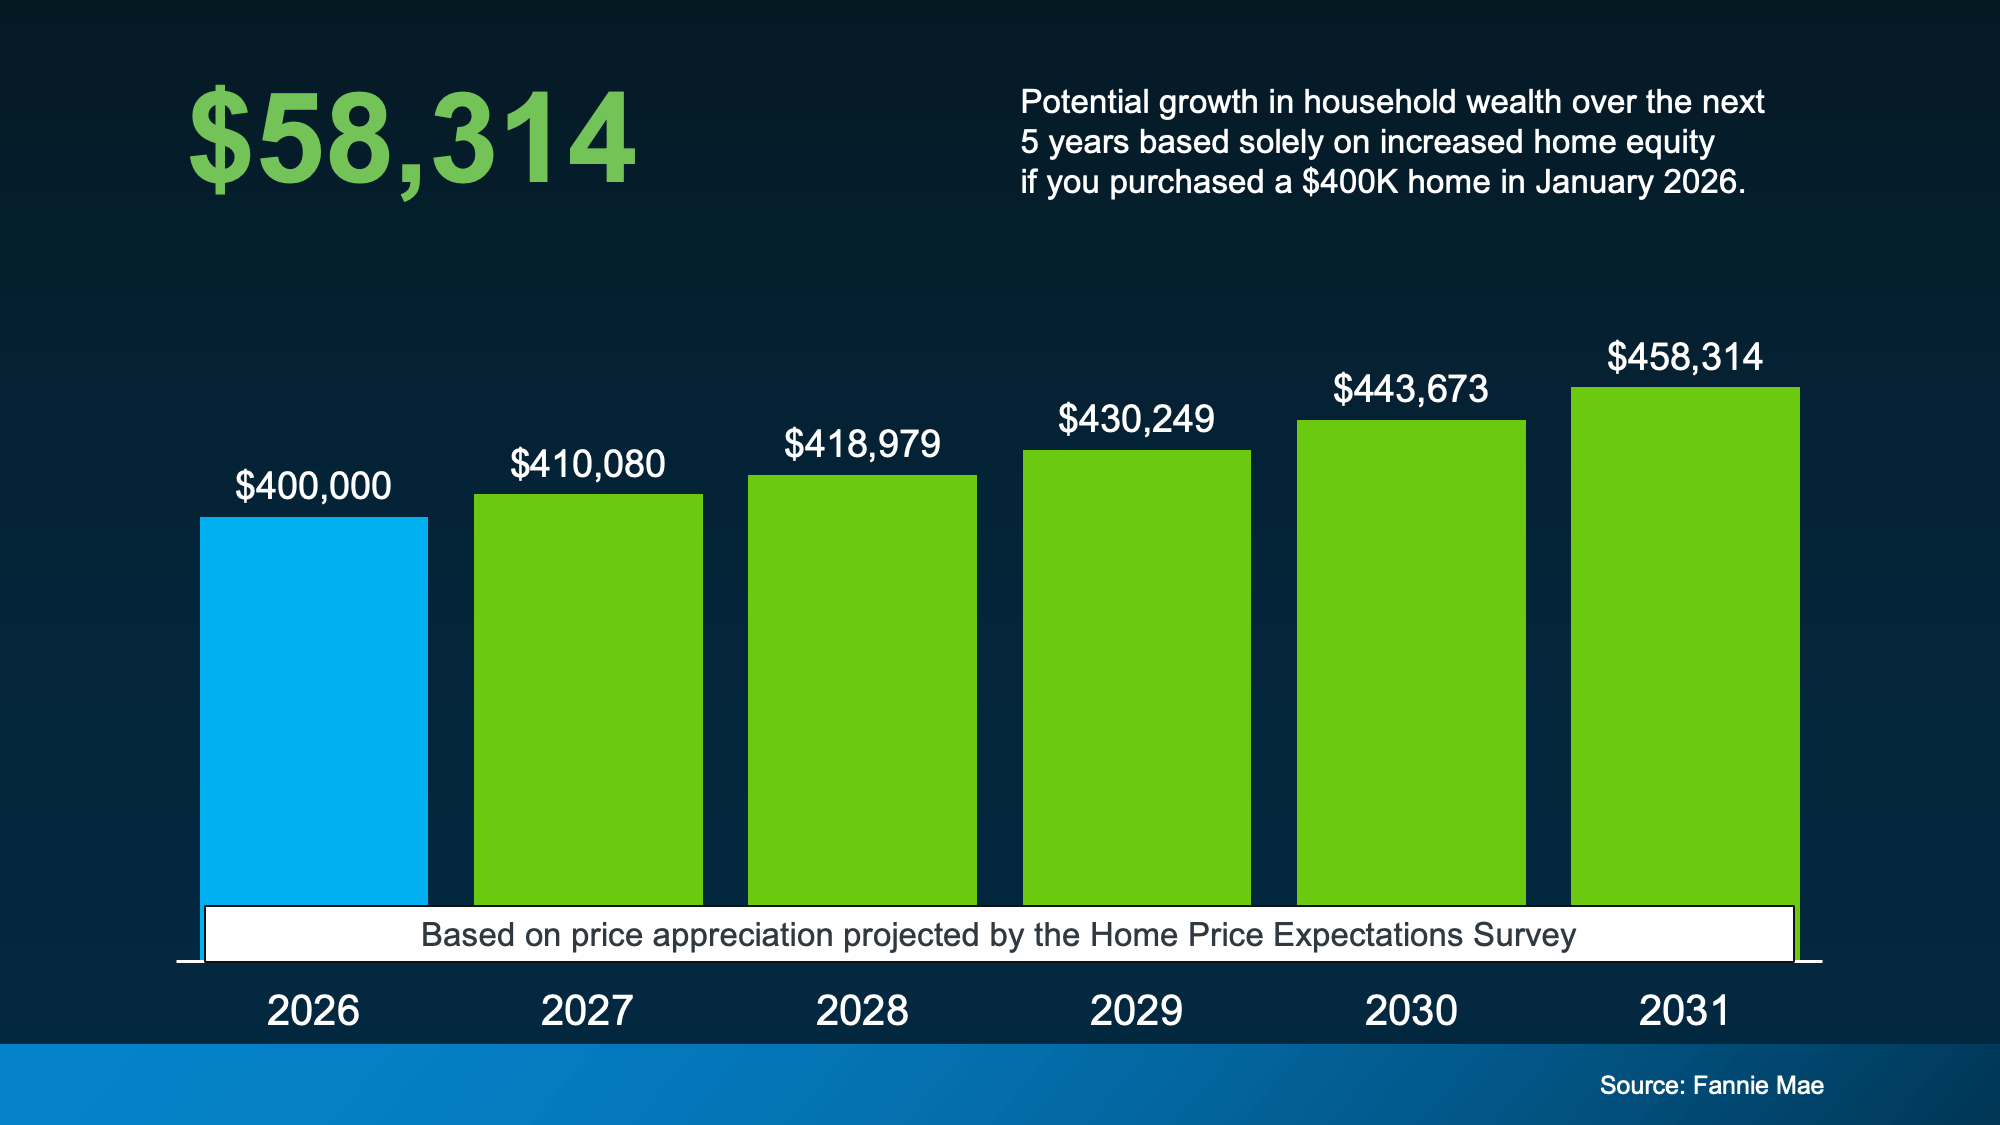
That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.
Bottom Line
Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.
When’s the last time someone told you what your house is worth? Not what some online valuation tool guessed. Not what your neighbor’s house sold for. What yours is actually worth right now.
For a lot of homeowners, it’s been years. And if you’ve been thinking about moving, but higher home prices or mortgage rates have made you hesitate, here’s why it’s time to take a second look at that number.
Your House May Be Worth More Than You Think
Home values have climbed significantly over the past 5-10 years. And even though today’s market is more balanced, homeowners are building wealth every day just by owning their homes. That’s how equity works. As home values rise, and as you make your monthly payments, your equity grows. And it adds up fast.
According to Cotality, the typical homeowner with a mortgage now has $310,500 in equity. That’s not a small number. It’s six figures.
And that’s only the national average. In many states, homeowners have built even more equity than that. Take a look at the map below and see where your state stands. The darker the blue, the more equity the typical homeowner has there (see map below):
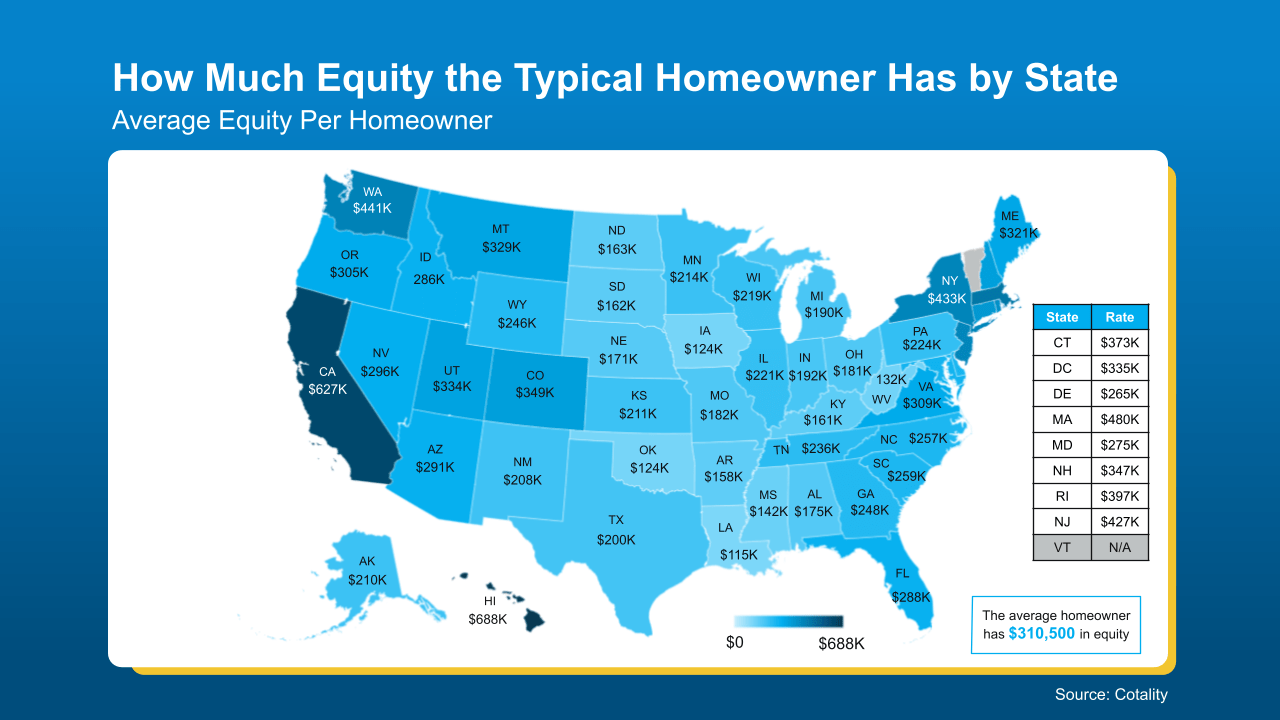 Even though every local market is different, the question you should be asking right now is the same: How much equity have you built up?
Because if you don’t know that number, you’re missing out.
This Could Be the Missing Piece in Your Move
Most people assume that because prices are higher and rates aren’t at 3% anymore, moving just isn’t realistic right now, especially if they already have an ultra-low rate. And that’s understandable – those are real factors.
But they’re not the only factors.
When you have that much equity in your house, you’re not starting from scratch. You’re not scraping together a down payment or hoping the numbers work. You’re walking into your next move with more of an advantage than you think. And that changes the math.
What Your Equity Can Do for You
Maybe you’ve outgrown your current house or you’re ready to downsize… The equity you’ve built could help bridge the gap between where you are today and where you want to be next.
Yes, your next house may cost more than your last one did. But your equity could cover a big chunk of that difference. Depending on how much you’ve built, it could help you:
-
Lower your monthly payment on your next home. The bigger your down payment on your next place, the less you have to borrow. And with today’s rates, borrowing less can make a big difference in what you pay every month.
-
Buy your next house with all cash. This surprises a lot of people, but some homeowners have built enough equity to buy their next home outright, in cash. According to the National Association of Realtors, more than one-quarter (26%) of repeat buyers paid all cash for their home in July.
-
Transform the home you already have. Love your neighborhood but not your floor plan? You don’t have to move. Your equity could help fund renovations that make your home fit your life today while potentially adding value for tomorrow.
Your equity doesn’t erase the challenges of the current market. But it does mean you’re walking into your next move with a lot more power and flexibility than you think.
That’s why the value of your home isn’t something you should have to wonder about.
If you’re even thinking about a move – or if you’re just curious what your options might be – the smartest thing you can do is get a Professional Equity Assessment. It’ll give you a real, market-based evaluation of what your house is really worth right now and how much equity you’re working with.
Because once you see the number, maybe it’s not about whether you can afford to move – it’s about what kind of move makes sense for you.
Bottom Line
If it’s been a while since you’ve gotten a professional look at your home’s value, it’s time to change that.
Reach out to a local real estate agent for a free, personalized Home Equity Assessment that estimates what your house could sell for, how much equity you’ve likely built, and what that could mean for your next move.
You may have six figures of equity without even realizing it. And that’s enough to change everything about your next move.
Remember how exciting it was to buy your first place? It felt like crossing a long-awaited finish line. It gave you a place to build your life. Maybe it’s where you lived when you got married. Or where you welcomed a child or a pet into the family.
But that was just the beginning.
For most people, your first house was never meant to be your forever home. It’s a stepping stone for what comes next.
And if your life looks different today than it did when you got the keys, you’re not stuck. Moving may be more realistic than you think.
Starter Home Inventory Is Still Relatively Low
If you’ve been wondering whether now is the right time to move up, here’s something worth knowing. Starter homes remain one of the hardest types of homes to find. And that’s good news if you’re thinking about selling your first place.
Historically, we haven’t been building enough homes for first-time buyers. And even though homebuilders have shifted more attention toward smaller, entry-level homes lately, the Census shows there’s a long way to go to re-build supply (see graph below):
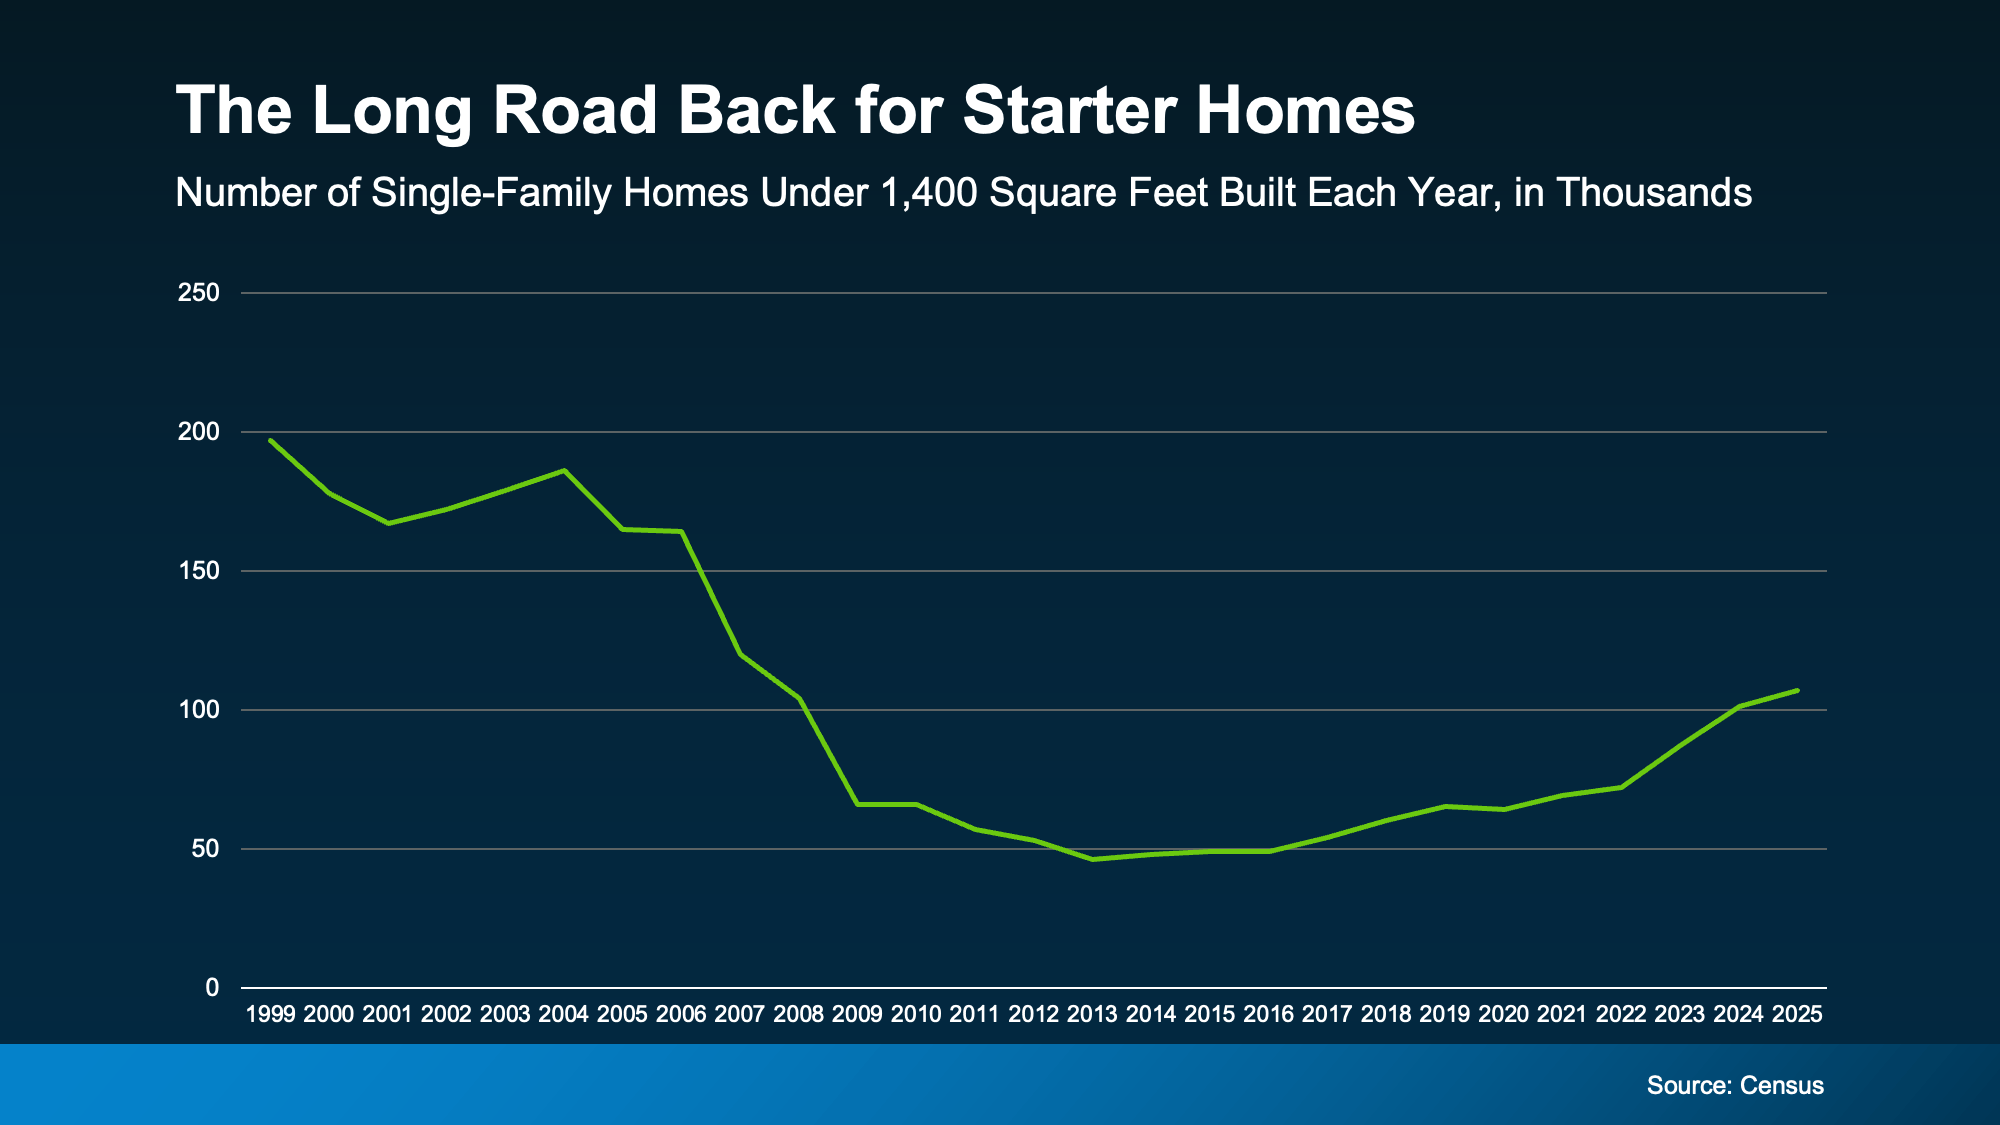
That means your current house is in demand – and that’s a dream scenario for sellers. But that’s only half the story. You also need somewhere to go.
There Are More Move-Up Homes on the Market
Here’s where this gets interesting. While the supply of starter homes remains tight (the green line), data from Redfin shows that the number of homes for sale has been climbing overall (the blue line):
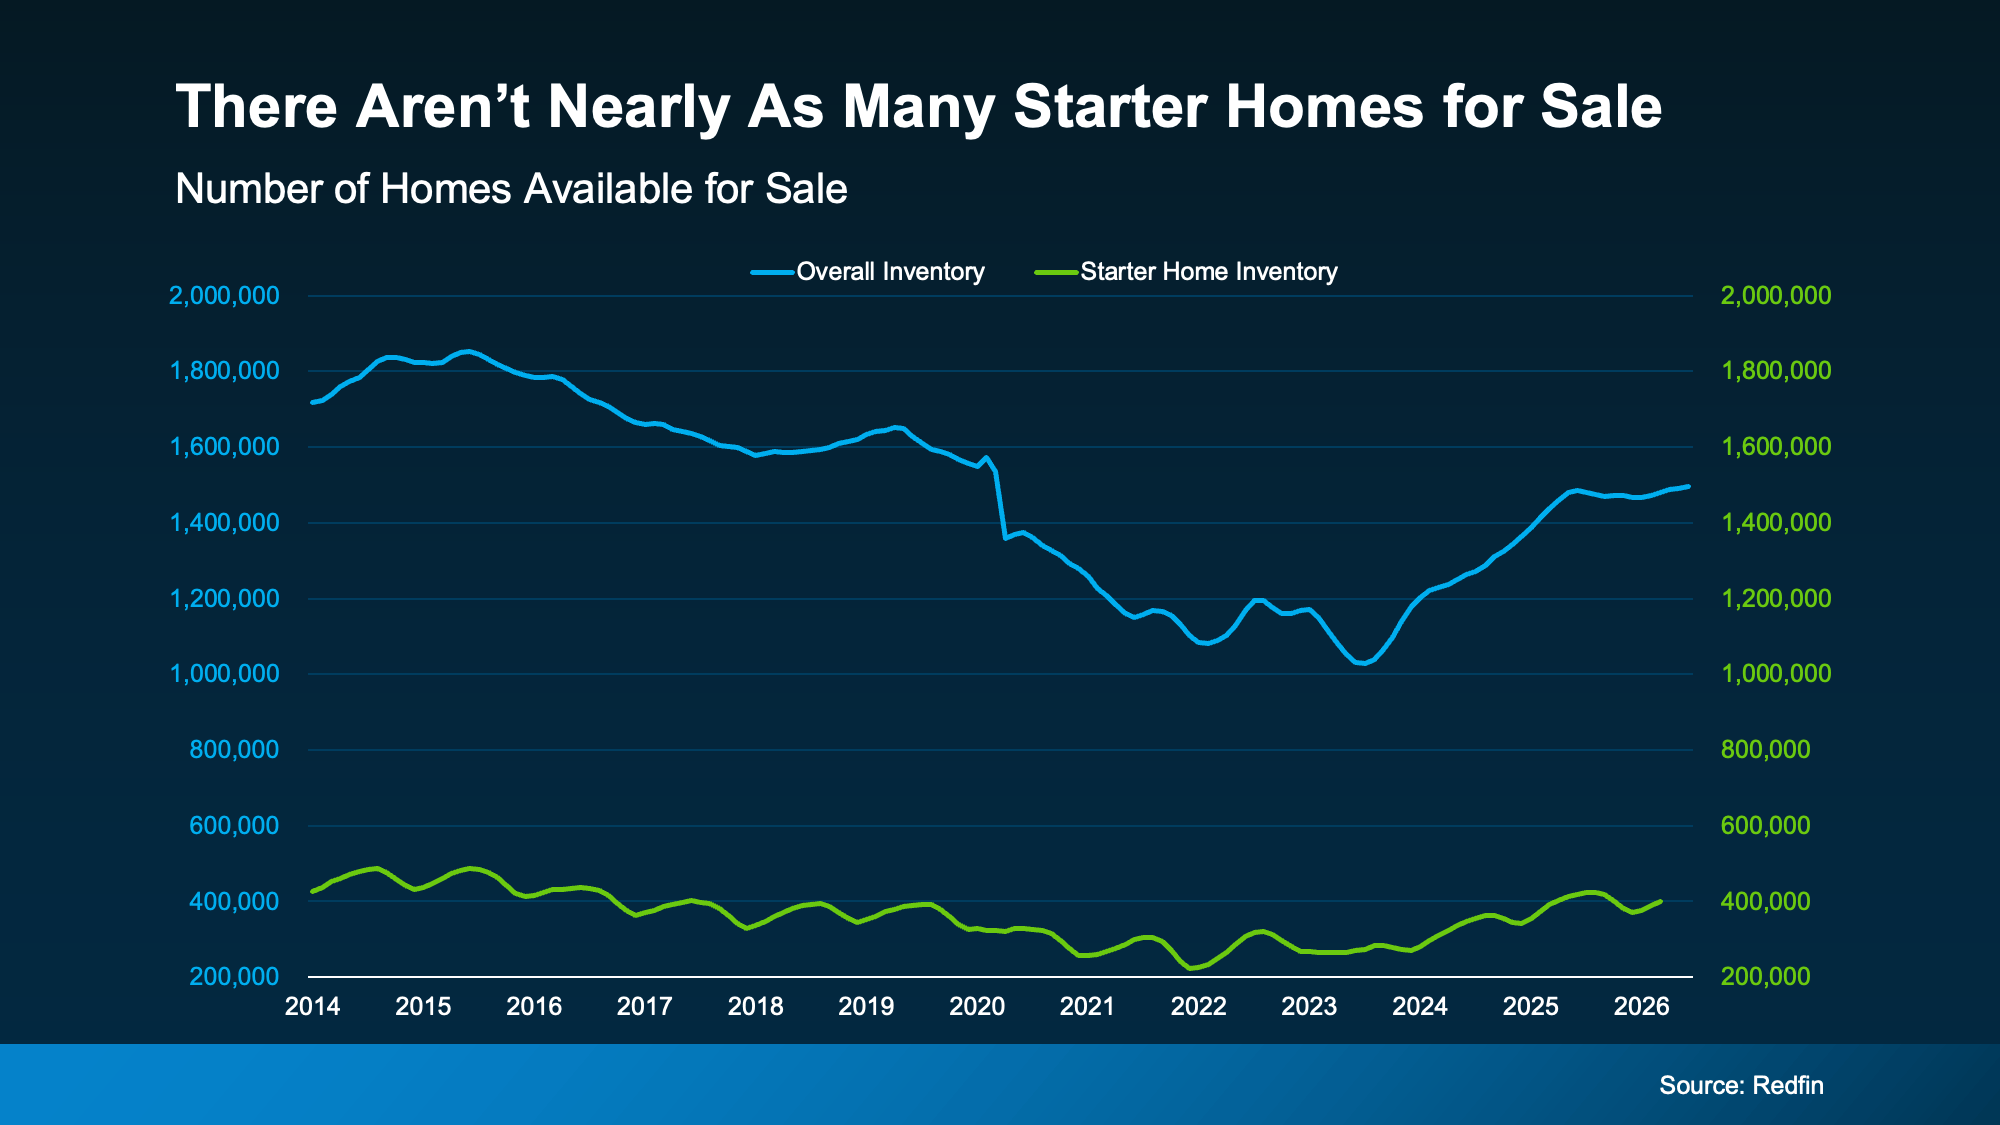
As Nadia Evangelou, Principal Economist and Director of Real Estate Research at the National Association of Realtors (NAR), explains:
“Too much of the inventory available today remains concentrated at higher price points, leaving a shortage of options for entry-level and middle-income buyers.”
That means you may have more choices for your move up than you’d expect. Whether you’re hoping for another bedroom, a home office, a bigger backyard, or simply more room for this next stage of life, today’s market may finally be giving you the chance to find it.
At the same time, your current house may be exactly what someone else has been looking for because homes like yours are still in short supply. That’s a unique advantage for move-up buyers. And it could help you sell for a stronger price. As Zillow says:
“Starter home value appreciation has outpaced other types of homes nationally, mostly because they’re so in demand.”
Your Biggest Advantage May Be Your Equity
Here’s the cherry on top. There’s one more thing your first home has been doing behind the scenes, and that’s building equity. Every mortgage payment you’ve made and every year your home’s value has grown has quietly increased your ownership stake in your house.
According to Cotality, the average homeowner with a mortgage has $295k in equity built up. While your number may be different, once you sell, it could become the down payment on your next home or help reduce the amount you need to borrow at today’s rates.
Put it all together and your move up becomes a lot more realistic than you think:
-
The house you’re selling is in demand.
-
The house you’re buying may be easier to find.
-
And the equity you’ve built can help bridge the gap between the two.
Your first home did exactly what it was supposed to do. It gave you a place to start.
Now, it may be the thing that helps you take the next step.
Bottom Line
Your first home was never meant to be your forever home. It was meant to help you build a life and build the financial foundation for whatever came next.
If your current home no longer fits the life you’re living today, connect with an agent. You may be closer to your next chapter than you realize.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

Why So Many Sellers Are Cutting Their Price Right Now


-
 Affordability4 weeks ago
Why Buyers Shouldn’t Overlook a Fall Move
-
 Affordability4 weeks ago
Think New Homes Cost More? Not Right Now.
-
 Affordability3 weeks ago
Remote Work Could Be Your Affordability Answer
-
 For Buyers3 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
-
 Agent Value3 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
-
 Agent Value2 weeks ago
Selling This Fall? You Haven’t Missed Your Window
-
 For Sellers2 weeks ago
Selling This Fall? You Want To Get These 4 Things Right.
-
 Affordability2 weeks ago
The Best Time To Buy a Home in 2026 Is Almost Here
You must be logged in to post a comment Login