Home Prices
National Housing Trends To Watch
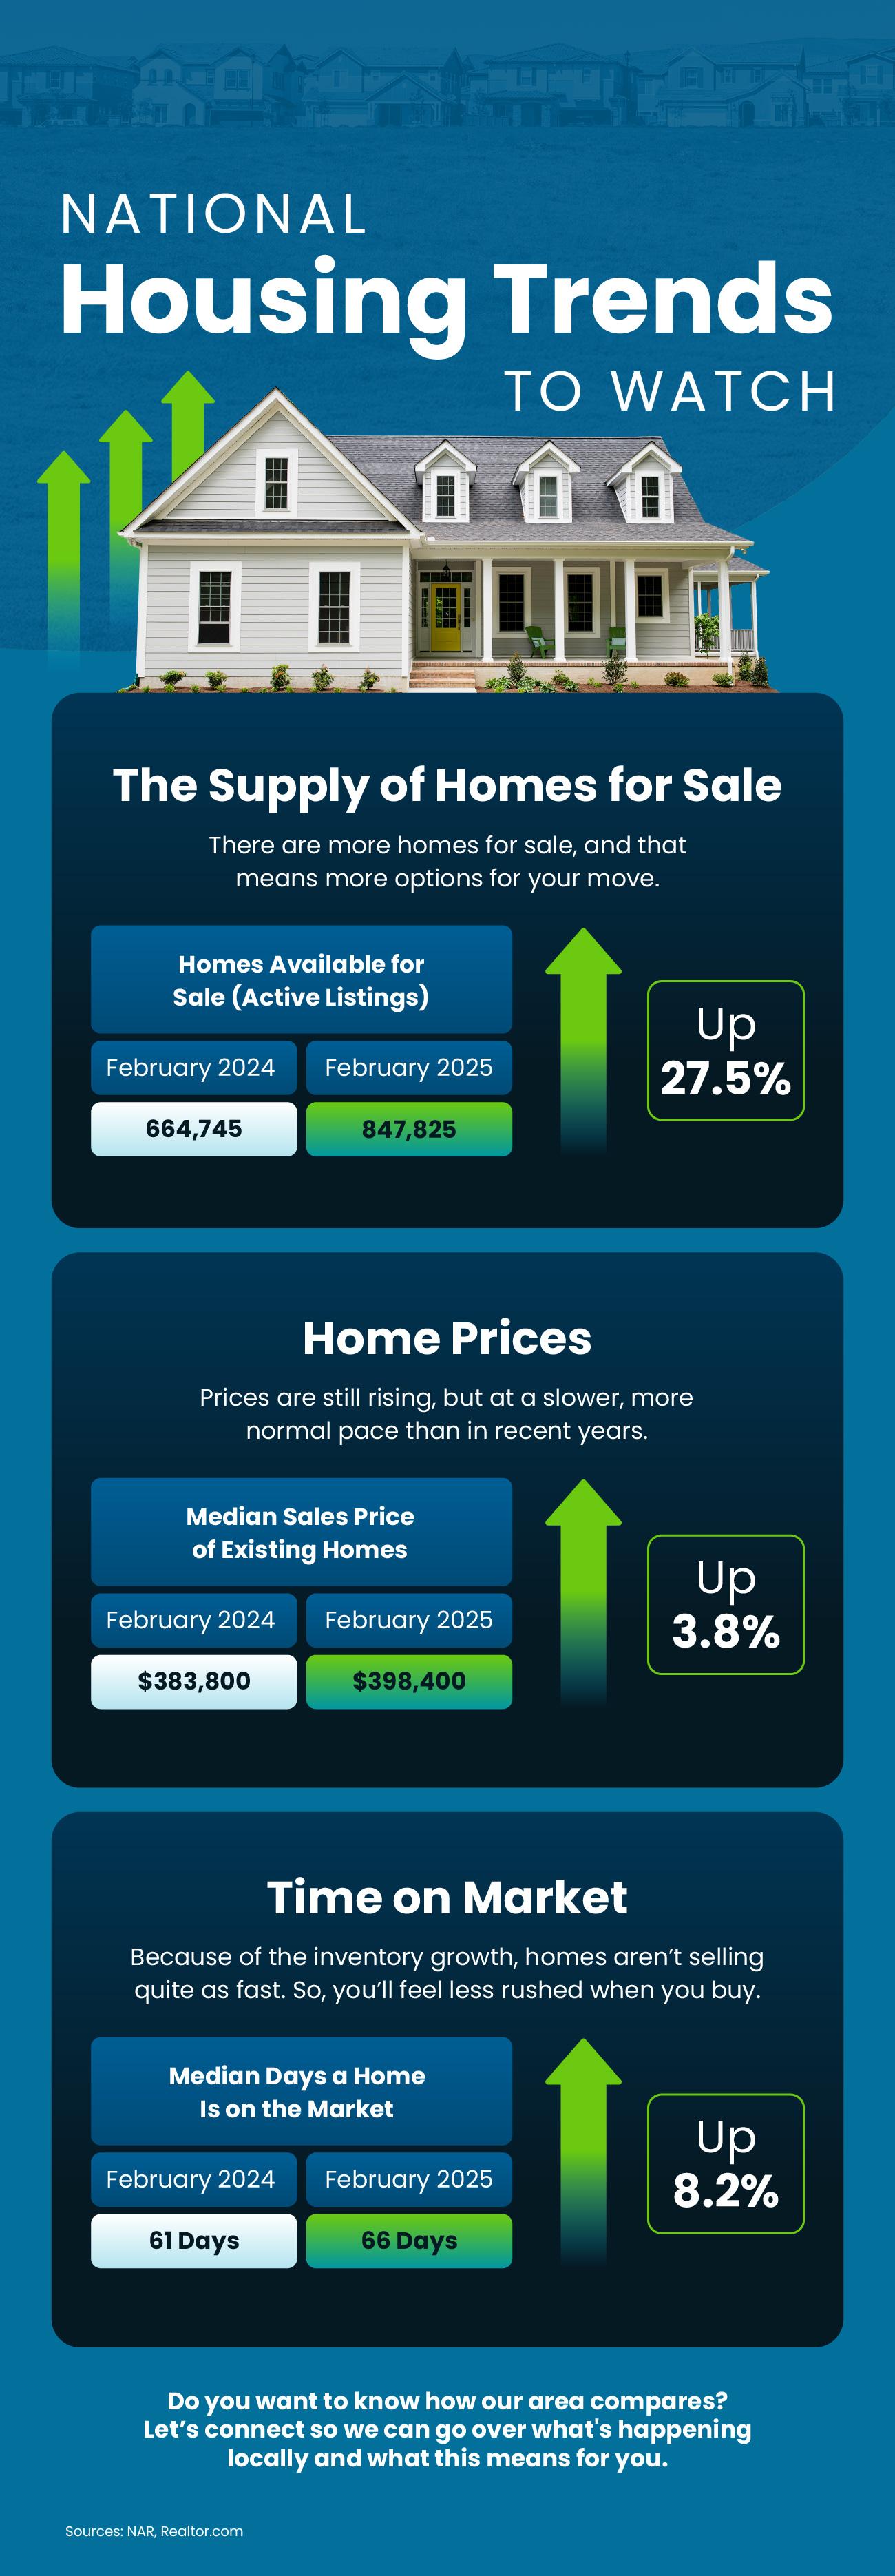
Some Highlights
- At a national level, the housing market has shifted over the past year.
- There are more homes for sale, price growth has moderated, and homes are taking a little longer to sell.
- Do you want to know how your area compares? Connect with a real estate agent to go over what’s happening locally and what this means for you.
Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.
One says home prices are falling. The next says they’re still climbing.
So, which one’s right? It comes down to where you live.
What’s Really Going on with Asking Prices
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):
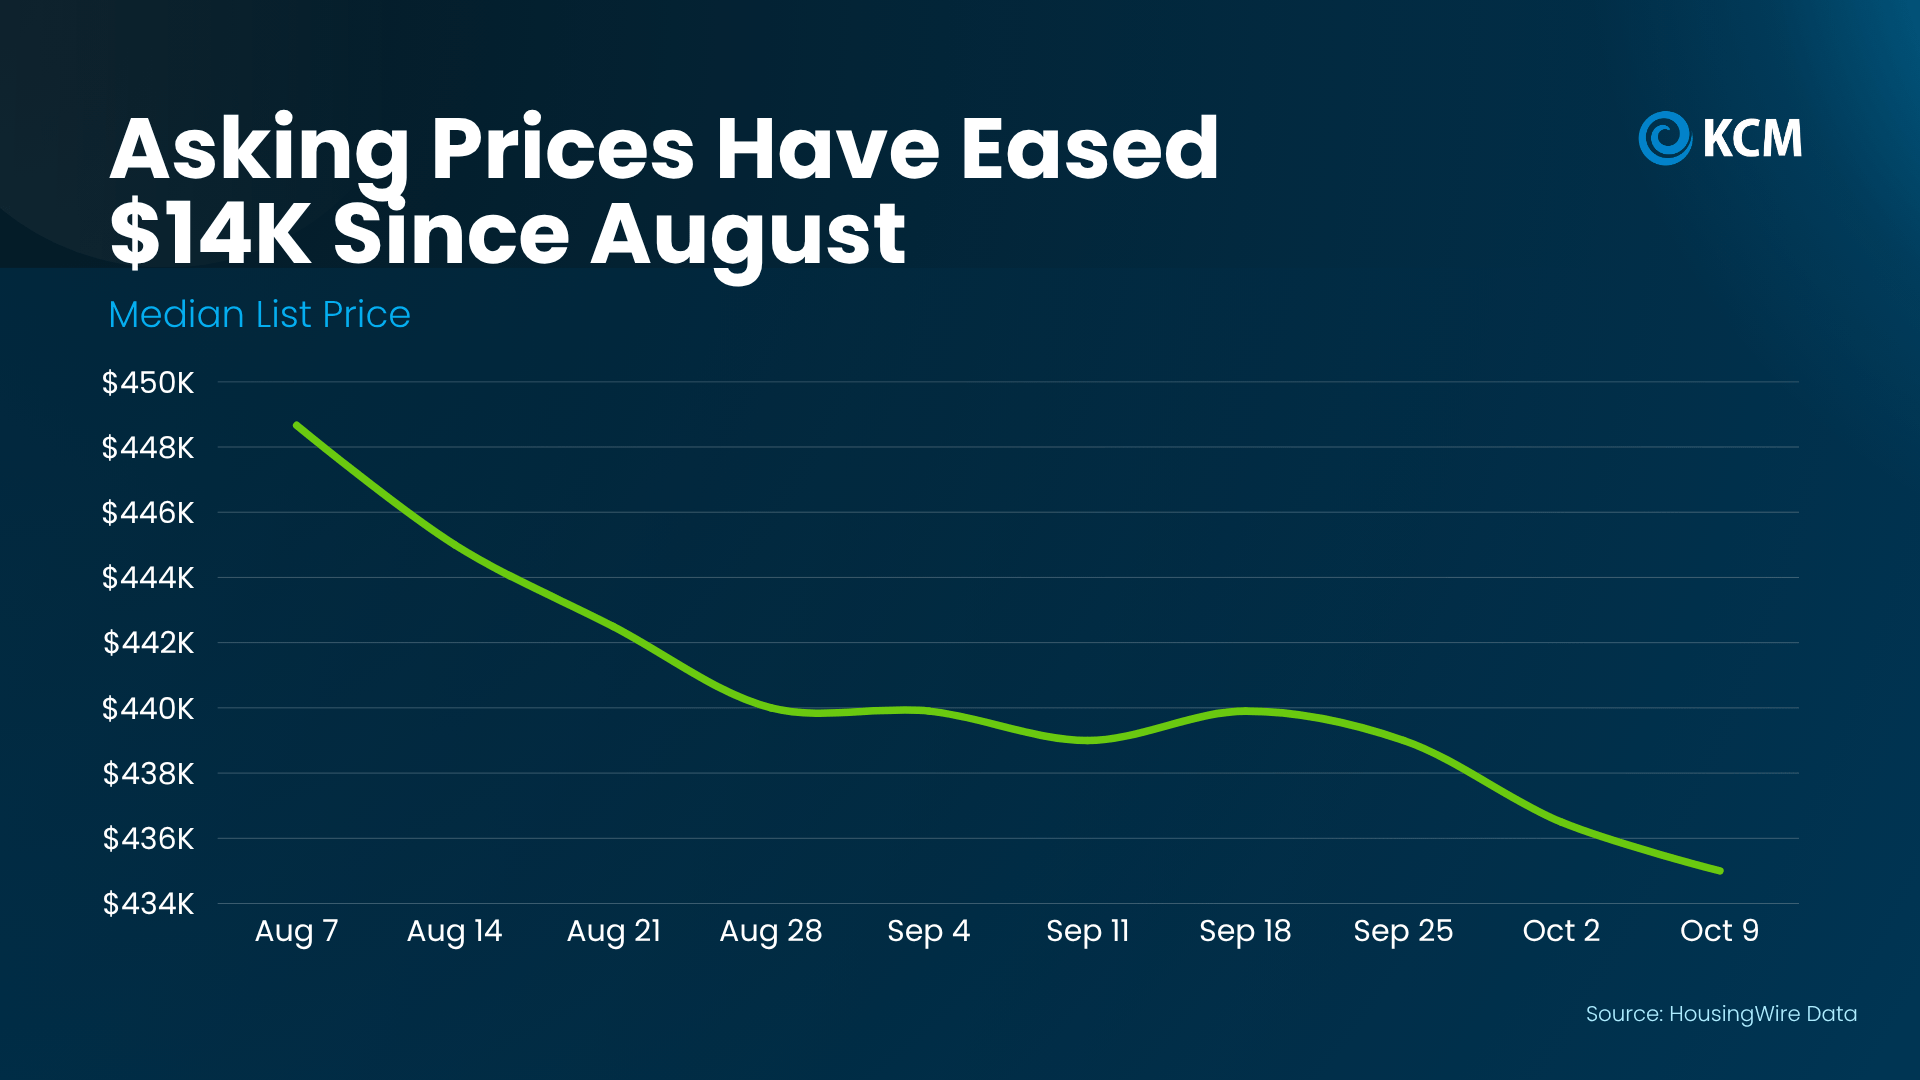
That’s a dip of about 3%, and a lot of it is normal for this time of year.
Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.
Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.
Where You Live Changes Everything
Realtor.com explains:
“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):
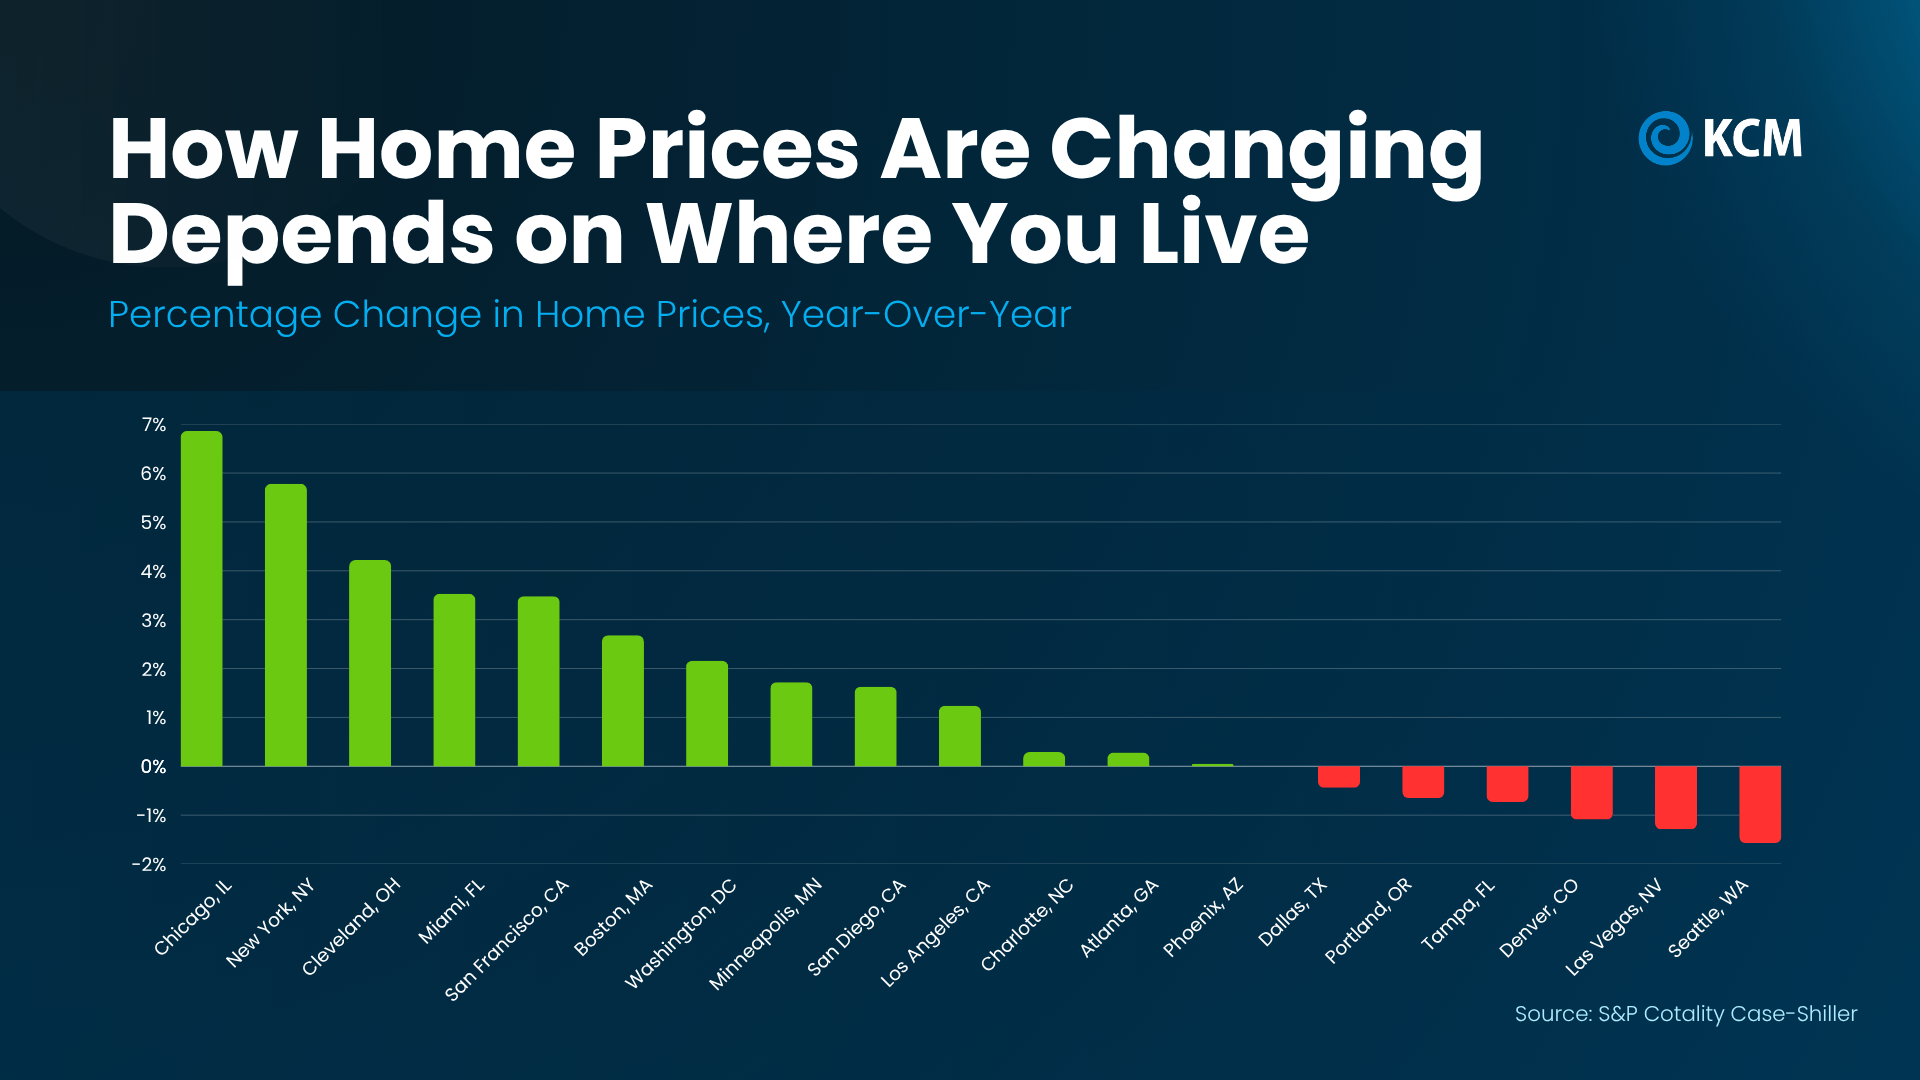
That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.
Why You Don’t Need To Worry About a Crash
Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.
And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):
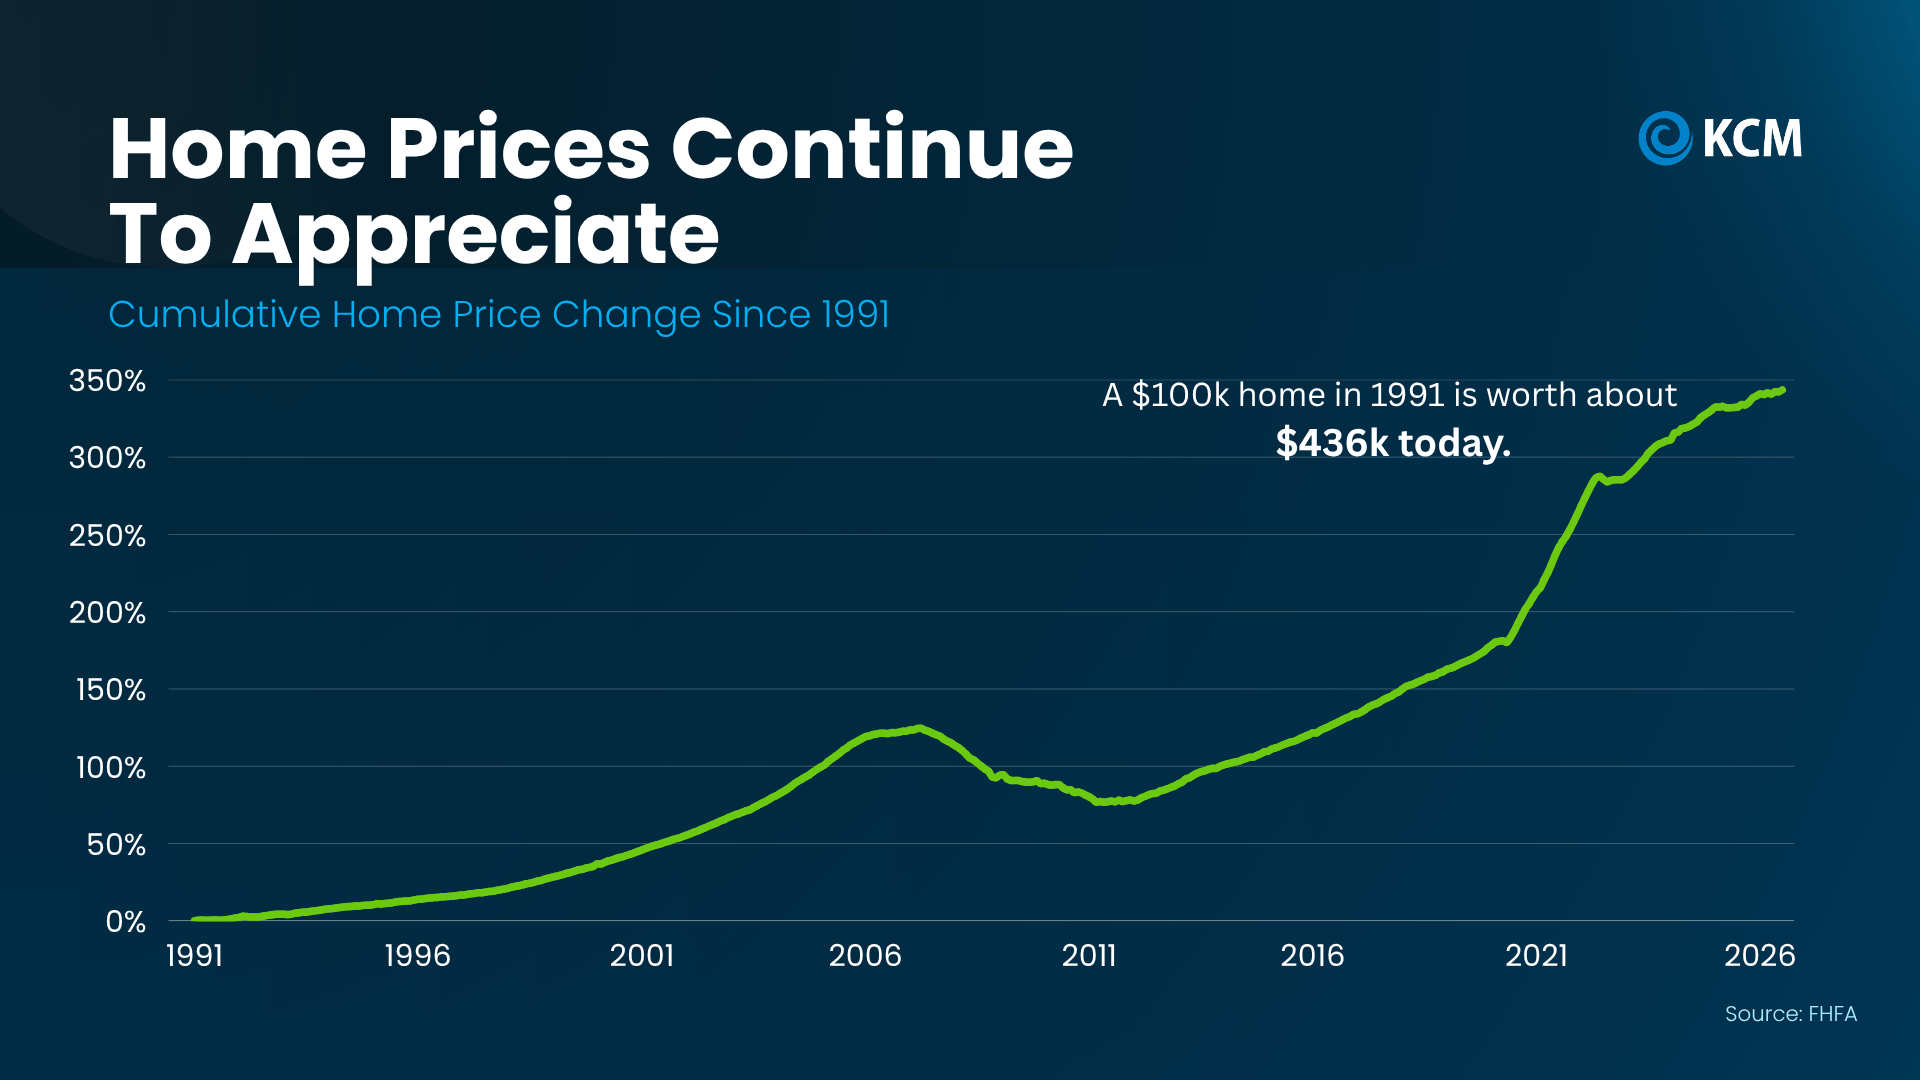
So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.
Bottom Line
National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.
With everything going on, it’s understandable if you’re wondering if you’d regret buying right now.
Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…
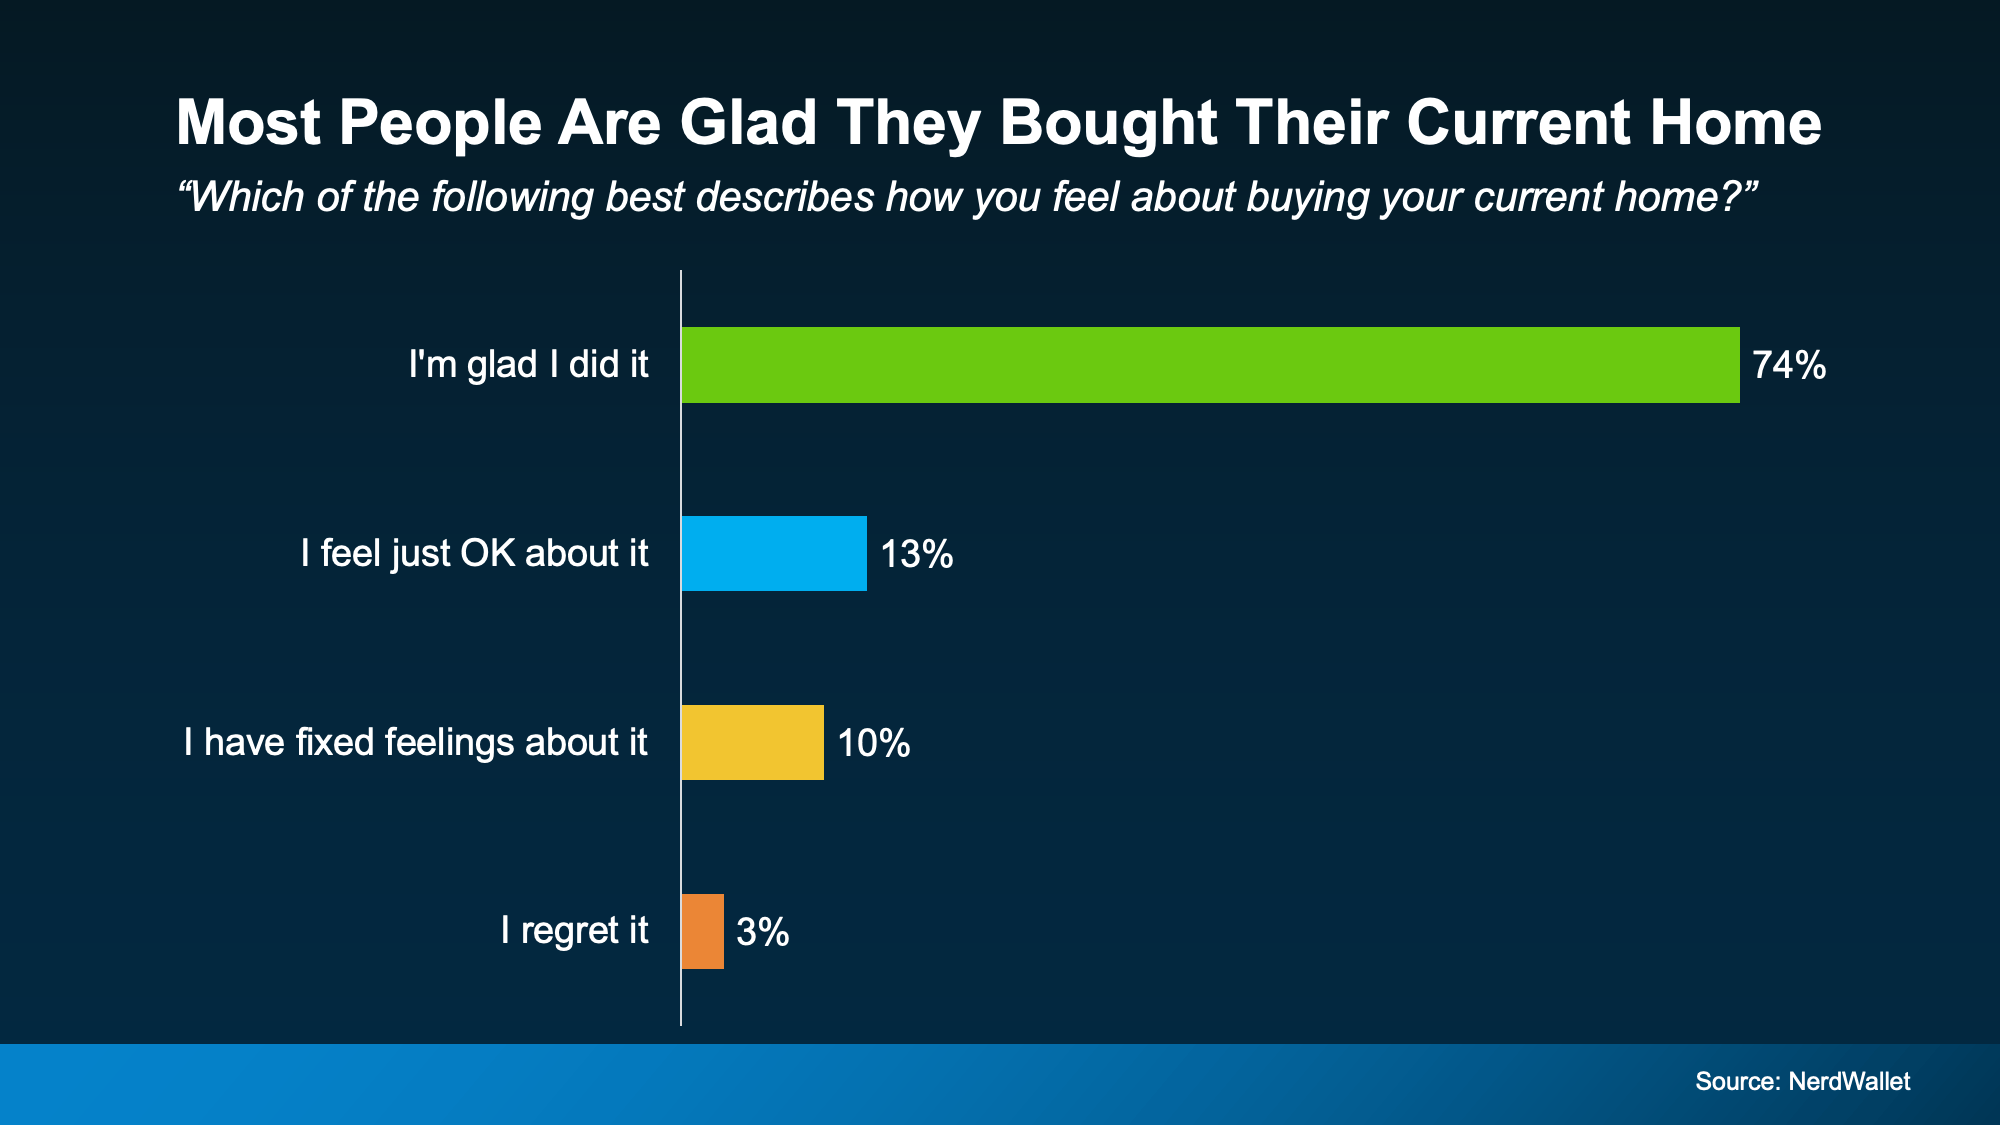
Most people who already made that leap would do it again.
According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:
And here’s a big reason why so many people feel it was worth it, even now.
Homeownership Is a Long-Term Play
When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.
A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):
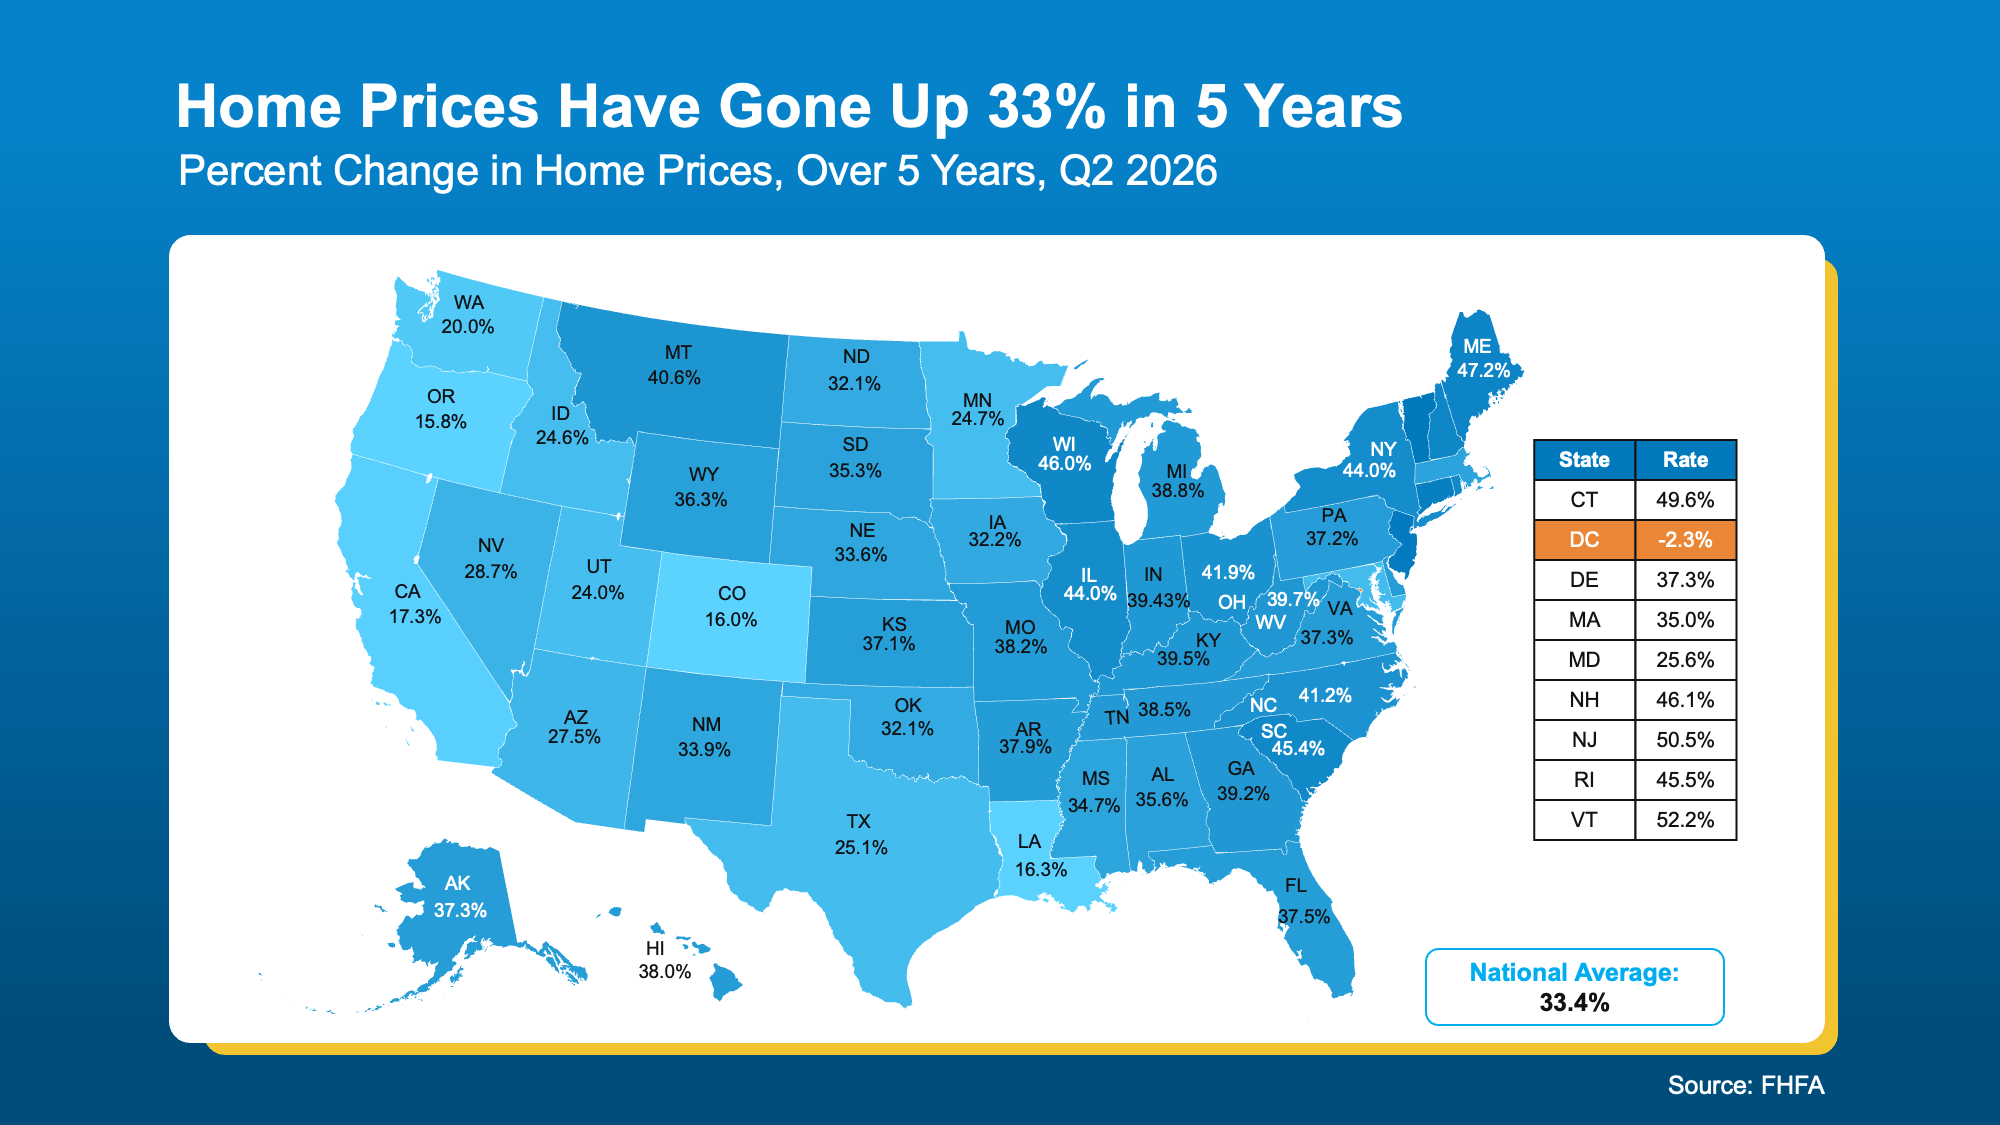
And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.
That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.
Now, Zoom Out Even Further
The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):
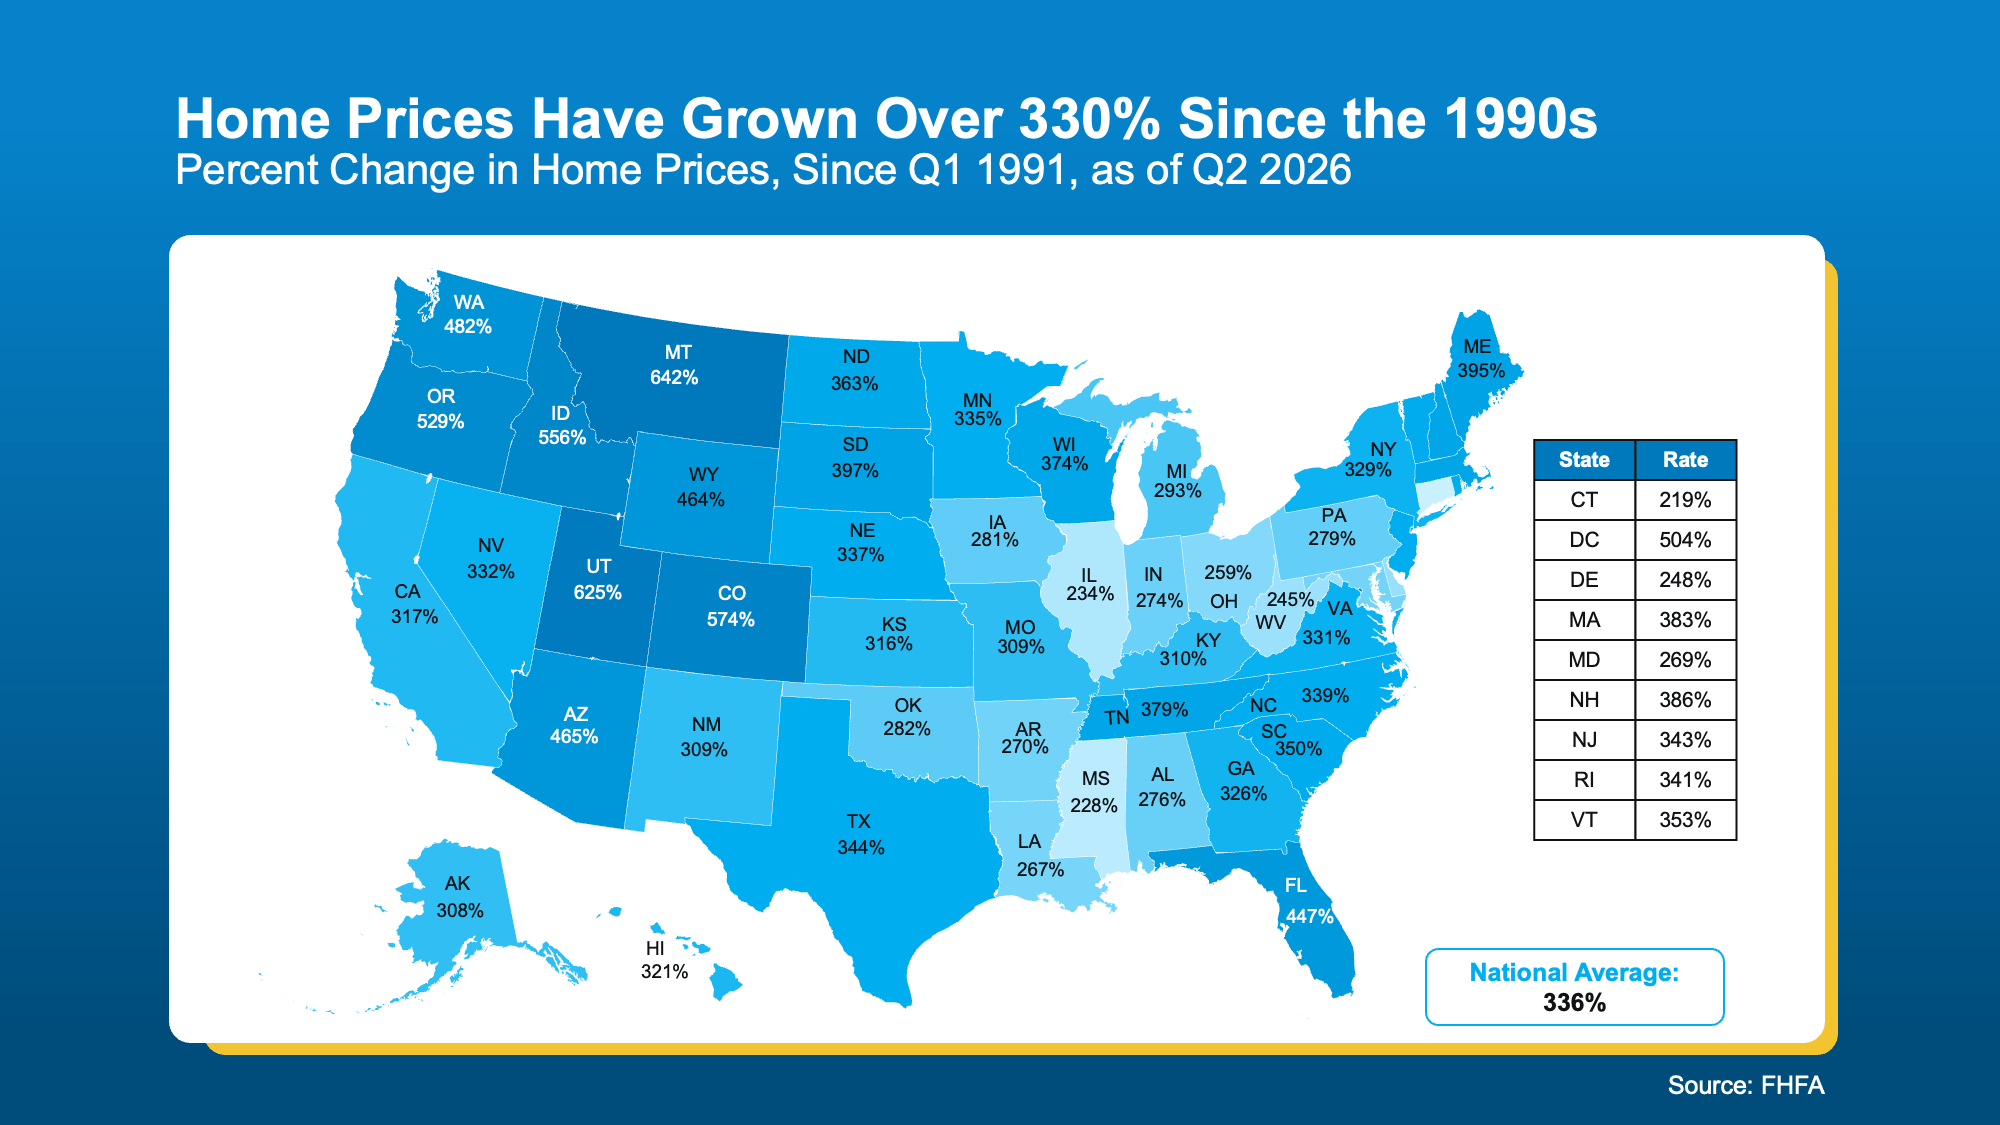
That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.
What it does show is why trying to perfectly time the market can make you miss the bigger picture.
Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains:
“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .
If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”
Basically, if you can afford to do it, buying a home now could set you up for future moves.
And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.
Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.
Bottom Line
Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.
If you’re wondering whether buying makes sense for you right now, connect with an agent to look at the numbers together – and what owning a home could mean for you in the years ahead.
Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.
A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.
So, what do the forecasts actually say?
Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.
What the Newest Numbers Actually Say
The panel’s latest forecast has prices climbing every single year through at least 2030.
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):
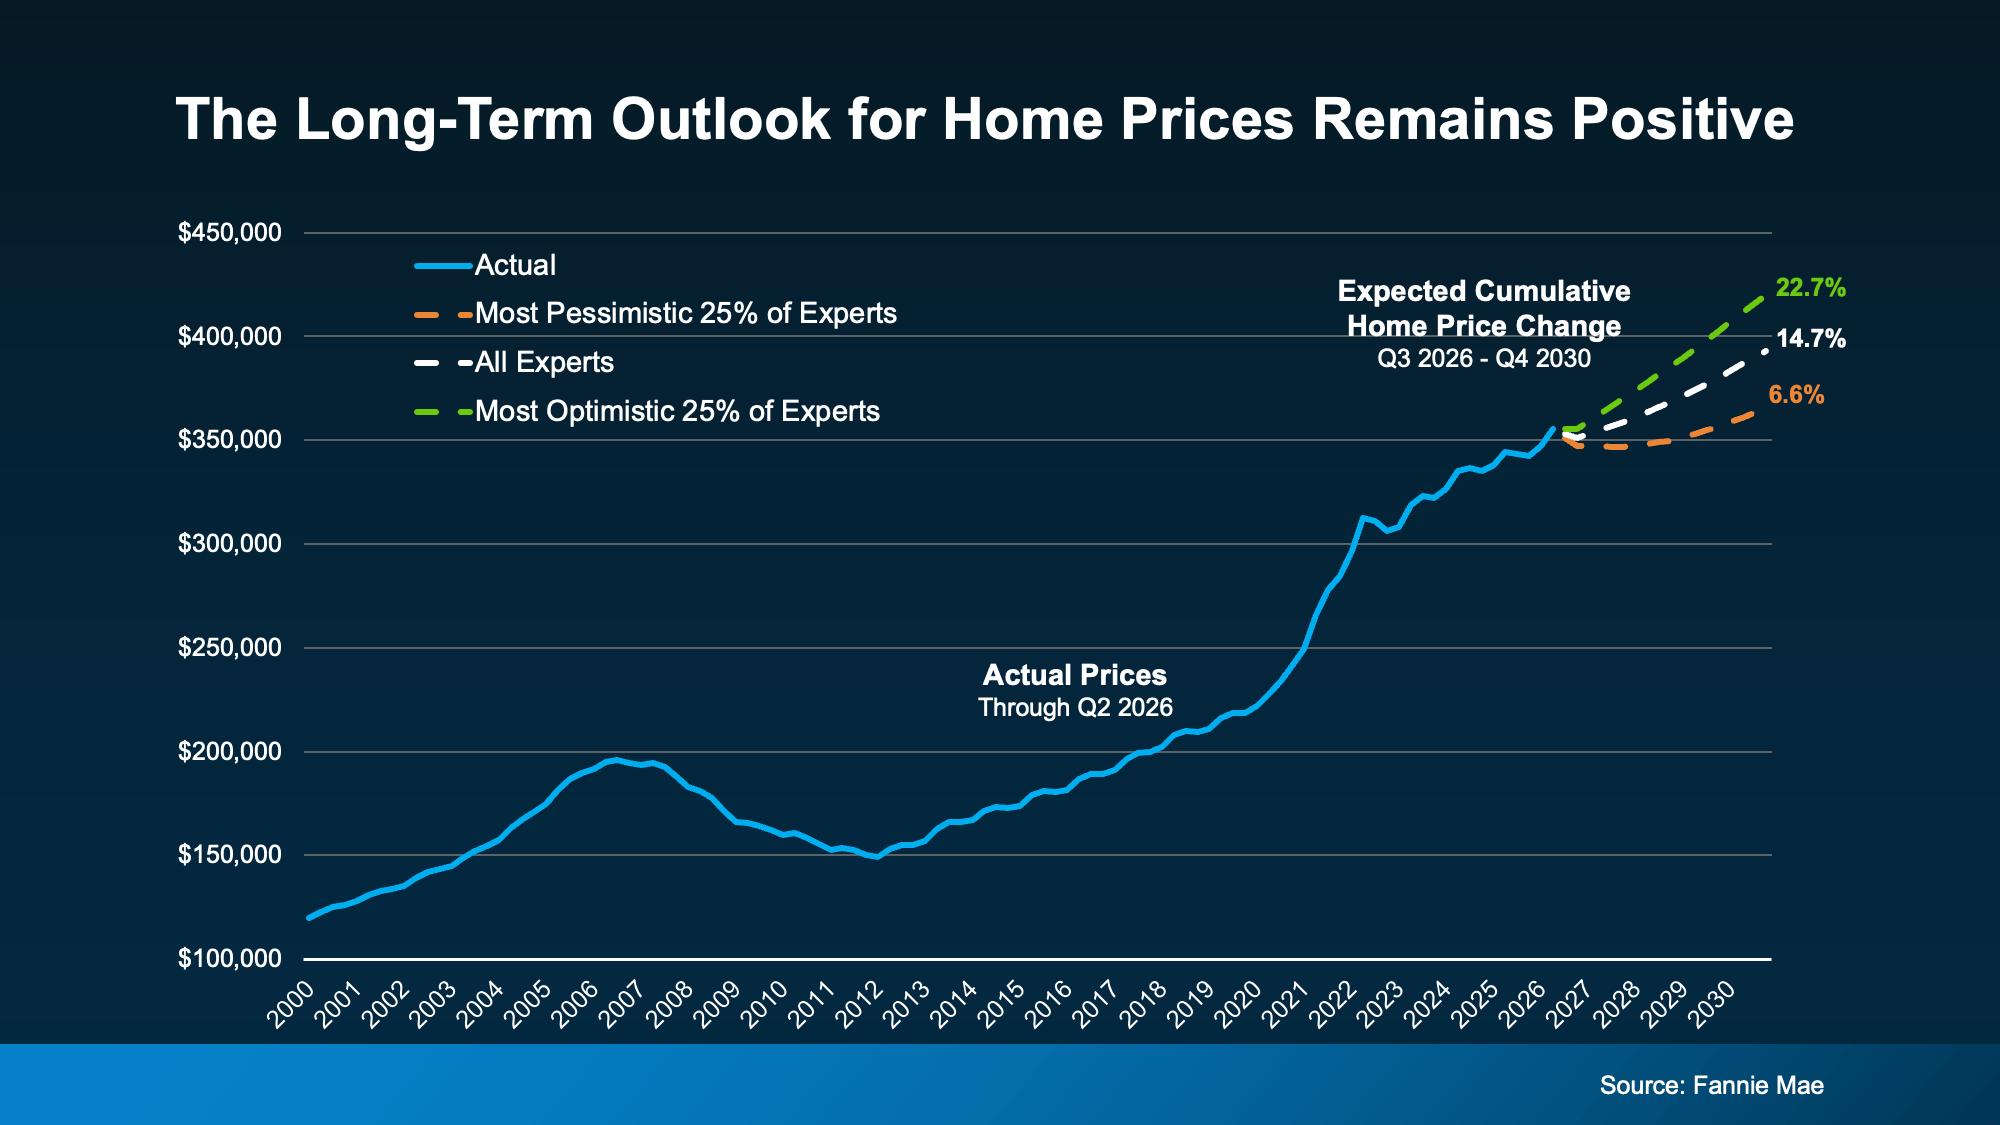
The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.
One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.
How This Quarter Compares to the Past
Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.
A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):
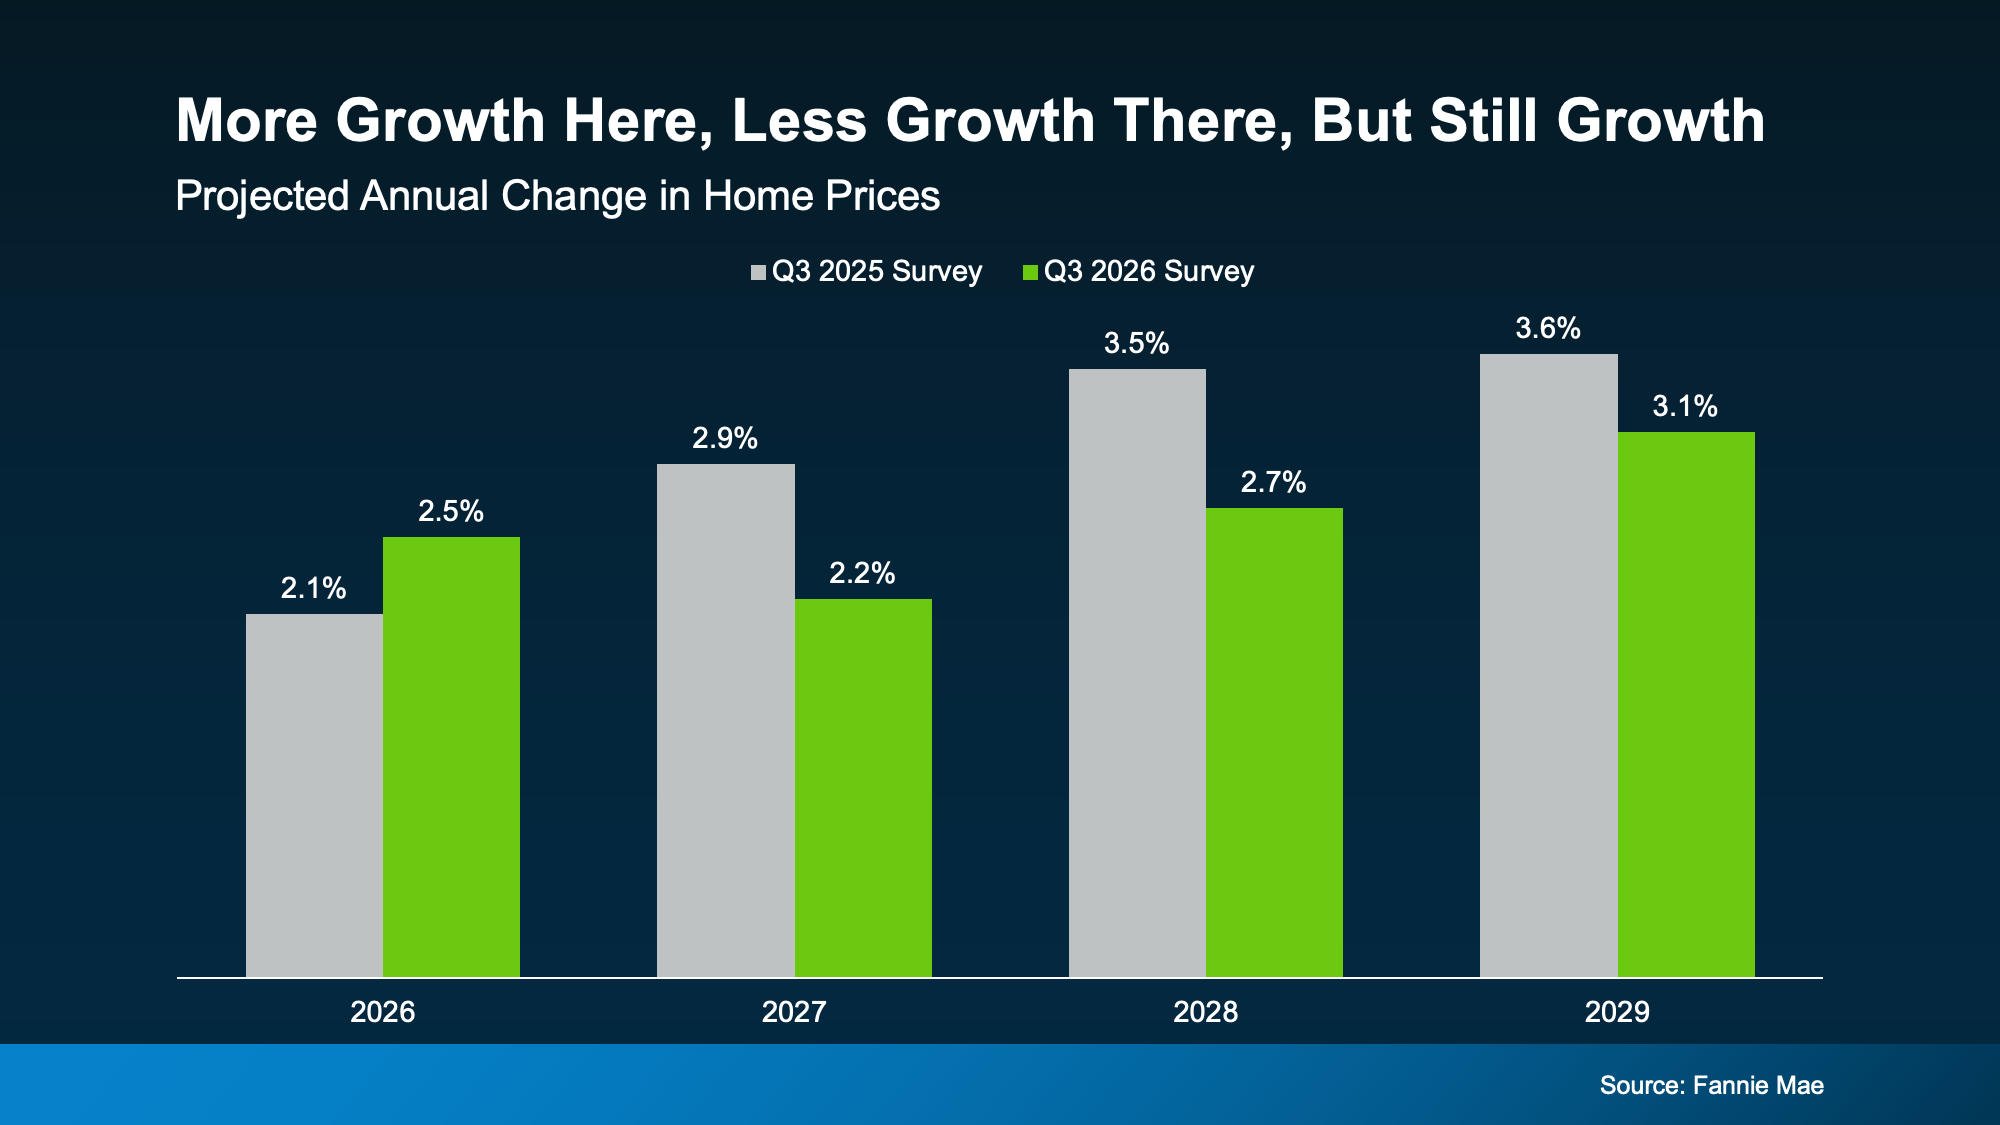
Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.
But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.
A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.
A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.
What It Means for Your Next Move
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.
Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):
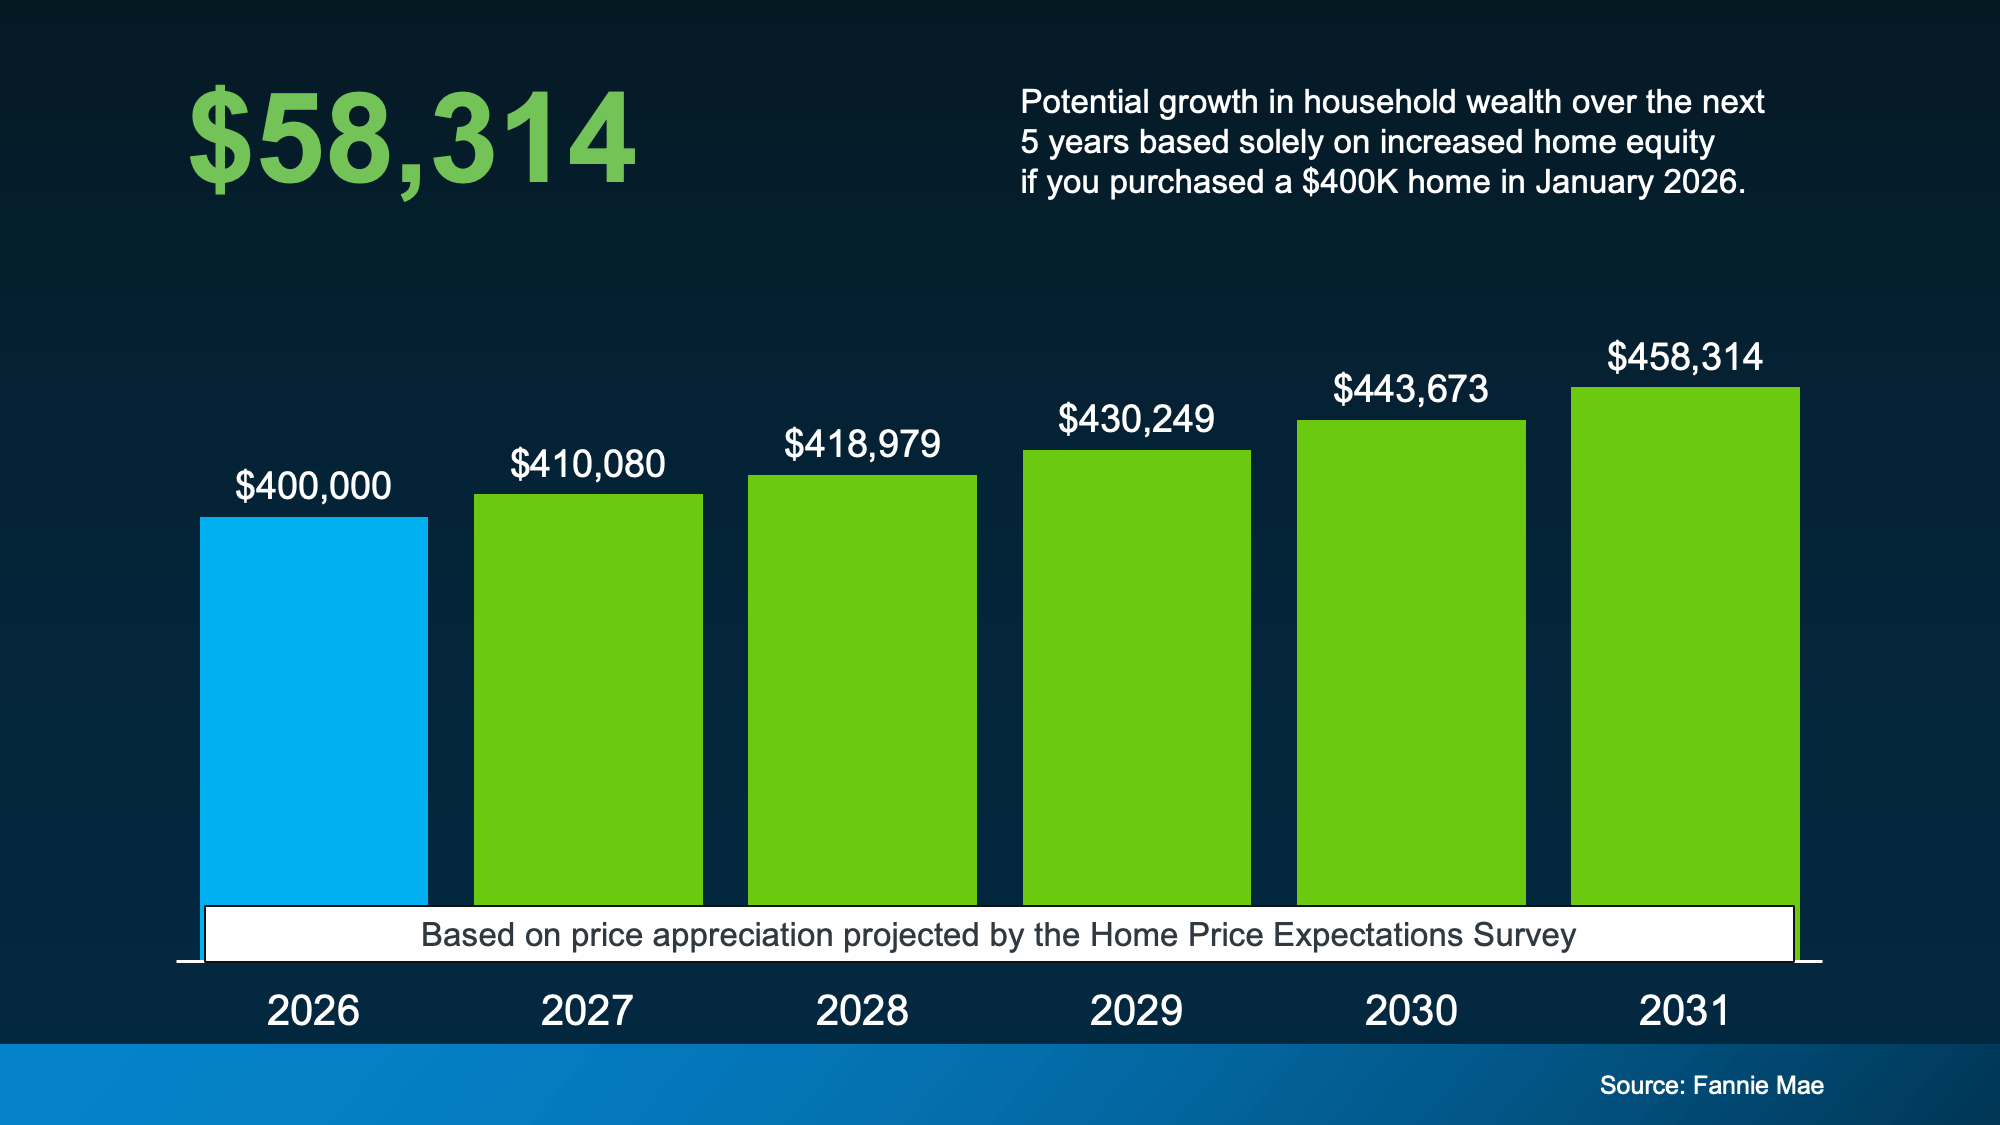
That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.
Bottom Line
Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

Confused by Home Price Headlines? Here’s Why.

Want a More Affordable Home? Don’t Overlook Condos.

The Biggest Credit Hurdle for Renters Who Want To Buy


-
 Buying Tips3 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 Agent Value4 weeks ago
There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?
-
 For Sellers3 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability4 weeks ago
Why So Many Sellers Are Cutting Their Price Right Now
-
 Affordability3 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Affordability2 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Affordability2 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Downsize2 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
You must be logged in to post a comment Login