Agent Value
3 Must-Do’s for First-Time Home Buyers
Today’s housing market splits into four distinct types. You’ve got cash buyers, buyers financing a purchase, owners who feel locked into a low rate, and builders with homes to sell. Which type you’re in changes how you should buy or sell. Ryan Serhant, CEO of SERHANT agrees:
“There is no longer a housing market . . . There are four Americas.”
Here’s what each looks like, and what it means for you.
Cash Buyers: 1 in 4 Buyers Are Paying with Cash
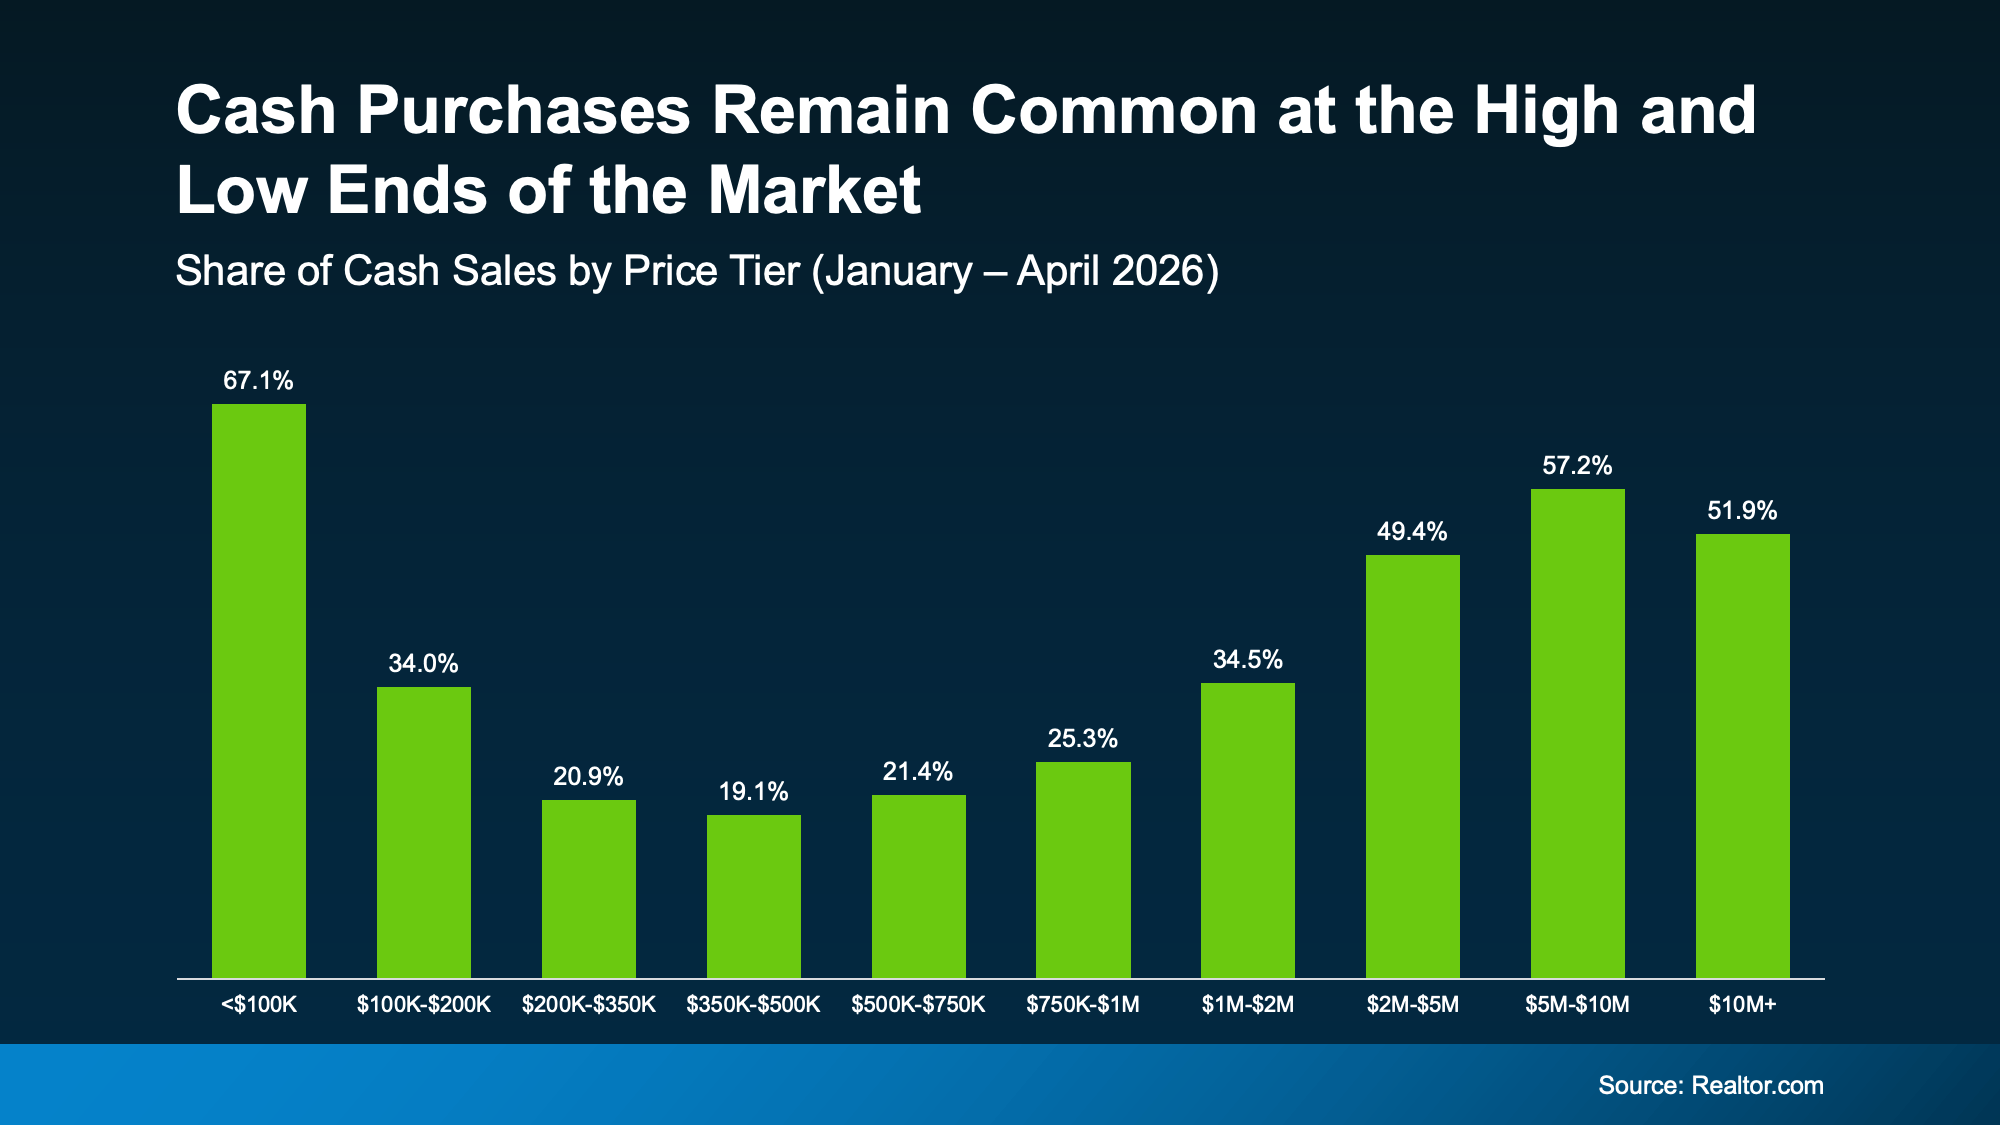
If you already own a home, you may be able to buy your next place in cash thanks to your equity. In fact, 26% of existing home sales this summer were all-cash, according to the National Association of Realtors (NAR). That’s roughly 1 in 4 buyers skipping a home loan entirely.
Data from Realtor.com shows most are at the very top and very bottom of the market by price point (see graph below):
For Buyers: If you’re able to buy in cash too, having no financing contingency means your offer is going to look really appealing to sellers. You may get a faster close and more room to negotiate.
For Sellers: A cash offer can mean less risk of the deal falling through, but that certainty sometimes comes with a lower number attached. Compare the whole picture before deciding it’s automatically your best offer.
Buyers Using Financing: They’re Not Getting Help from Rates, But They Are from Sellers
If you’re looking to take out a mortgage, you should know mortgage rates aren’t likely to come down anytime soon. Data from Fannie Mae shows nearly half of experts actually raised their long-term rate forecast this year (see graphs below):
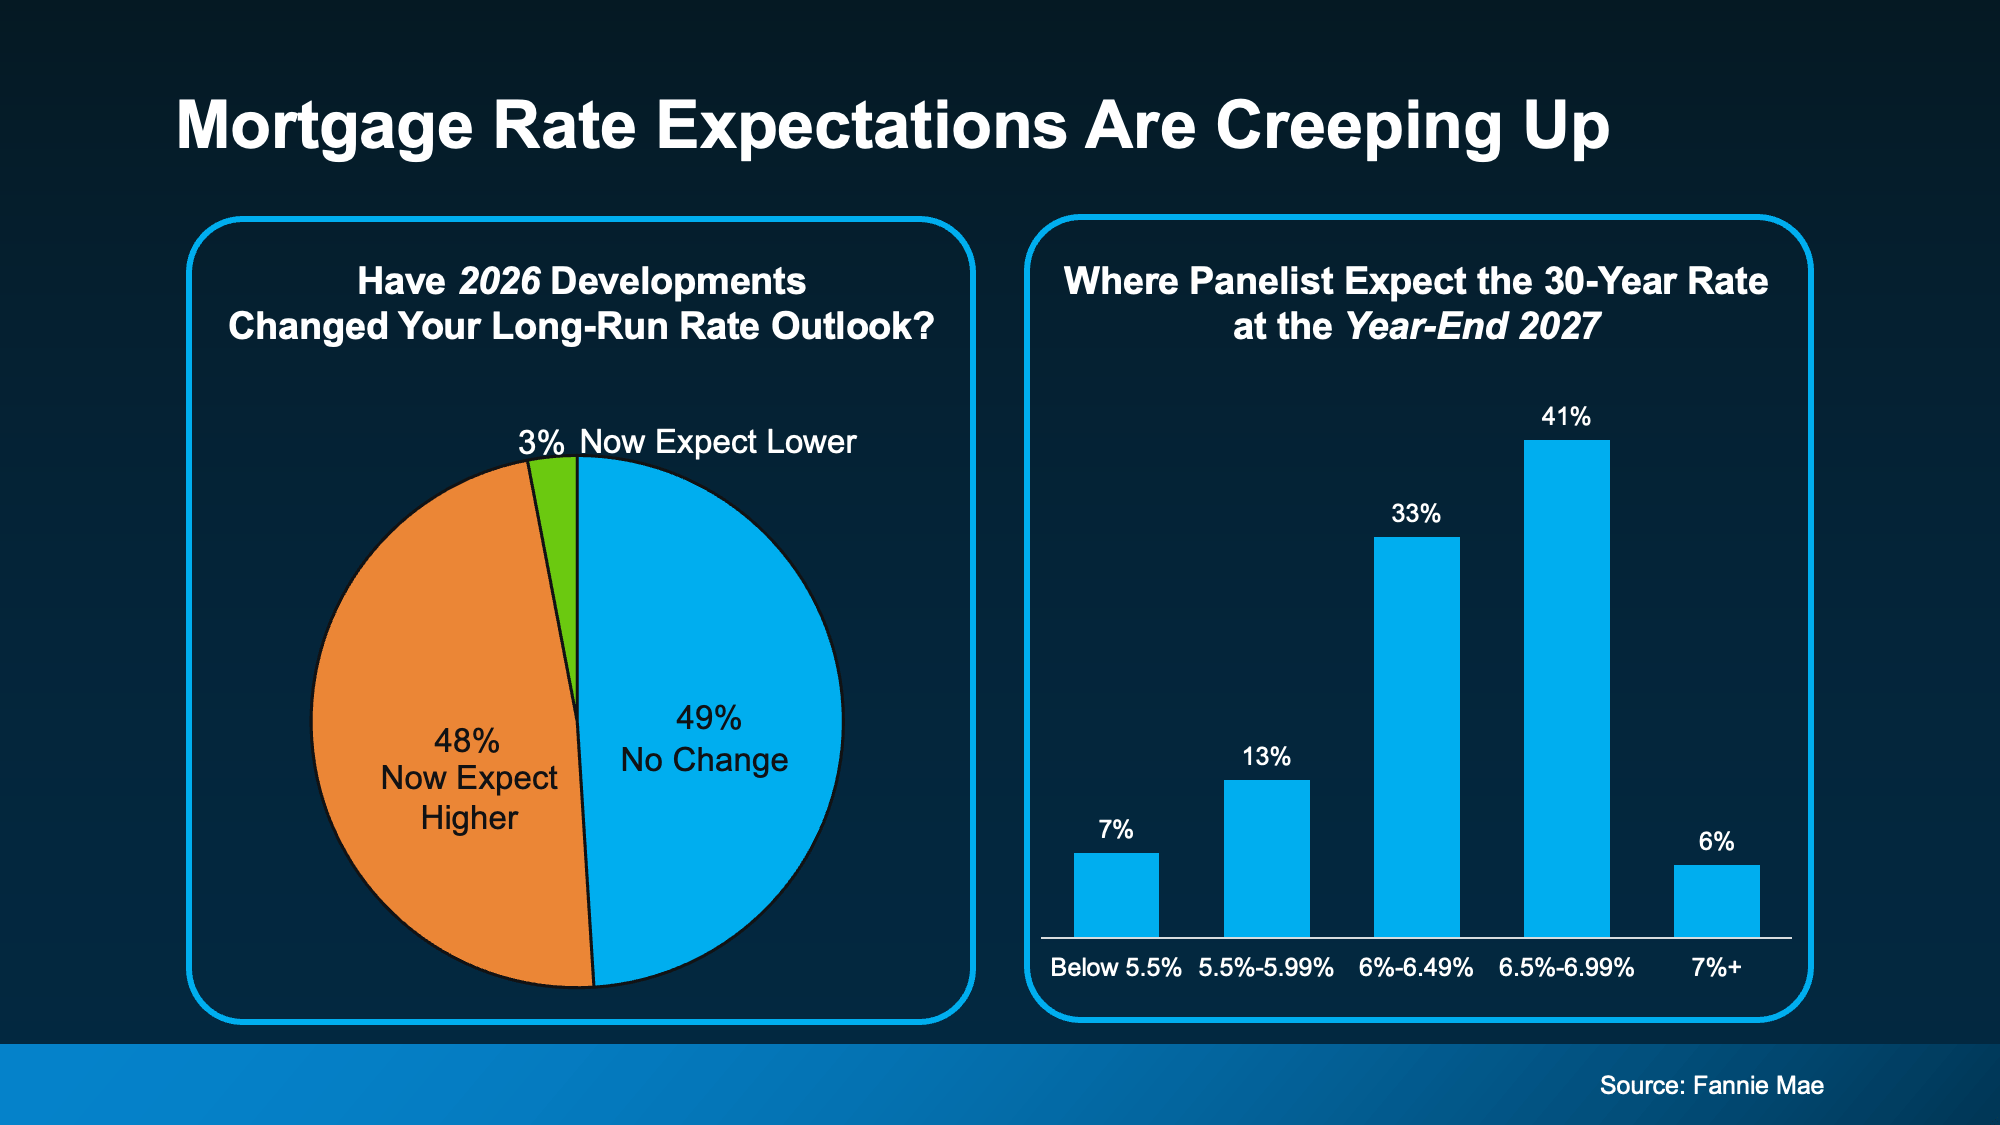
That’s tough for homebuyers relying on a mortgage, especially first-time buyers. But it’s not all bad news.
While buyers may not be getting the lower rates they want, at least there’s help to be had if you ask sellers for what you really need. Redfin data shows almost half of May sales included a concession like a rate buydown or closing-cost credit from the homeowner.
For Buyers: Stop waiting on rates to drop. Negotiate the concession instead. If the payment works today, that’s your signal.
For Sellers: Expect to negotiate. Build a concession into your pricing strategy from the start could be the thing that gets a deal done.
Rate-Locked Homeowners: Most Are Sitting on a Rate Below 5%
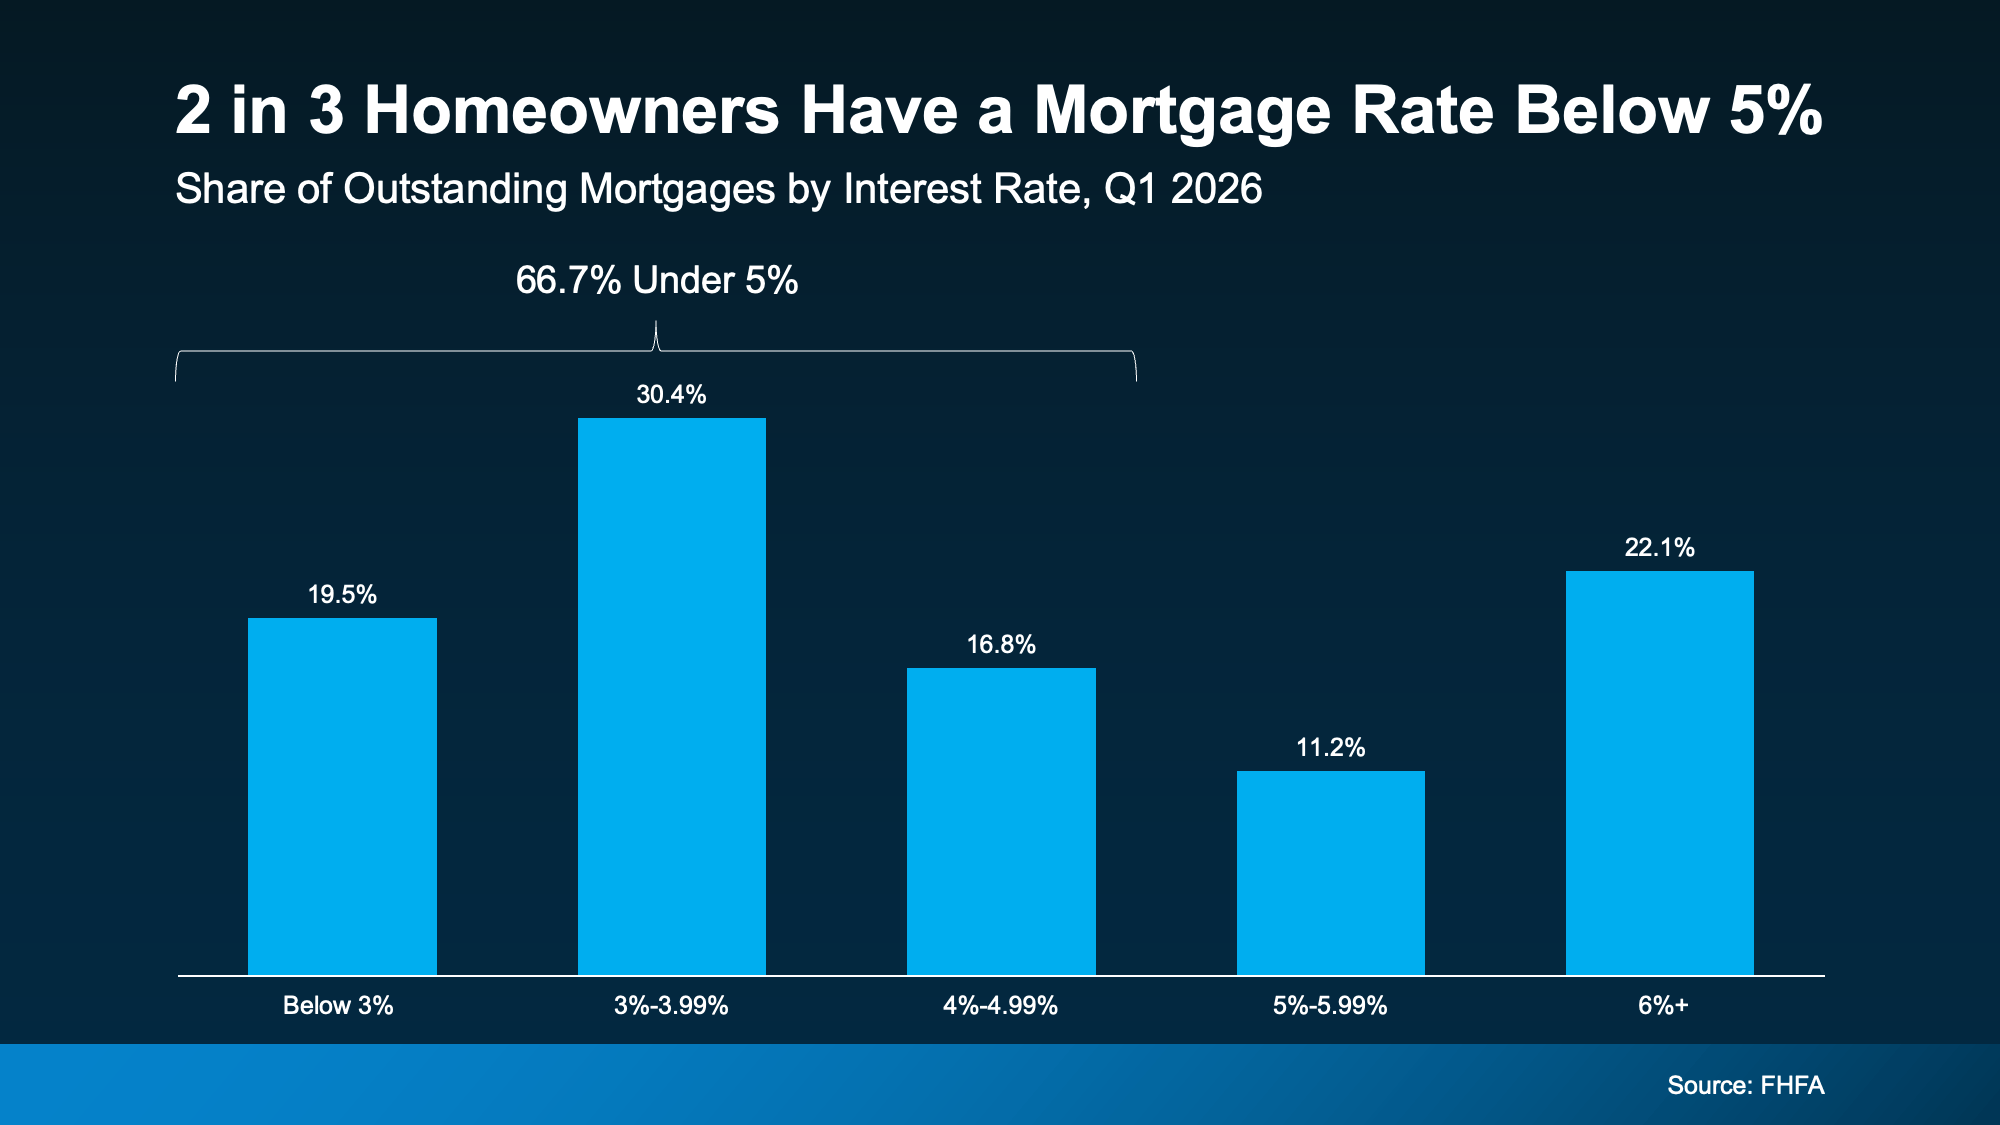
If you own a home already, you might not want to move and take on a higher rate than the one you’ve got. That’s the case for a lot of people. About 2 in 3 homeowners have a mortgage rate under 5%, according to Federal Housing Finance Agency (FHFA) data (see graph below).
When a homeowner has a rate that low, it’s harder for them to want to move and leave behind that ultra-low rate. Because, they’d likely have to take on a higher one on their next home. Hence “rate locked” – they feel locked in.
And, according to Fannie Mae data, most experts think that lock-in will stick around another 3-5 years. That means this will continue to be a factor in how many homes come up for sale.
For Buyers: Fewer homeowners are listing, but the ones who do usually have a real reason to move. They’re often more flexible, motivated sellers.
For Sellers: Run the math on what your equity actually buys before ruling out a move. Got an FHA or VA loan? Ask about making it assumable. It’s rare, but it’s a real selling point.
Homebuilders: They’re Negotiating More Than You Think
If you’re looking at new construction, this might be your moment. According to the latest Census data, builders have more unsold new homes sitting around than usual, enough that it would take nearly 10 months to sell them all at the current pace (well above the normal 4-6 months pace). That’s pushing builders toward price cuts and rate buydowns.
For Buyers: That’s where the deals are right now. Just be sure to use your own agent and compare the whole incentive package, not only the price tag.
For Sellers: Lead with what a builder can’t offer – mature landscaping, an established neighborhood, and a house that’s ready today, not in 8 months. That can help your house seem like a better optiona
Bottom Line
Four different housing markets are running at once: cash buyers, financed buyers, locked-in owners, and builders. Each one plays by its own rules, and the right move for one is exactly the wrong move for another.
Connect with a local real estate agent to figure out which one you’re actually in and build your next move from there.
Summer’s winding down, and if you’ve been thinking about selling, you might be wondering if you missed your chance. Better to wait until next year or even next spring, right?
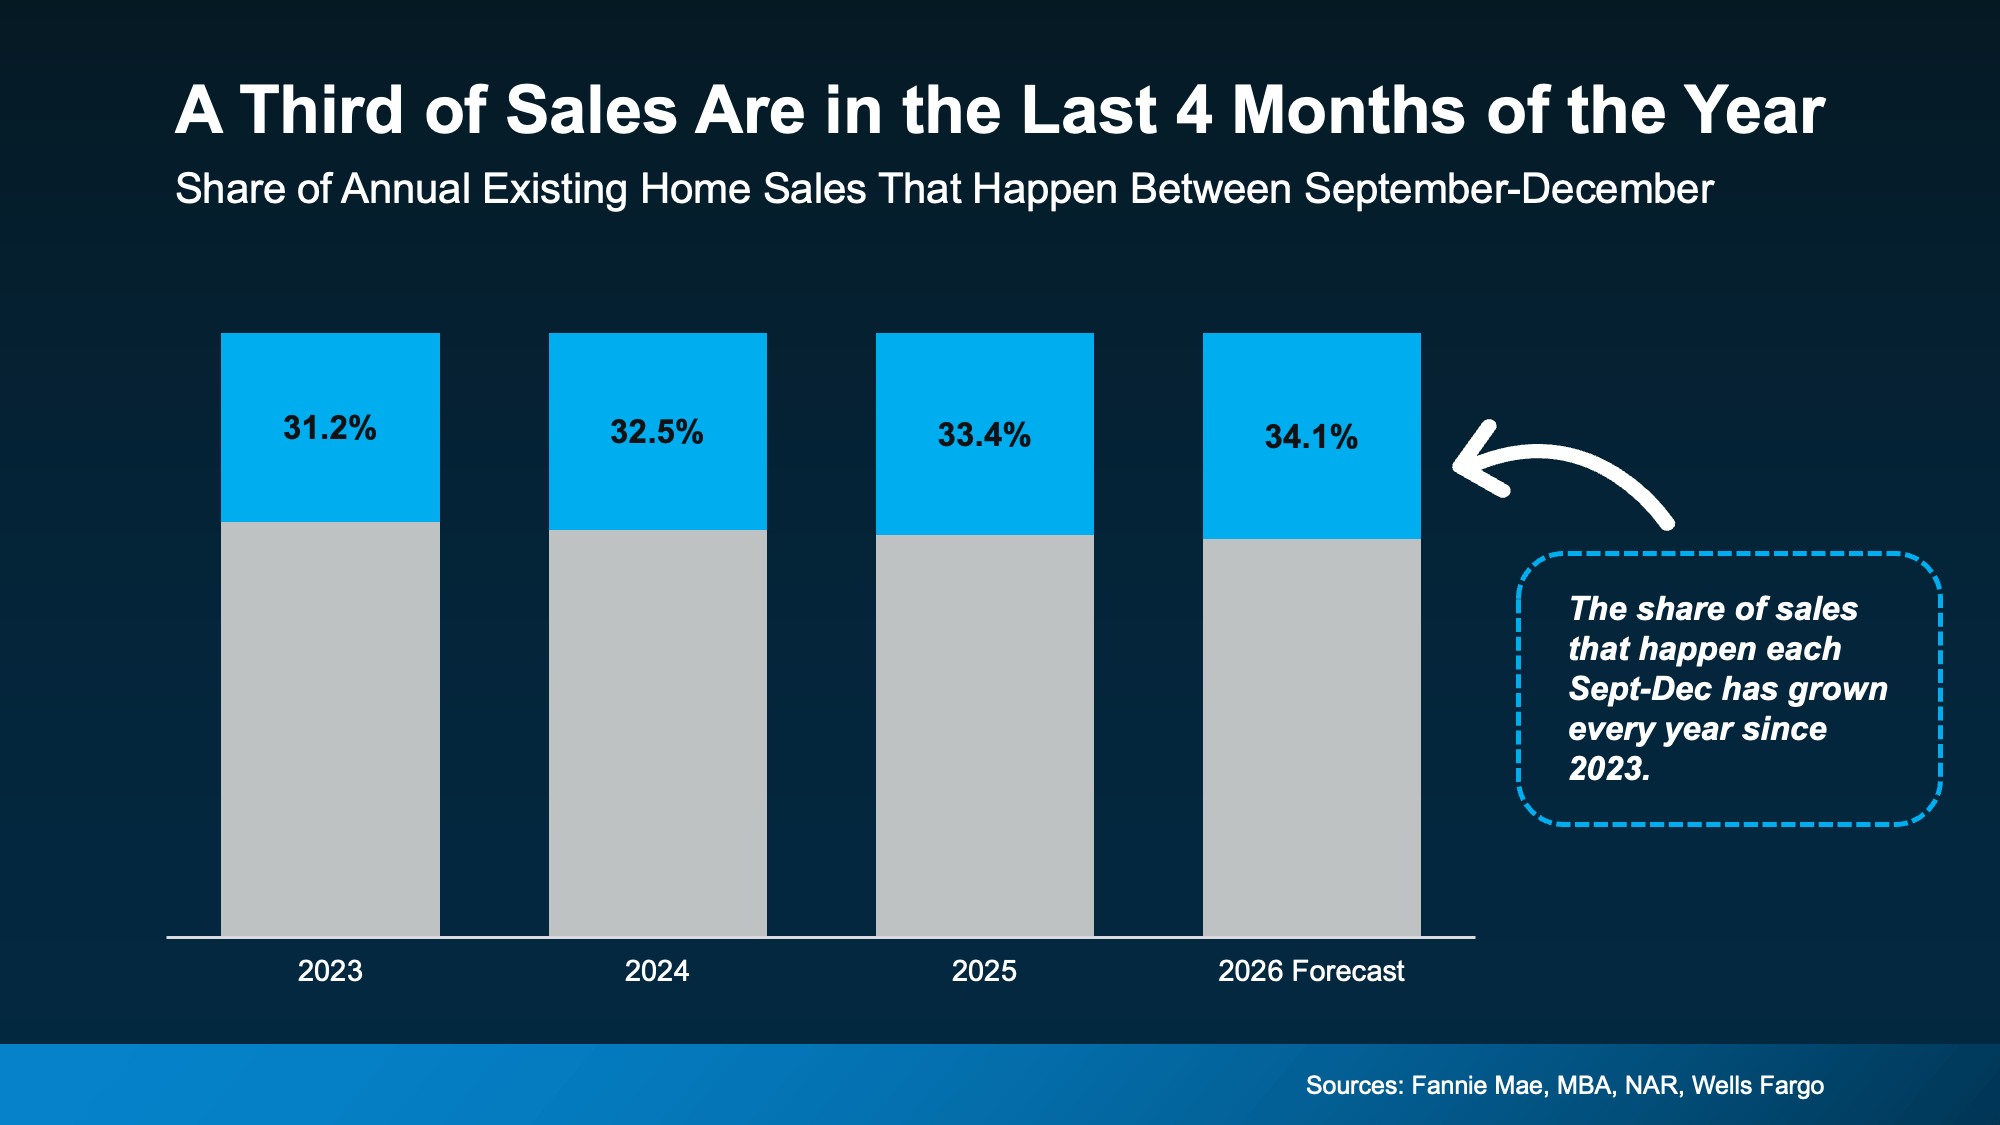
Not so fast. About one in three of all home sales happen in the last four months of the year.
Fall Is Busier than You Think
Data from the National Association of Realtors (NAR) shows around a third of existing home sales happen in the final four months of the year. And that share has grown every year since 2023 (see graph below):
Here’s What That Means for You
According to forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), NAR, and Wells Fargo, there will be about 4.16 million existing home sales this year. Based on how many sales have happened so far, that means roughly 1.4 million sales are expected between now and December.
That’s about 11,800 houses selling every single day this fall.
So, the market isn’t frozen and you don’t need to put your plans on ice either. Yes, higher rates are keeping some buyers on the sidelines. But hold out for next spring, and you’ll sit out months when other serious buyers are ready to move before the new year.
How do you get in front of those buyers who are still out there looking right now? Getting your house sold this season comes down to how well it’s priced and presented, and that’s where a local agent shines.
A good agent knows what buyers in your area want right now, prices your house to match this fall’s market, and positions it to stand out to the serious buyers shopping before year-end. From the first photo to the final offer, they handle the details that turn your house on the market into one of the 11,800 selling every day.
Bottom Line
Listing this fall doesn’t mean your house will sit on the market until spring. Buyers are out there right now, ready to make a move before the new year – and your window is still open.
To make yours one of the homes that sells this season, connect with a local real estate agent.
Ask a couple people how the housing market is doing and you’ll probably get a couple different answers. That’s because right now, the market runs on 2 very different tracks, split by price point.
Knowing which track your house is on changes everything about your sale, from your asking price to how long you can expect to wait before an offer comes in. Here’s what you need to know.
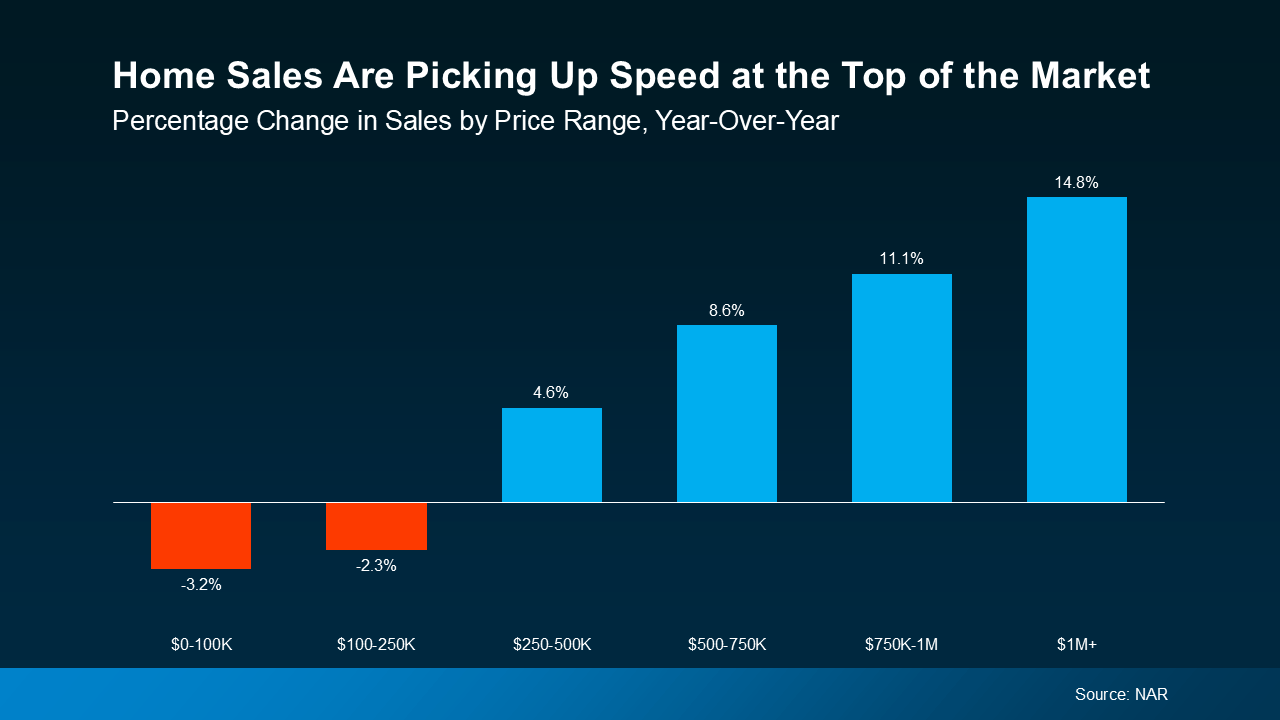
Home Sales Are Picking Up Speed at the Top of the Market
Rates and buyer competition are shaping this market differently depending on price point. Look at recent sales data from the National Association of Realtors (NAR) and the pattern jumps right out.
Homes priced under $250,000 saw sales drop 2-3% compared to last year, while homes priced above $750,000 saw sales climb by double digits (see graph below):
 What’s behind the divide? Due to higher rates and the last few years of home price appreciation, fewer buyers can comfortably afford homes at the entry-level price point right now – especially first-time buyers. So, demand in that segment has slowed down.
On the flip side, buyers looking for higher-priced homes have less sensitivity to high-rate environments and more room in their budgets, thanks in part to a strong stock market and their equity in their current home.
That’s the real differentiator. Lower-priced homes are still selling, just not as quickly since today’s rates have shrunk the pool of buyers who can afford to buy their first place right now.
This is exactly why pricing strategy and presentation carry more weight than they used to, especially if you’re selling in that range. Price it right from the start instead of testing a high number, make sure it shows well online and in person, and lean on an agent who can get your listing in front of every buyer shopping in your range. That’s the best way to make sure you catch the attention of one of the buyers who are still looking – and it’s how you prove your home is worth it’s price.
Why Some Homes Sit While Others Get Snapped Up
How fast a home sells is shifting by price point too, and the split is just as sharp. For years, luxury homes sat on the market a lot longer than starter homes. That gap has nearly closed, according to Redfin (see chart below):
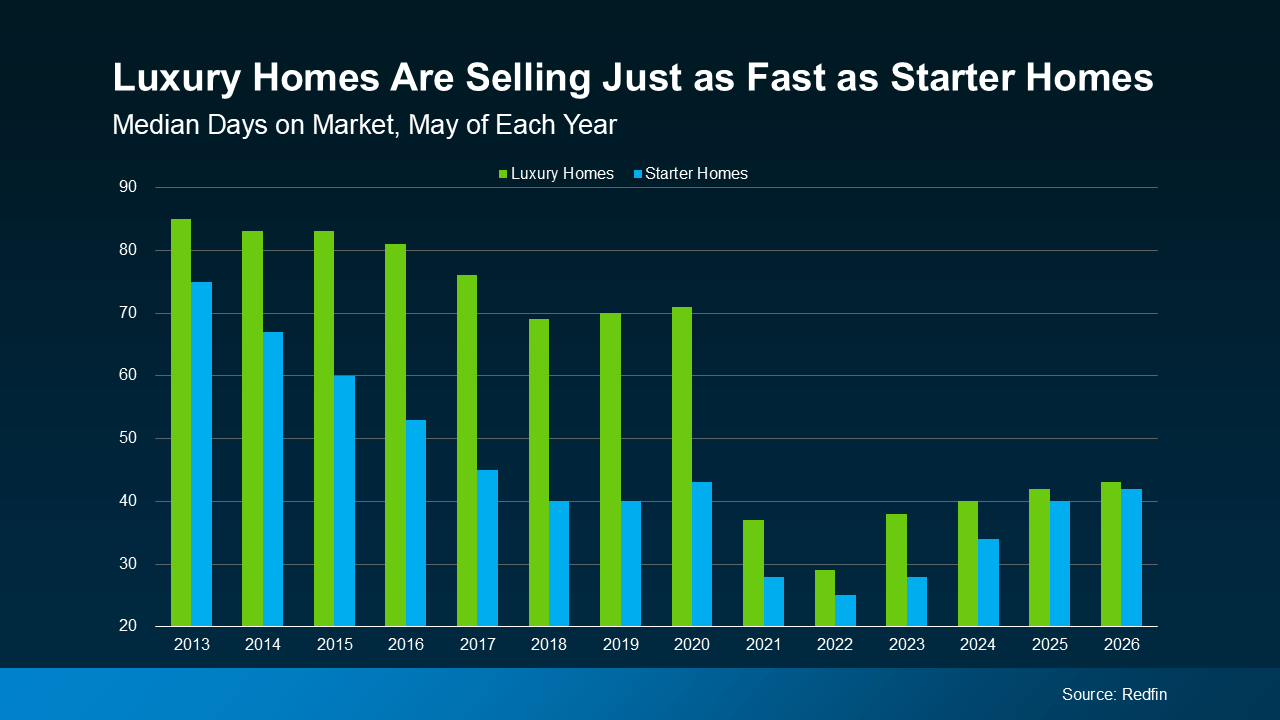 Buyers with deep pockets are moving fast when a well-priced home in their range comes up. As Zillow puts it:
“The U.S. housing market is splitting in two. Luxury homes are selling at a faster pace than a year ago, with shrinking supply and growing bidding wars.”
If you’re in that range, your house may sell faster than you’d expect. You may even get multiple offers. That kind of competition changes how a listing should be marketed and priced from day 1.
And no matter which side you’re on, that’s information you’re going to want up front if you want to have the smoothest sale possible.
What This Means for Your Sale
If you’re thinking about selling an entry-level home, don’t panic. Homes at your price point are still selling, just at a slower pace than last year. That slower pace means pricing and presentation matter even more right now.
If you’re selling a move-up or luxury house, you’re in a good spot right now. Buyers looking in your price point usually aren’t as affected by today’s rates, so they’re more active, and good listings are drawing real competition.
Either way, your price point is the biggest factor in how fast your house sells and what it sells for.
Bottom Line
Your home’s price point is the real story right now, more than anything you’re hearing in national headlines. Connect with a local real estate agent to map out exactly where your house fits in this split market and build a pricing strategy that gets you the speed and price you’re after.

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?

3 Things You Can Actually Control About Your Mortgage Rate Right Now

Selling This Fall? You Want To Get These 4 Things Right.


-

 For Buyers4 weeks ago
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
-
 Affordability4 weeks ago
Sellers Are Cutting Prices To Meet Buyers Where They’re At
-
 Affordability3 weeks ago
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
-
 Affordability3 weeks ago
Think New Homes Cost More? Not Right Now.
-
 Affordability3 weeks ago
Why Buyers Shouldn’t Overlook a Fall Move
-
 Affordability2 weeks ago
Remote Work Could Be Your Affordability Answer
-
 Agent Value2 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
-
 For Buyers2 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
You must be logged in to post a comment Login