For Buyers
There’s No Reason To Panic Over Today’s Lending Standards
Today, some are afraid the real estate market is starting to look a lot like it did in 2006, just prior to the housing crash. One of the factors they’re pointing to is the availability of mortgage money. Recent articles about the availability of low down payment loans and down payment assistance programs are causing fear that we’re returning to the bad habits seen 15 years ago. Let’s alleviate these concerns.
Several times a year, the Mortgage Bankers Association releases an index titled The Mortgage Credit Availability Index (MCAI). According to their website:
“The MCAI provides the only standardized quantitative index that is solely focused on mortgage credit. The MCAI is…a summary measure which indicates the availability of mortgage credit at a point in time.”
Basically, the index determines how easy it is to get a mortgage. The higher the index, the more available mortgage credit becomes. Here’s a graph of the MCAI dating back to 2004, when the data first became available: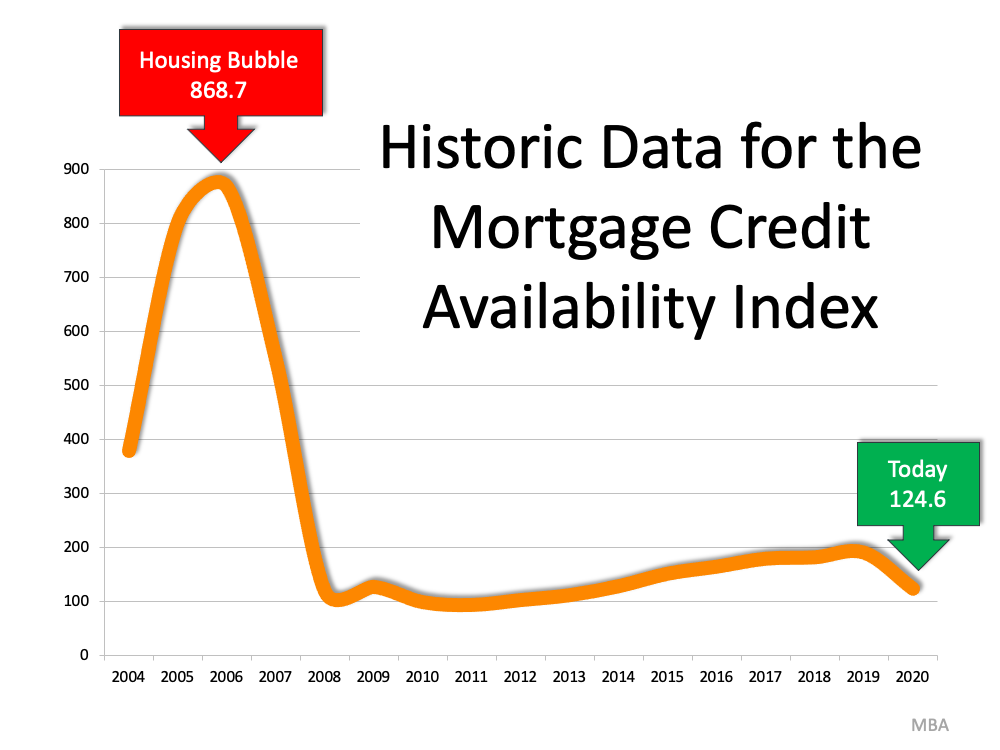 As we can see, the index stood at about 400 in 2004. Mortgage credit became more available as the housing market heated up, and then the index passed 850 in 2006. When the real estate market crashed, so did the MCAI (to below 100) as mortgage money became almost impossible to secure. Thankfully, lending standards have eased somewhat since. The index, however, is still below 150, which is about one-sixth of what it was in 2006.
Why did the index rage out of control during the housing bubble?
The main reason was the availability of loans with extremely weak lending standards. To keep up with demand in 2006, many mortgage lenders offered loans that put little emphasis on the eligibility of the borrower. Lenders were approving loans without always going through a verification process to confirm if the borrower would likely be able to repay the loan.
Some of these loans offered attractive, low interest rates that increased over time. The loans were popular because they could be obtained quickly and without the borrower having to provide documentation up front. However, as the rates increased, borrowers struggled to pay their mortgages.
Today, lending standards are much tighter. As Investopedia explains, the risky loans given at that time are extremely rare today, primarily because lending standards have drastically improved:
“In the aftermath of the crisis, the U.S. government issued new regulations to improve standard lending practices across the credit market, which included tightening the requirements for granting loans.”
An example of the relaxed lending standards leading up to the housing crash is the FICO® credit score associated with a loan. What’s a FICO® score? The website myFICO explains:
“A credit score tells lenders about your creditworthiness (how likely you are to pay back a loan based on your credit history). It is calculated using the information in your credit reports. FICO® Scores are the standard for credit scores—used by 90% of top lenders.”
During the housing boom, many mortgages were written for borrowers with a FICO score under 620. Experian reveals that, in today’s market, lenders are more cautious about lower credit scores:
“Statistically speaking, 28% of consumers with credit scores in the Fair range are likely to become seriously delinquent in the future…Some lenders dislike those odds and choose not to work with individuals whose FICO® Scores fall within this range.”
There are definitely still loan programs that allow a 620 score. However, lending institutions overall are much more attentive about measuring risk when approving loans. According to Ellie Mae’s latest Origination Insight Report, the average FICO® score on all loans originated in February was 753.
The graph below shows the billions of dollars in mortgage money given annually to borrowers with a credit score under 620.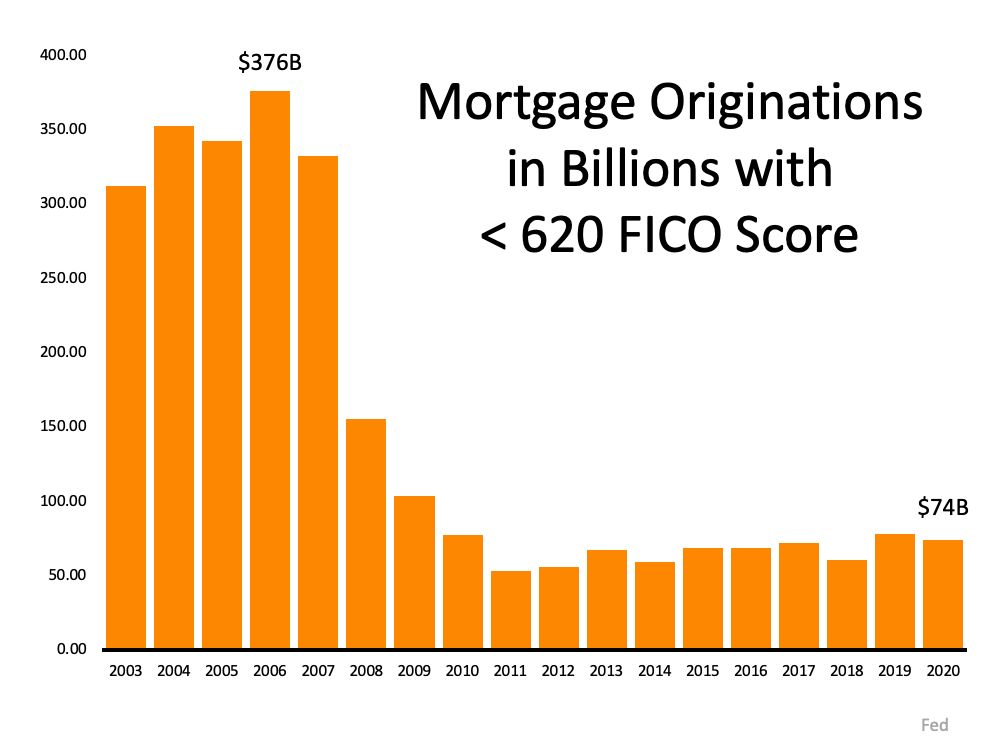 In 2006, mortgage entities originated $376 billion dollars in loans for purchasers with a score under 620. Last year, that number was only $74 billion.
Bottom Line
In 2006, lending standards were much more relaxed with little evaluation done to measure a borrower’s potential to repay their loan. Today, standards are tighter, and the risk is reduced for both lenders and borrowers. These are two very different housing markets, so there’s no need to panic over today’s lending standards.
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.
Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:
“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”
But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):
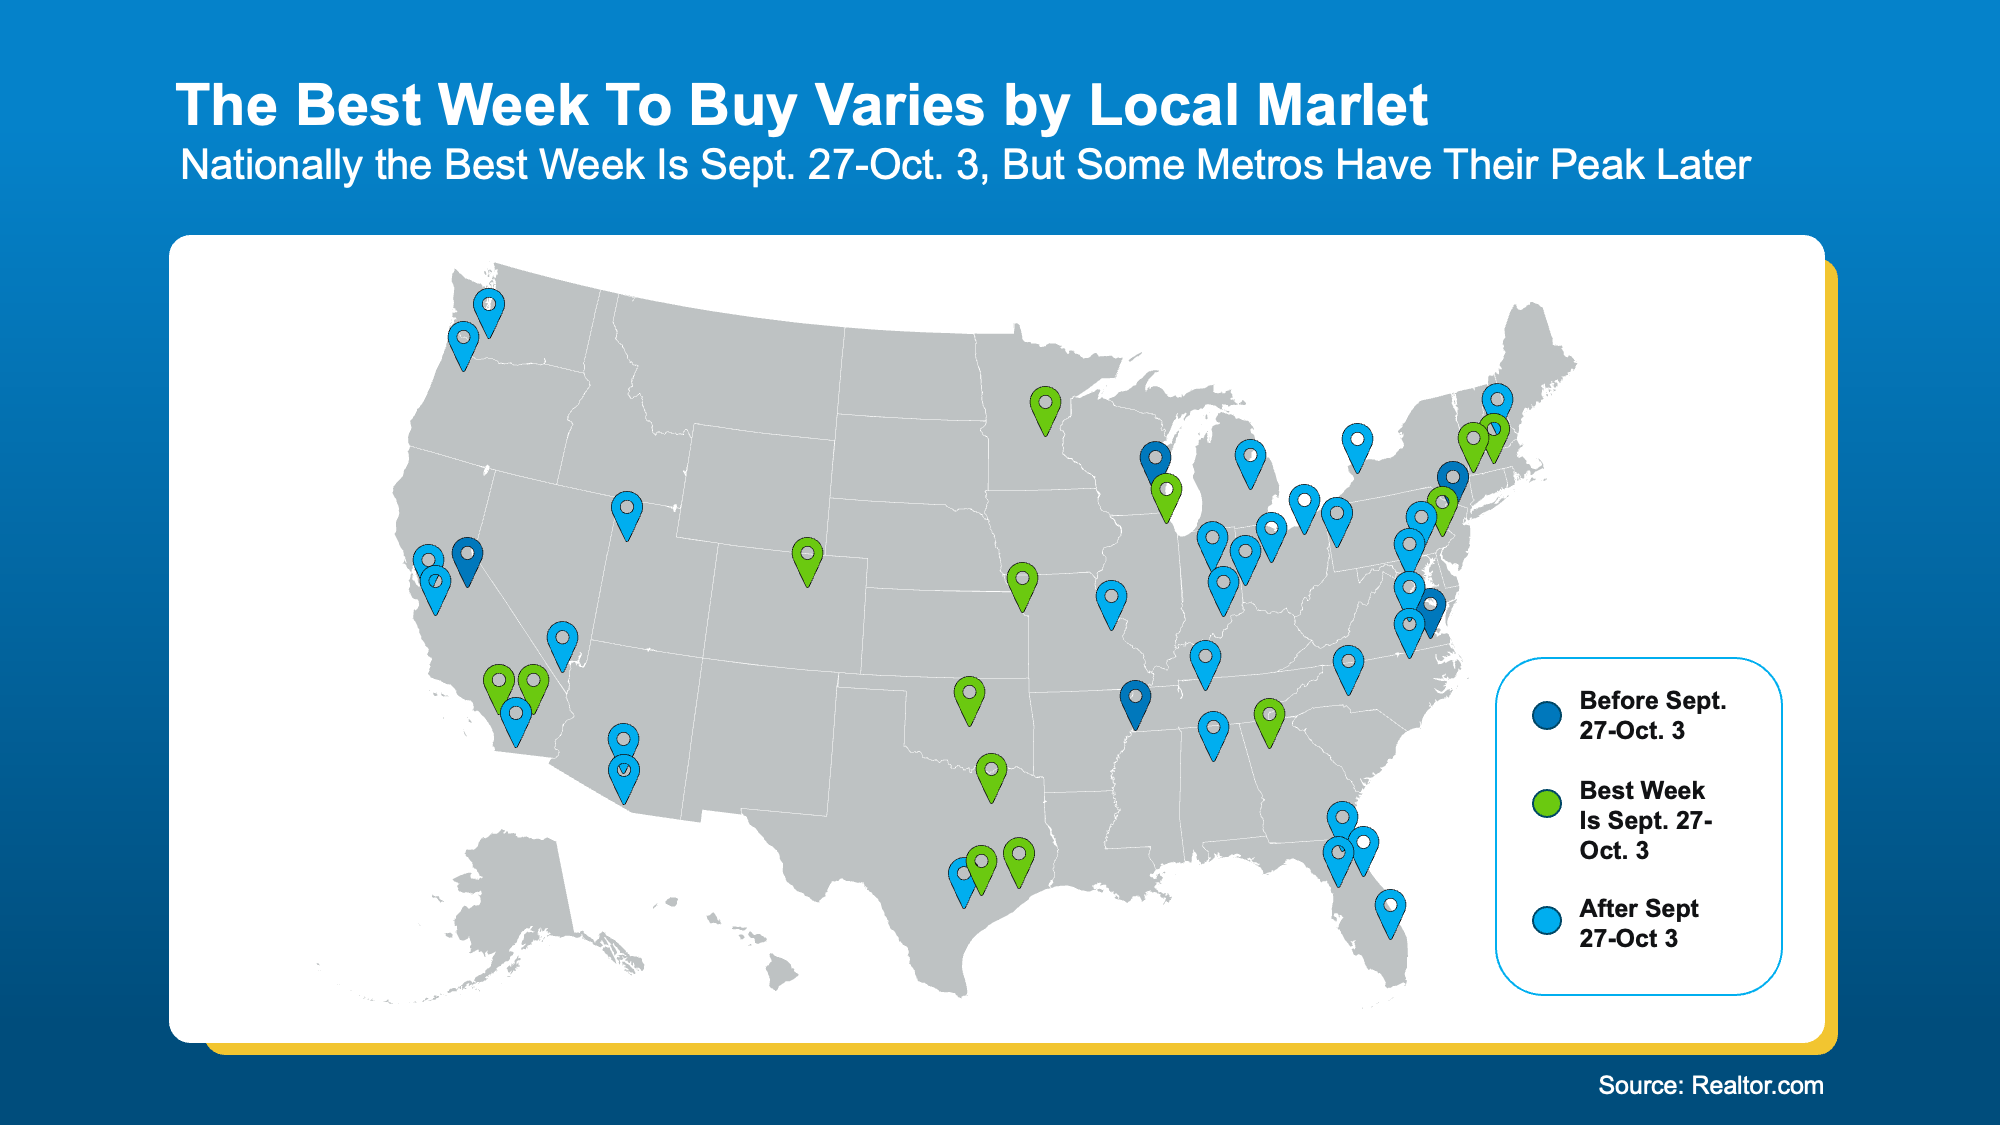
It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.
More Choices, Better Prices, and Less Competition
For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:
“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”
That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.
Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision.
-
More choices.
-
Better pricing.
-
Less competition.
That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.
The Window Doesn’t Close After This One Week
But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:
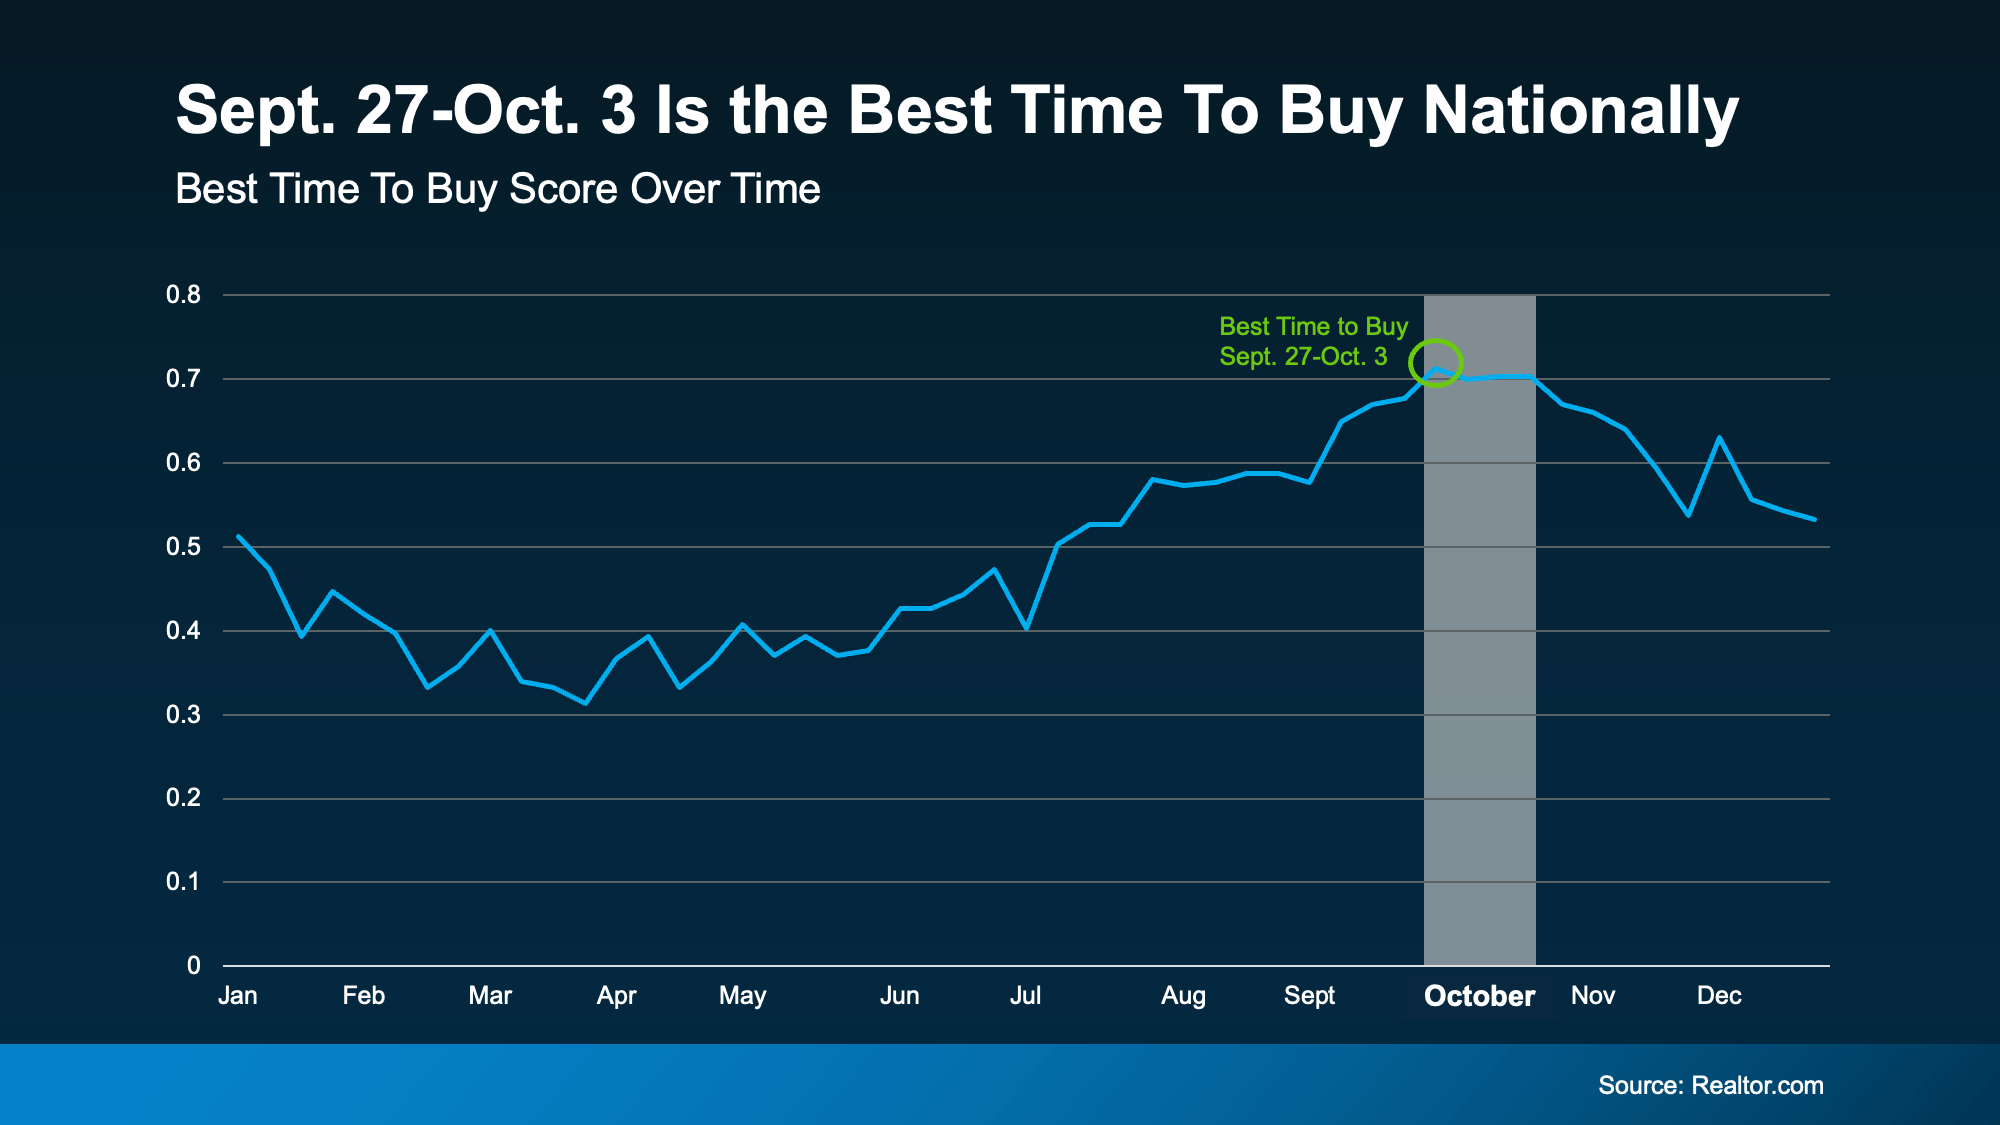
In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains:
“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”
Bottom Line
If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.
Want help figuring out when those advantages typically show up in your market?
Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready.
Data centers probably weren’t on your list of things to think about when buying or selling a home.
School districts? Sure. How close you are to family? Absolutely. A large building full of computer servers down the road? Probably not.
But that may be changing.
Data centers are popping up in more communities across the country. And as they do, buyers and homeowners are starting to wonder what having one nearby could mean for everything from home values to utility bills. So, let’s get into what the data actually says. Because there’s a lot more nuance here than if they’re “good” or “bad.”
Data Centers Are Showing Up in a Lot More ZIP Codes
According to Realtor.com, back in 2015, only about a dozen ZIP codes had a large data center. But by the first half of 2026, that number had climbed to more than 100 – and it’s projected to rise even further by the end of the year (see graph below):
 That’s a pretty dramatic increase in just over a decade. HousingWire shows a lot of that growth is in Texas, Virginia, Georgia, Pennsylvania, Ohio, Utah, Illinois, Arizona, Indiana, and Nevada.
And that ramp up explains why this is becoming a real estate conversation. More buyers are going to encounter a data center during their search. More homeowners are going to hear about one being proposed nearby.
And both groups are going to want to know what that could mean for them.
The Big Question: What About Home Values?
One of the first concerns homeowners and buyers may have is: could a nearby data center hurt home values? So far, there’s no evidence that says it automatically will.
Researchers compared communities that have large data centers to similar communities without them. A recent HousingWire article reports:
“. . . home values in data center ZIP codes generally tracked their matched communities — with no statistically meaningful gains or losses. Listing prices showed a modest initial increase around openings . . .”
That’s important context. Historically, simply having a data center nearby hasn’t been enough to send home values dramatically higher or lower.
That doesn’t mean every property will react the same way. Proximity, the surrounding development, and the specific facility can all matter. But for the typical homeowner or buyer, the data so far doesn’t point to an automatic impact on home values.
Living Near a Data Center Can Come with Tradeoffs
Like any major development coming to town, data centers can bring benefits along with things buyers and homeowners will want to consider.
On the plus side:
-
They may be part of a bigger growth story. A data center can usher in broader development in an area and substantial property tax revenue that can be used to improve the community.
-
Infrastructure may get an upgrade. New roads, fiber, power infrastructure, and other improvements can come along with major development.
-
They can generate economic activity. A data center can generate jobs which in turn fuels local housing demand and supports local businesses.
On the flip side:
-
They’re not exactly invisible. Large facilities, transmission lines, substations, and construction can change the look and feel of an area.
-
Noise can matter. Cooling equipment, generators, construction, and truck traffic may be noticeable depending on how close you are.
-
They use more resources. These facilities can require significant electricity and, depending on the cooling system, water. That can raise questions about local infrastructure and whether growing electricity demand could affect what residents pay.
On that last point, J.P. Blackwood, Public Affairs Liaison and Media Spokesperson for the Ohio Consumers’ Counsel (OCC), explained his take on what consumers need to know about data centers and their potential to impact utility costs to HousingWire:
“Utility rate increases tend to be gradual, and so that’s what I would expect here. Again, a number of factors can drive electricity prices higher and are driving them higher, and this is one of them. There are steps being taken around the country to mitigate the effects of data centers.”
Basically, they’re just one factor that can have an impact. And the key word there is “can” because it depends on where you live and what rules are in place in your area.
So, What Should Buyers and Homeowners Do?
If you’re buying, find out what’s already there – and what’s approved or proposed nearby. Consider the facility’s proximity, potential noise, future development, and whether utility costs are something you want to factor into your budget.
If you’re selling, don’t assume a nearby data center automatically hurts your home’s value. But buyers may have questions. Knowing the facts about the facility, construction timeline, noise, and future plans can help you address those concerns upfront.
Bottom Line
As more data centers pop up, they’re becoming another piece of the puzzle buyers and homeowners need to understand.
Have a data center nearby or one coming soon? Talk to a local real estate agent about what it could mean for your home or your next move.
For most first-time buyers, the hardest part of buying a home is making the numbers work. You budget, you save, and the finish line still feels far away.
But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don’t.
You’re not tied to living where the jobs are, so you can look where your money goes further.
Where You Work Doesn’t Have To Dictate Where You Live
Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth.
More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it:
“Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new.”
And you can use that freedom to look somewhere more affordable.
Your Paycheck Goes Much Further in Some States
Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford (see map below):
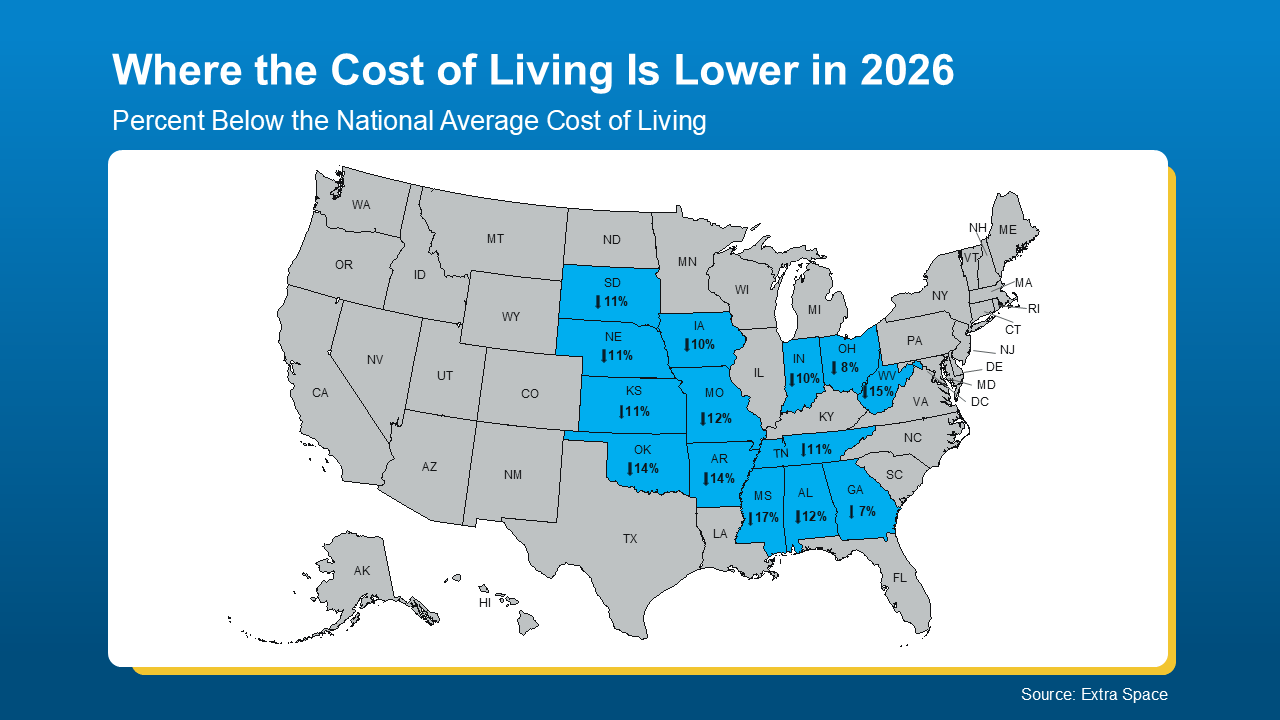 Take Mississippi, for example, where the cost of living sits about 17% below average, or West Virginia at roughly 15% below. When day-to-day life costs less, you can put more of your income toward your goals, homeownership included. Relocate Right describes it this way:
“Remote work has fundamentally changed the calculus of where to live. When your employer is in San Francisco, but you can work from anywhere, the question is no longer ‘where are the jobs’ but ‘where does my salary go furthest and what kind of life can I build.'”
For a first-time buyer, working remotely could be a chance to put down roots and finally buy. Because with that kind of flexibility, you get to choose where to live and which places work best for your life and goals.
What To Weigh Before You Go
A lower cost of living is a great start. But it’s also important to consider the things a budget spreadsheet won’t show you, because a place can look like a great fit on paper and still not feel like home.
-
Is the internet fast and steady enough to do your job without interruptions?
-
Will it be easy to make friends and settle into a routine once you arrive?
-
Does it have the amenities you want, like public transportation or decent takeout?
This is where a local real estate agent comes in. They can help you weigh a big move against a nearby one, because every state has more affordable pockets. Sometimes they’re closer than you think.
An agent will know which neighborhoods fit your budget and have the features you’re after, whether that’s walkability, good restaurants, parks, or a nearby farmer’s market.
Bottom Line
With remote work, where you live can be your decision instead of your employer’s. And that puts more affordable places within reach.
Want to explore where that could take you? Connect with a local real estate agent to see what’s possible.

The Best Time To Buy a Home in 2026 Is Almost Here

Selling This Fall? You Haven’t Missed Your Window

Data Centers Are Moving Closer to Homes. What Does That Mean for You?


-
 Downsize4 weeks ago
One Number Could Change Everything About Your Next Move
-

 For Buyers3 weeks ago
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
-
 For Buyers4 weeks ago
Higher Rates Could Actually Help Housing Supply – Here’s How.
-
 Agent Value3 weeks ago
Most Home Sales Close – Here’s How To Keep Yours on Track
-
 Affordability3 weeks ago
Sellers Are Cutting Prices To Meet Buyers Where They’re At
-
 Affordability2 weeks ago
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
-
 Affordability2 weeks ago
Why Buyers Shouldn’t Overlook a Fall Move
-
 Affordability1 week ago
Remote Work Could Be Your Affordability Answer
You must be logged in to post a comment Login