First-Time Buyers
Builders Are Building Smaller Homes
There’s no arguing it, affordability is still tight. And if you’re trying to buy a home, that may mean you need to look at smaller houses to find one that’s still in your budget. But there is a silver lining: builders are focused on building these smaller homes right now and they’re offering incentives. And that can help give you more options that fit the bill.
Newly Built Homes Are Trending Smaller
During the pandemic, homebuyers wanted (and could afford) larger homes – and builders delivered. They focused on homes that were bigger, so people had more space for things like working from home, having a home gym, bonus rooms for virtual school, and more.
But with the affordability challenges buyers are facing today, builders are increasingly shifting their attention to bringing smaller single-family homes to the market. The graph below uses data from the Census to show how this trend has evolved over the last few years:
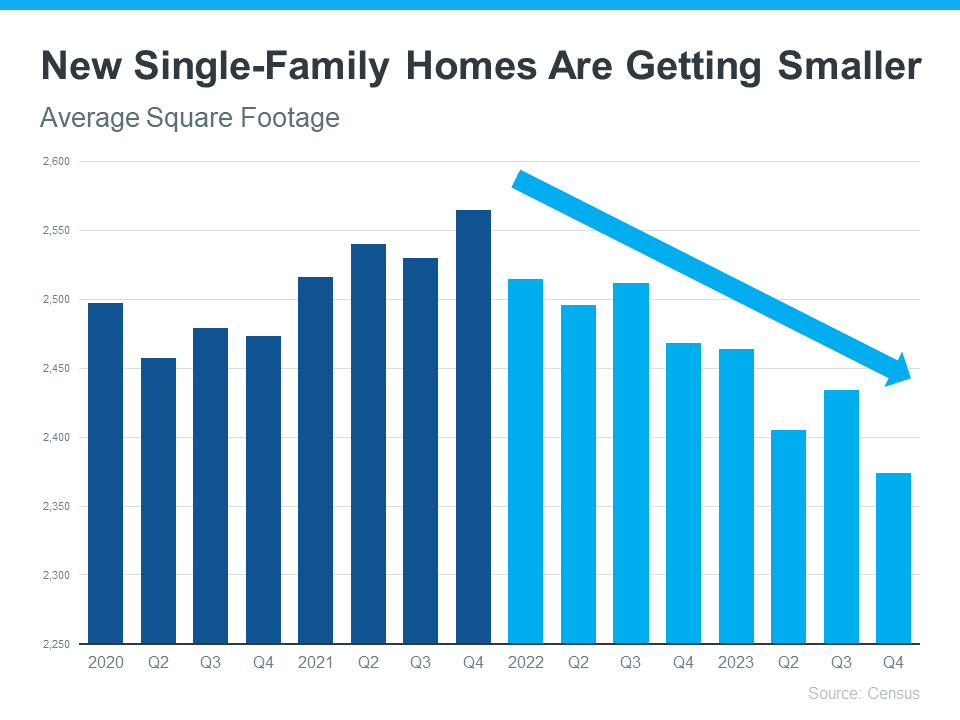
So, why the shift to less square footage? It’s simple. Builders want to build what they know will sell. Basically, they focus on where the demand is strongest. And once mortgage rates started climbing and consumers felt the challenges of affordability creeping in, it became clear there was (and is) a very real need for smaller homes. As the National Association of Home Builders (NAHB) explains:
“After a brief increase during the post-covid building boom, home size is trending lower and will likely continue to do so as housing affordability remains constrained.”
A recent article in the Real Deal says this about how this helps buyers:
“Even a slightly smaller home can be thousands of dollars cheaper — for both builders and buyers. . . In response to affordability challenges, major homebuilders are shifting priorities away from the big ticket homes and towards the cheaper set.”
What This Means for You
If you’re having a hard time finding something in your budget, it may help to look at smaller homes. And, if you consider new builds specifically, you may find a few other fringe benefits that can help on the affordability front – like price reductions or mortgage rate buy-downs. As NAHB says:
“More than one-third of builders cut home prices in 2023. NAHB expects builders to continue offering smaller homes and more affordable designs as housing affordability remains a barrier to homeownership.”
As Charlie Bilello, Chief Market Strategist, at Creative Planning, explains:
“Homebuilders are adapting to the lowest affordability on record by building smaller homes and offering more incentives/price cuts. The median square footage of a new single-family home in the US has moved down to its lowest level since 2010.”
If you explore these options, you’ll also get brand new everything, enjoy a house with fewer maintenance needs, and some of the latest features available. That’s worth looking into, right?
Bottom Line
Builders building smaller homes can give you more affordable options at a time when you really need it. If you’re hoping to buy a home soon, partner with a local real estate agent to find out what’s available in your area.
Here’s something most homebuyers don’t think about. When the housing market slows down, homeowners and builders don’t always respond the same way.
Think about it. If you’re selling your house and aren’t getting the offers you want, you could make the choice to take it off the market and stay put, and wait for things to improve.
But builders? They may be more motivated to stay the course.
They’ve already invested money in building those houses. And every completed home that sits unsold means money tied up in a property, plus ongoing costs that can add up.
That’s why some builders may be more motivated to negotiate right now. And that could work in your favor.
Fewer Buyers Are Making Moves. And Builders Are Feeling It.
You’ve probably seen the headlines. According to the latest report from the National Association of Realtors (NAR), pending home sales – homes that have gone under contract but haven’t closed yet – fell 7.3% in September and 11.3% compared to last year.
Why? Higher mortgage rates are making it harder for buyers to make the numbers work. Now, that report tracks existing homes, not new construction. But we’re seeing signs of the same slowdown on the builder side, too.
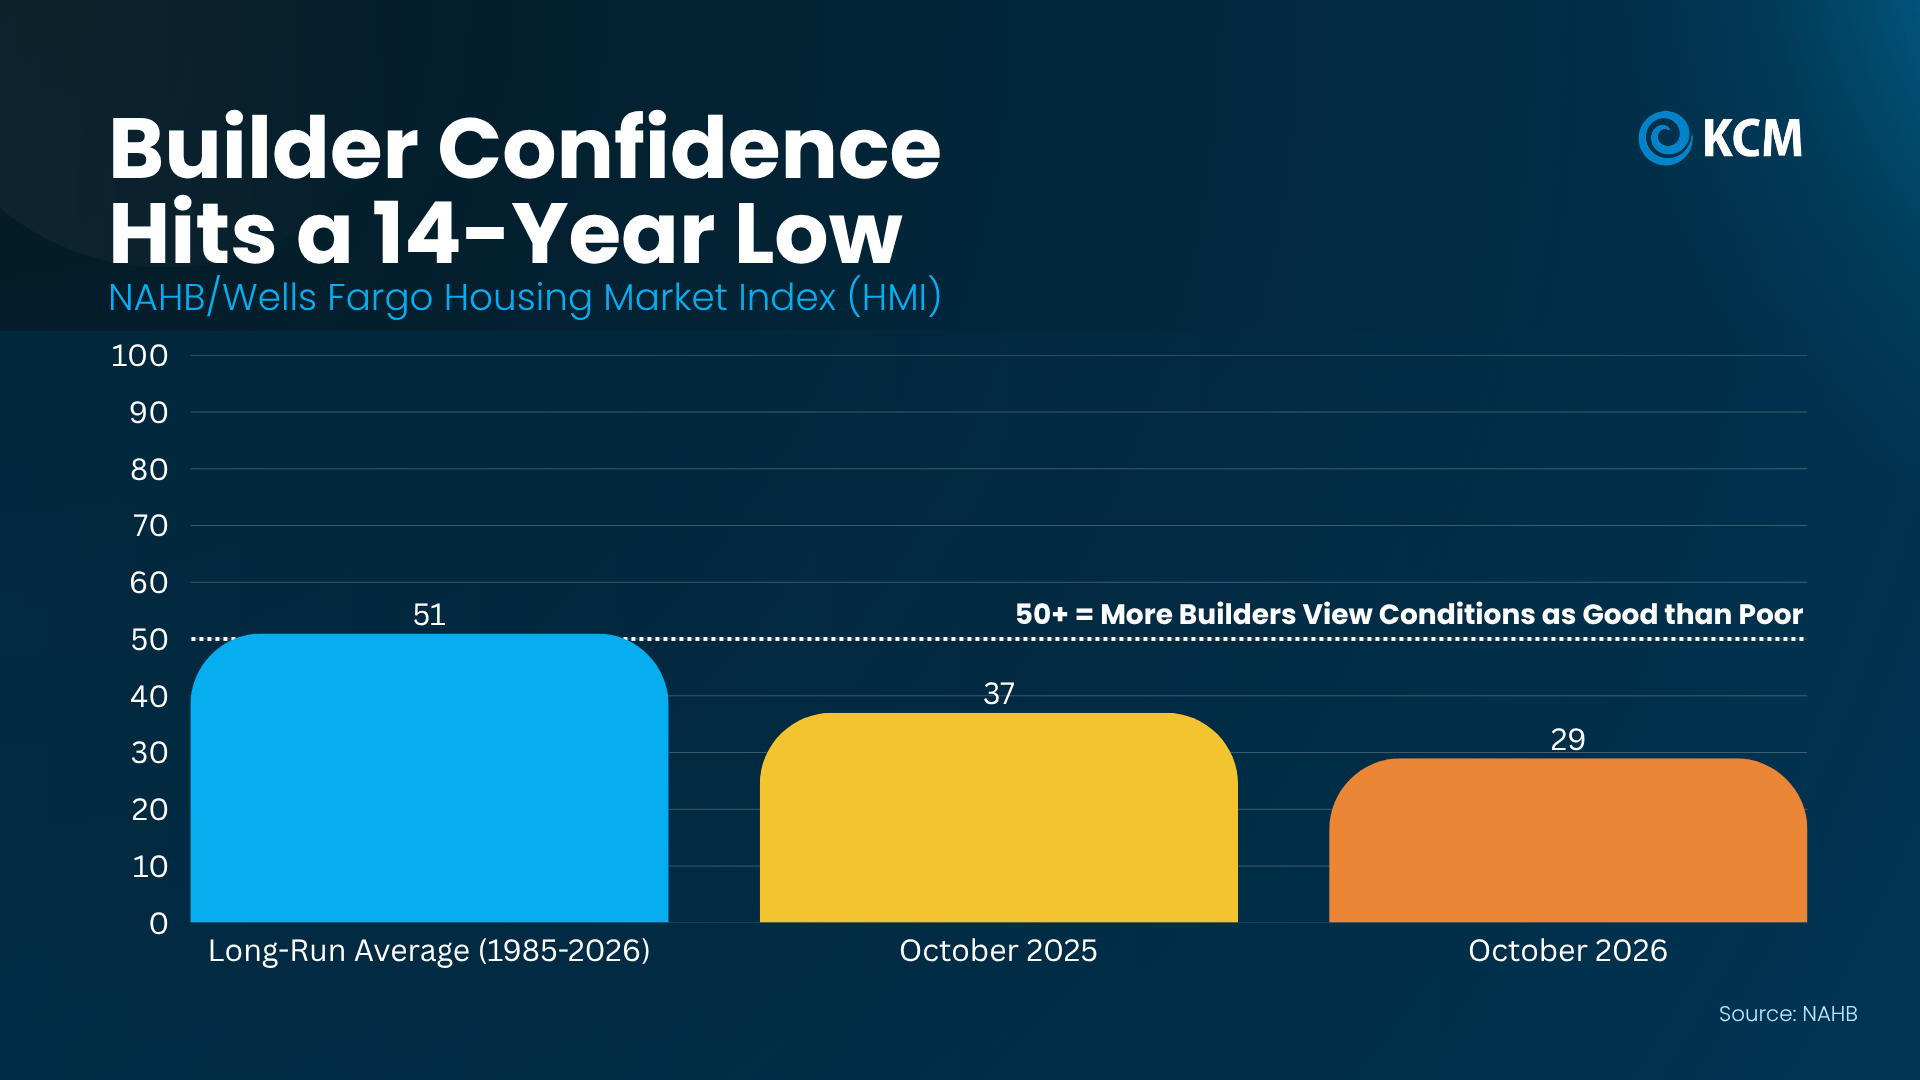
According to the National Association of Home Builders (NAHB), builder confidence dropped to 29 in October, its lowest level since June 2012. Traffic from prospective buyers also dropped to its lowest level in more than a decade, excluding the start of the pandemic.
As Robert Dietz, Chief Economist at NAHB, explains:
“Demand persists, but higher mortgage rates, elevated construction costs and weaker consumer confidence are keeping more buyers on the sidelines.”
Here’s why that matters for you.
A homeowner may be able to wait for the right offer. But a builder with several finished houses sitting unsold may have more reason to get those homes sold sooner rather than later.
And that means they may be more willing to work with you than you think.
Builders Are Already Making Moves To Win Buyers Over
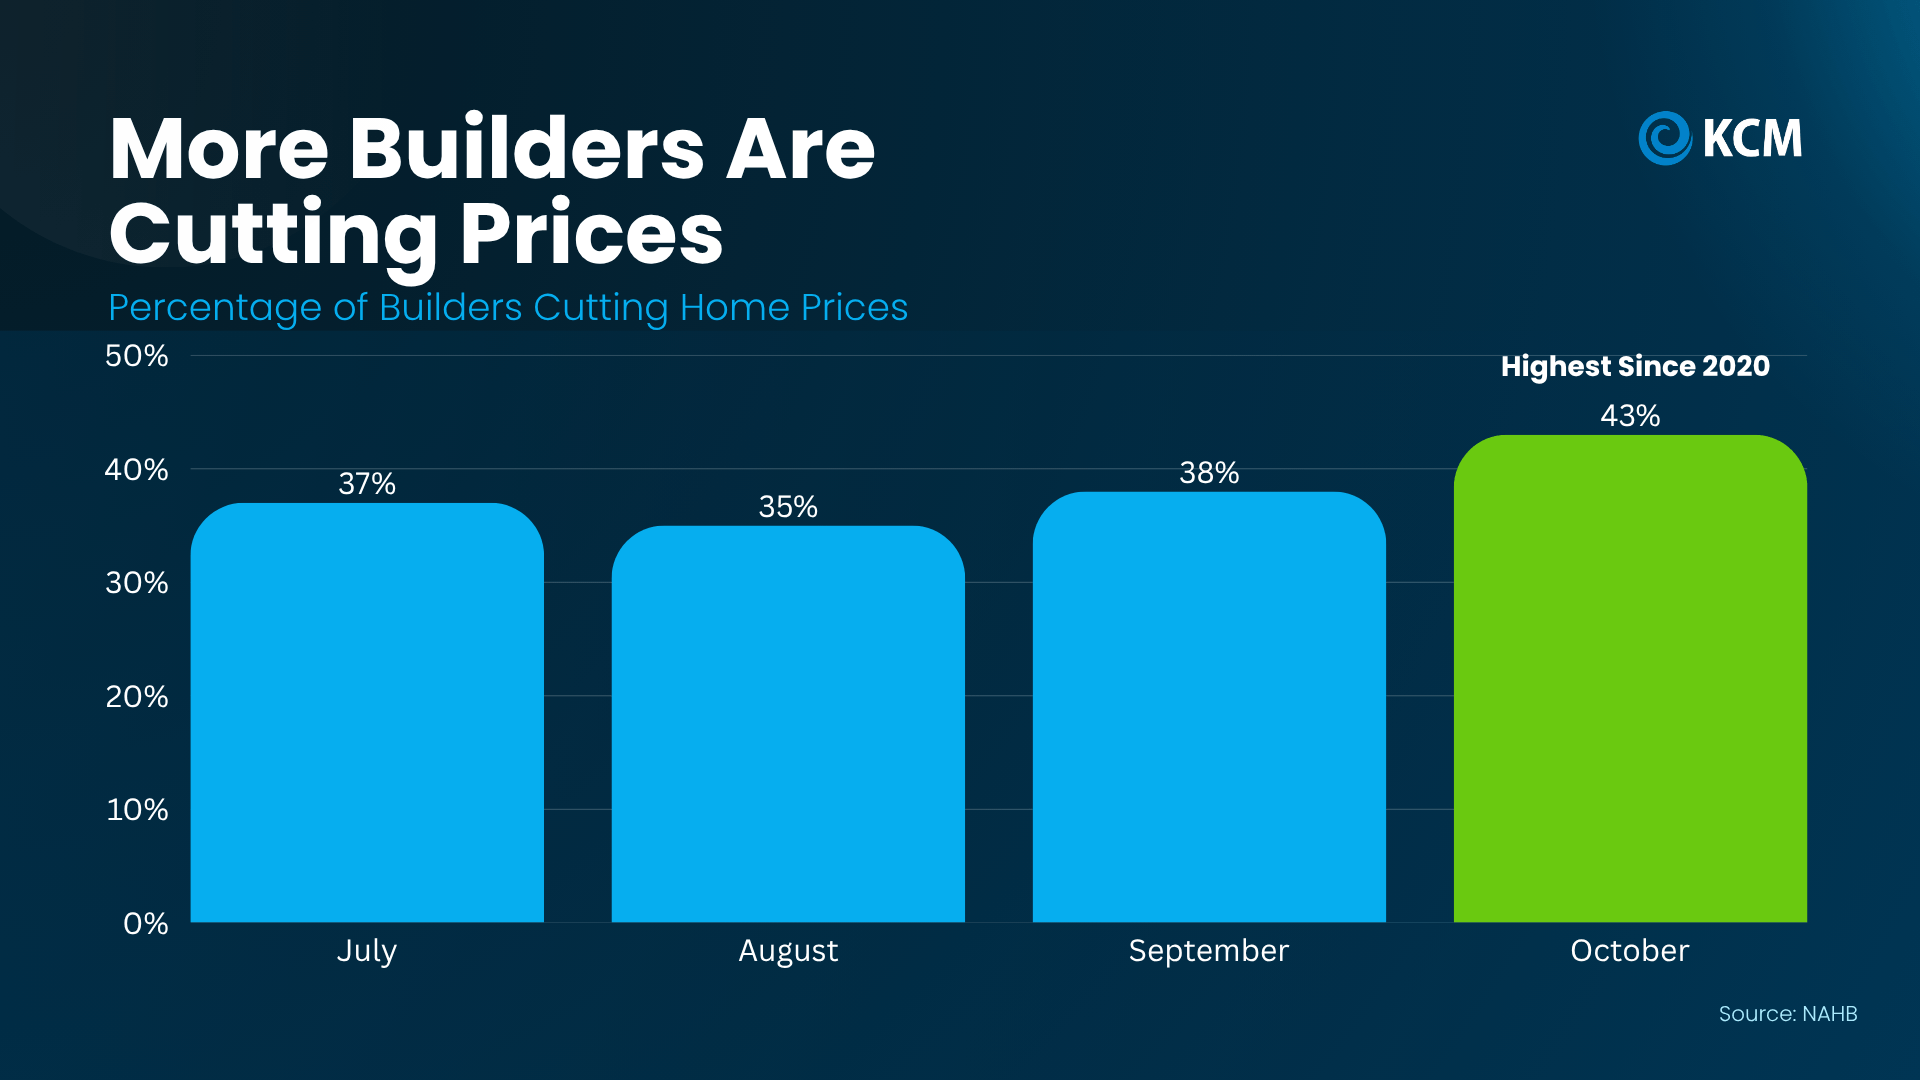
If you’ve always assumed builders don’t negotiate, take a look at what they’re actually doing. According to the latest survey from NAHB, in October:
-
65% of builders are offering sales incentives.
-
43% are cutting prices, the highest share recorded between 2020 and 2026.
-
And 6% is what they’re typically taking off the price.
So, yes. Builders absolutely do negotiate. And with demand slowing, there’s good reason to explore just how flexible they may be right now.
That could mean asking for a lower price. But it could also mean asking for a mortgage-rate buydown, help with closing costs, or upgrades that would otherwise cost you extra.
And here’s a tip that could make a real difference.
Don’t just look at the newest communities or the prettiest model homes. Look for builders with completed houses that haven’t sold yet.
Those are sometimes called quick move-in homes or spec homes. And the longer one of those move-in ready homes sits unsold, the more reason a builder may have to consider an offer that helps get it off their books.
Don’t Just Ask What’s Available. Ask What’s Negotiable.
Don’t assume the advertised price or incentive package is the best they’ll do.
This is where having your own agent can really pay off. An agent who knows the local market can help you compare what builders are offering, identify communities with more available homes, and understand where there’s room to negotiate.
Of course, not every builder will offer the same incentives. And some may be more flexible on closing costs or mortgage rates than on the price itself.
But that’s exactly why it pays to ask.
The trick is knowing where to look, what to ask for, and how much room there may be to negotiate. And that’s where having your own agent is key.
Bottom Line
A homeowner who isn’t ready to accept a lower offer may be able to wait. But a builder with finished houses to sell has a different set of priorities. And that could work in your favor.
If you’re ready to buy, talk to a local agent about which builders have completed homes sitting on the market in your area see what they’re willing to offer to get them sold.
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.
More and more of them are finding it in the adjustable-rate mortgage, or ARM.
The ARM Option
Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.
Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity.
Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home.
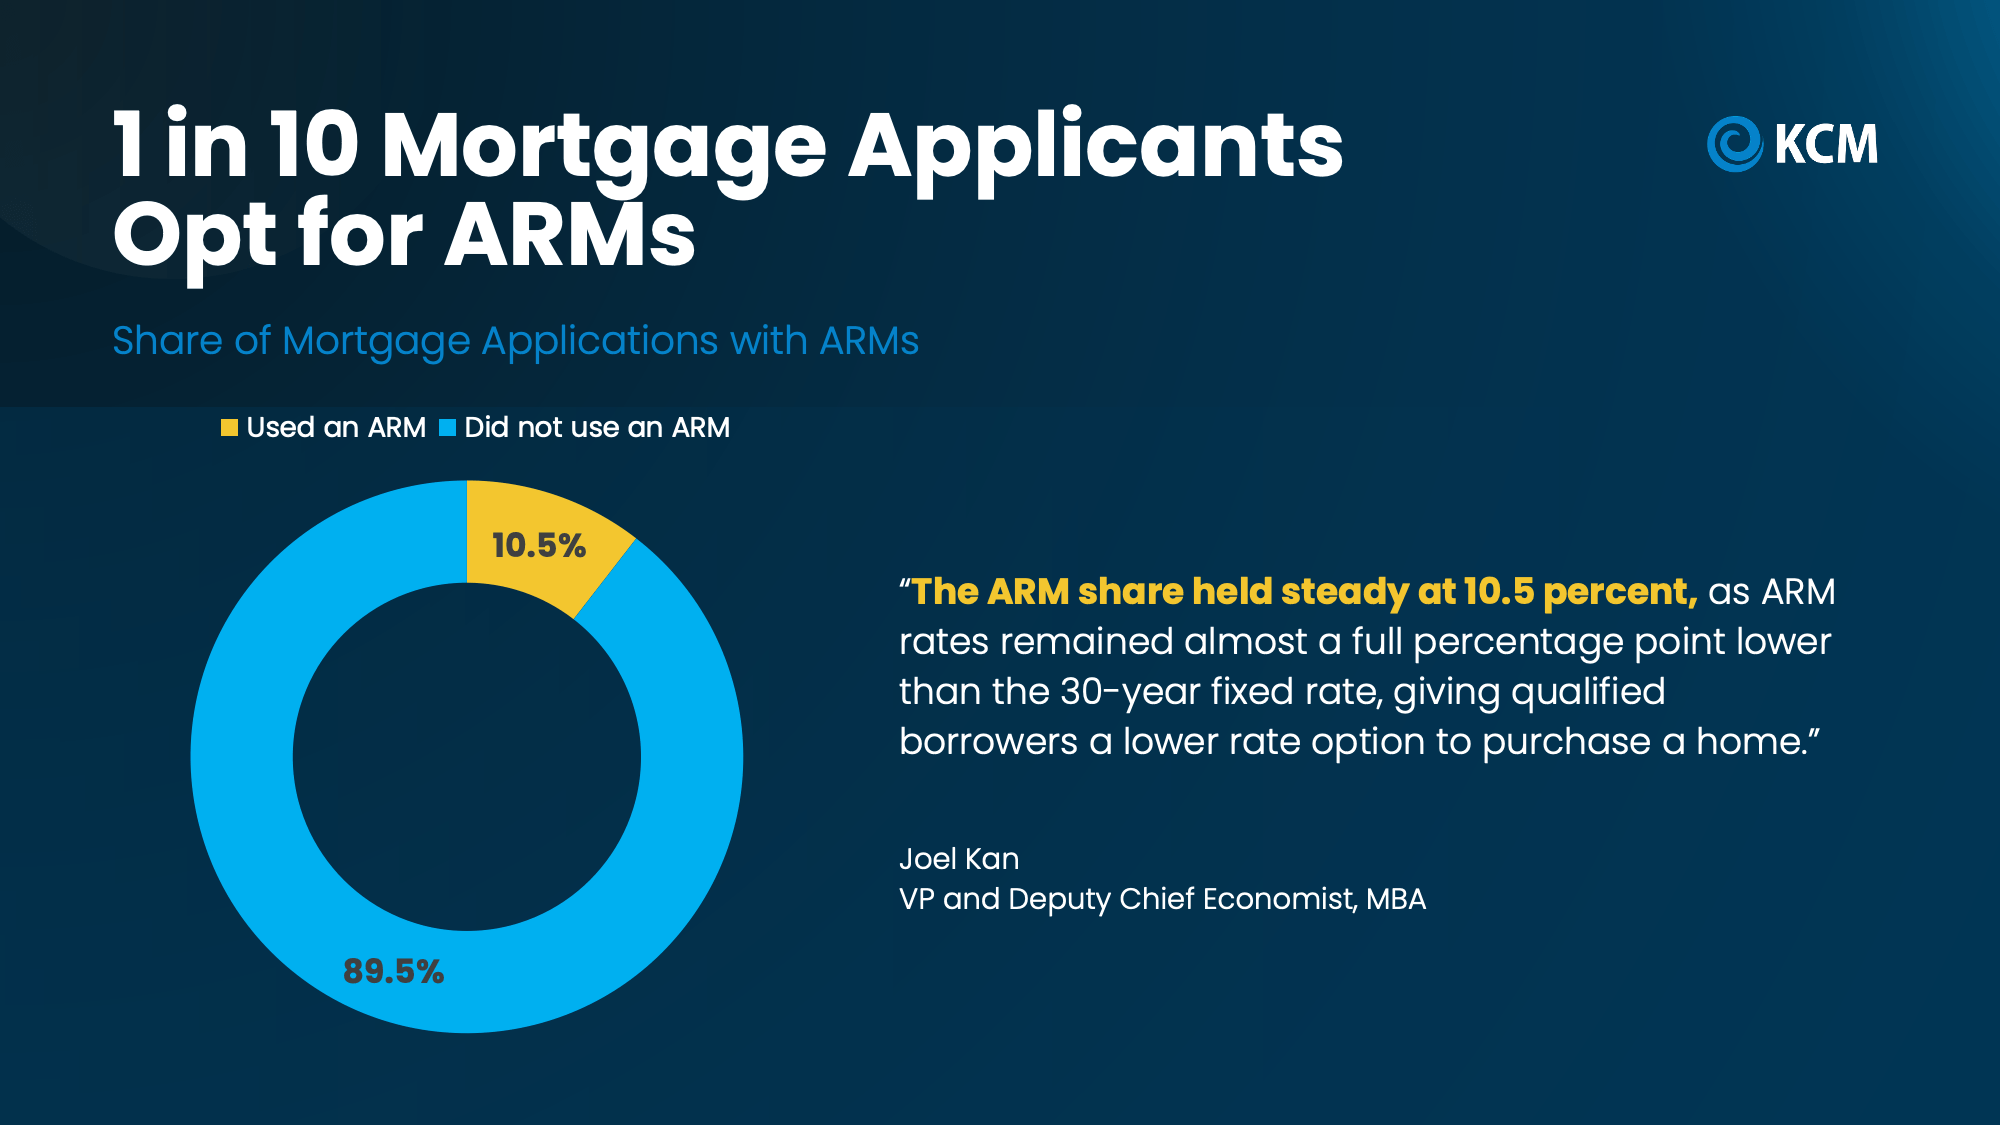
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
If you think you may want to consider this yourself, here’s what you need to know about how it works.
The 5/1 ARM
An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.
The “5” means your introductory rate is locked for the first five years, and the “1” means that the rate can change every year after that. The rate change is called the “reset.” And here’s the really important part.
When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready.
The Upsides and Potential Downsides
To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
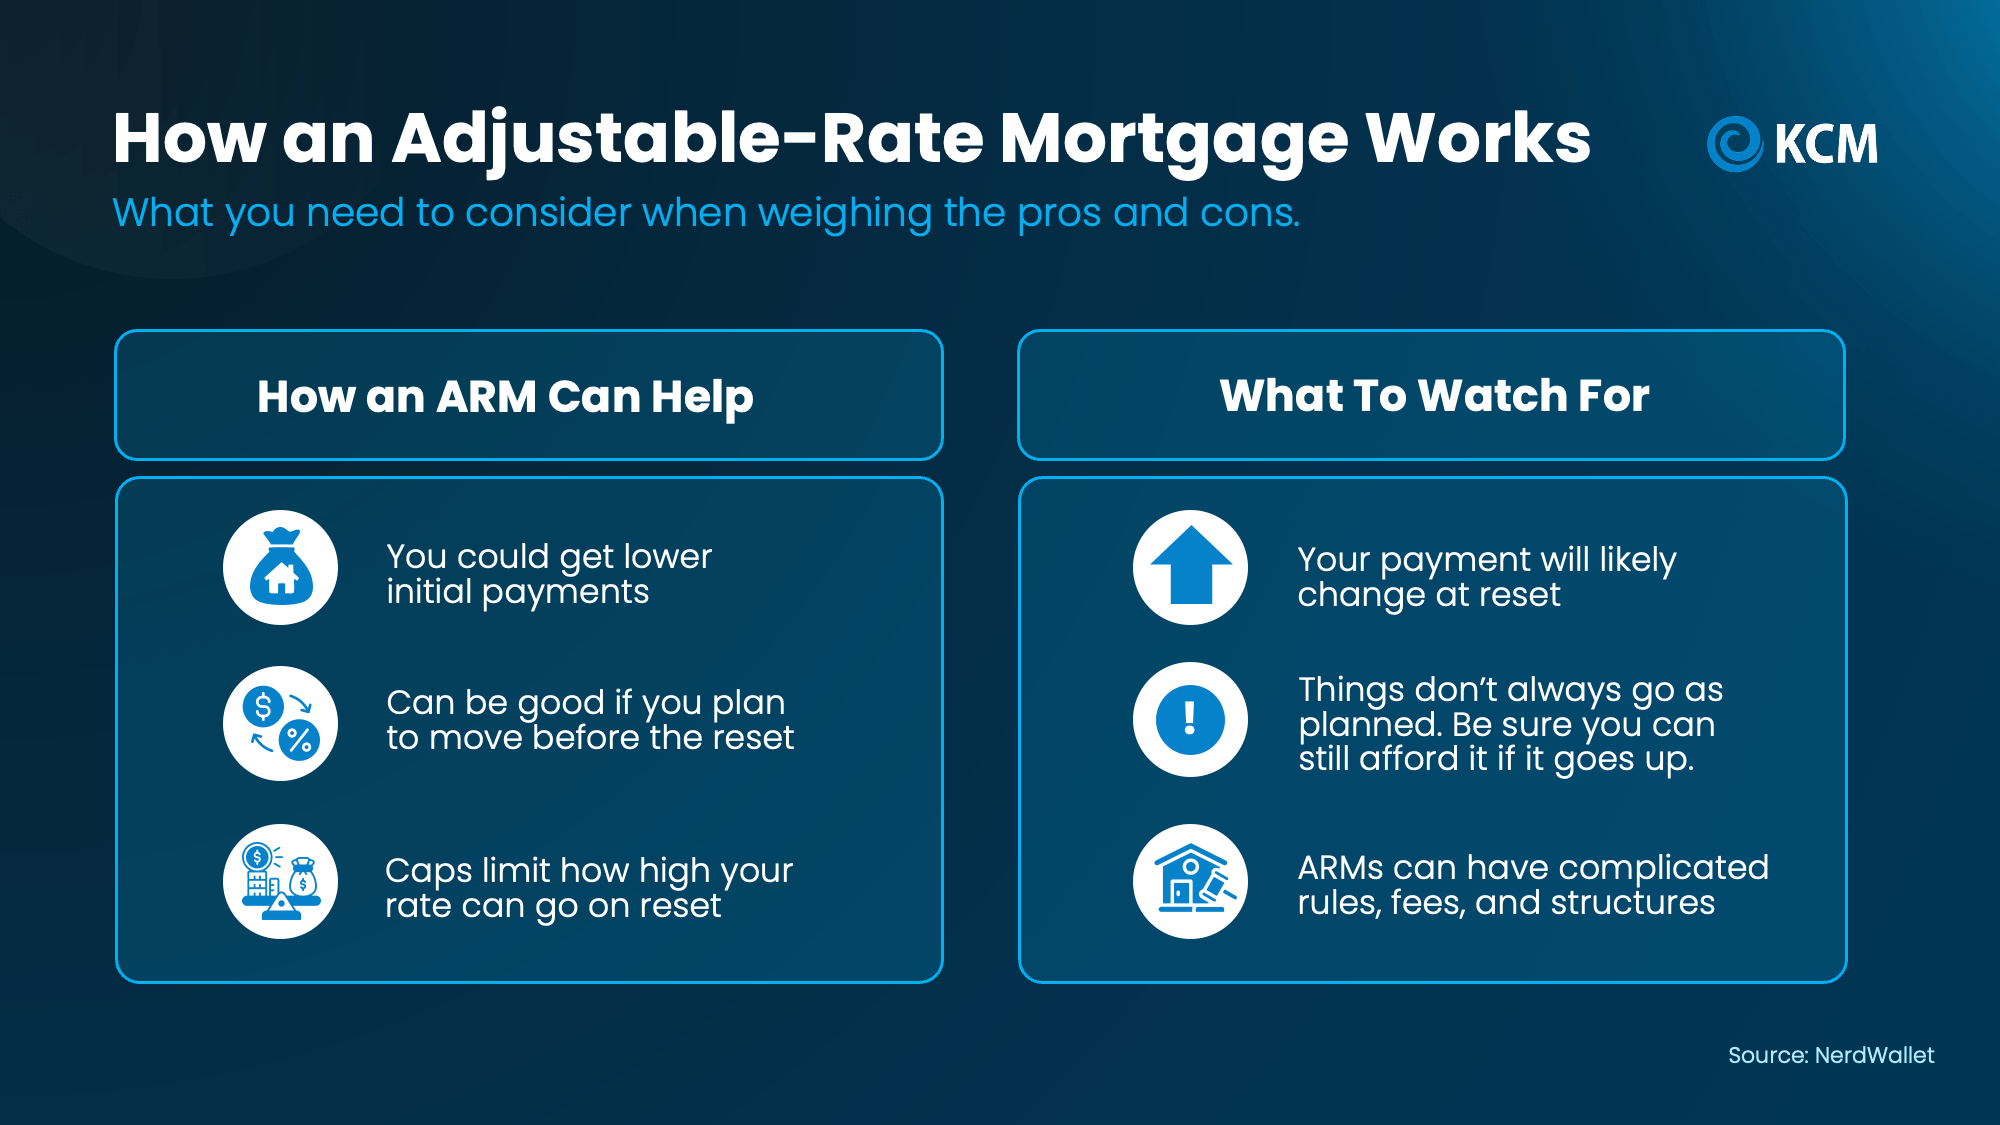
Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.
Be Ready for the Reset
And, if you do go with an adjustable-rate mortgage, just know that you’ll have choices when the reset time arrives. You could:
-
Do nothing and keep your loan in place if the new payment still fits your budget.
-
Refinance into a fixed-rate loan with a payment that never changes.
-
Refinance into another ARM with a new lower rate locked for a specified timeframe.
-
Sell your home.
-
Talk to the loan servicer about assistance or modification.
Remember, a refinance is a brand-new loan that you’ll have to qualify for – even if it’s on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It’s important to keep your credit and finances in “mortgage shape.”
Today’s ARMs Aren’t Like 2008
One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.
But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment.
So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.
Bottom Line
Today’s market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.
Is an ARM a good option for you? Talk to a loan officer to find out.
When you picture buying your first home, chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now.
So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo.
Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door.
Condos Can Cost Less Than You Think
According to a recent study by Zillow:
“Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home.”
And depending on where you live, the difference can be much bigger.
Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research (see chart below).
In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area’s median household income.
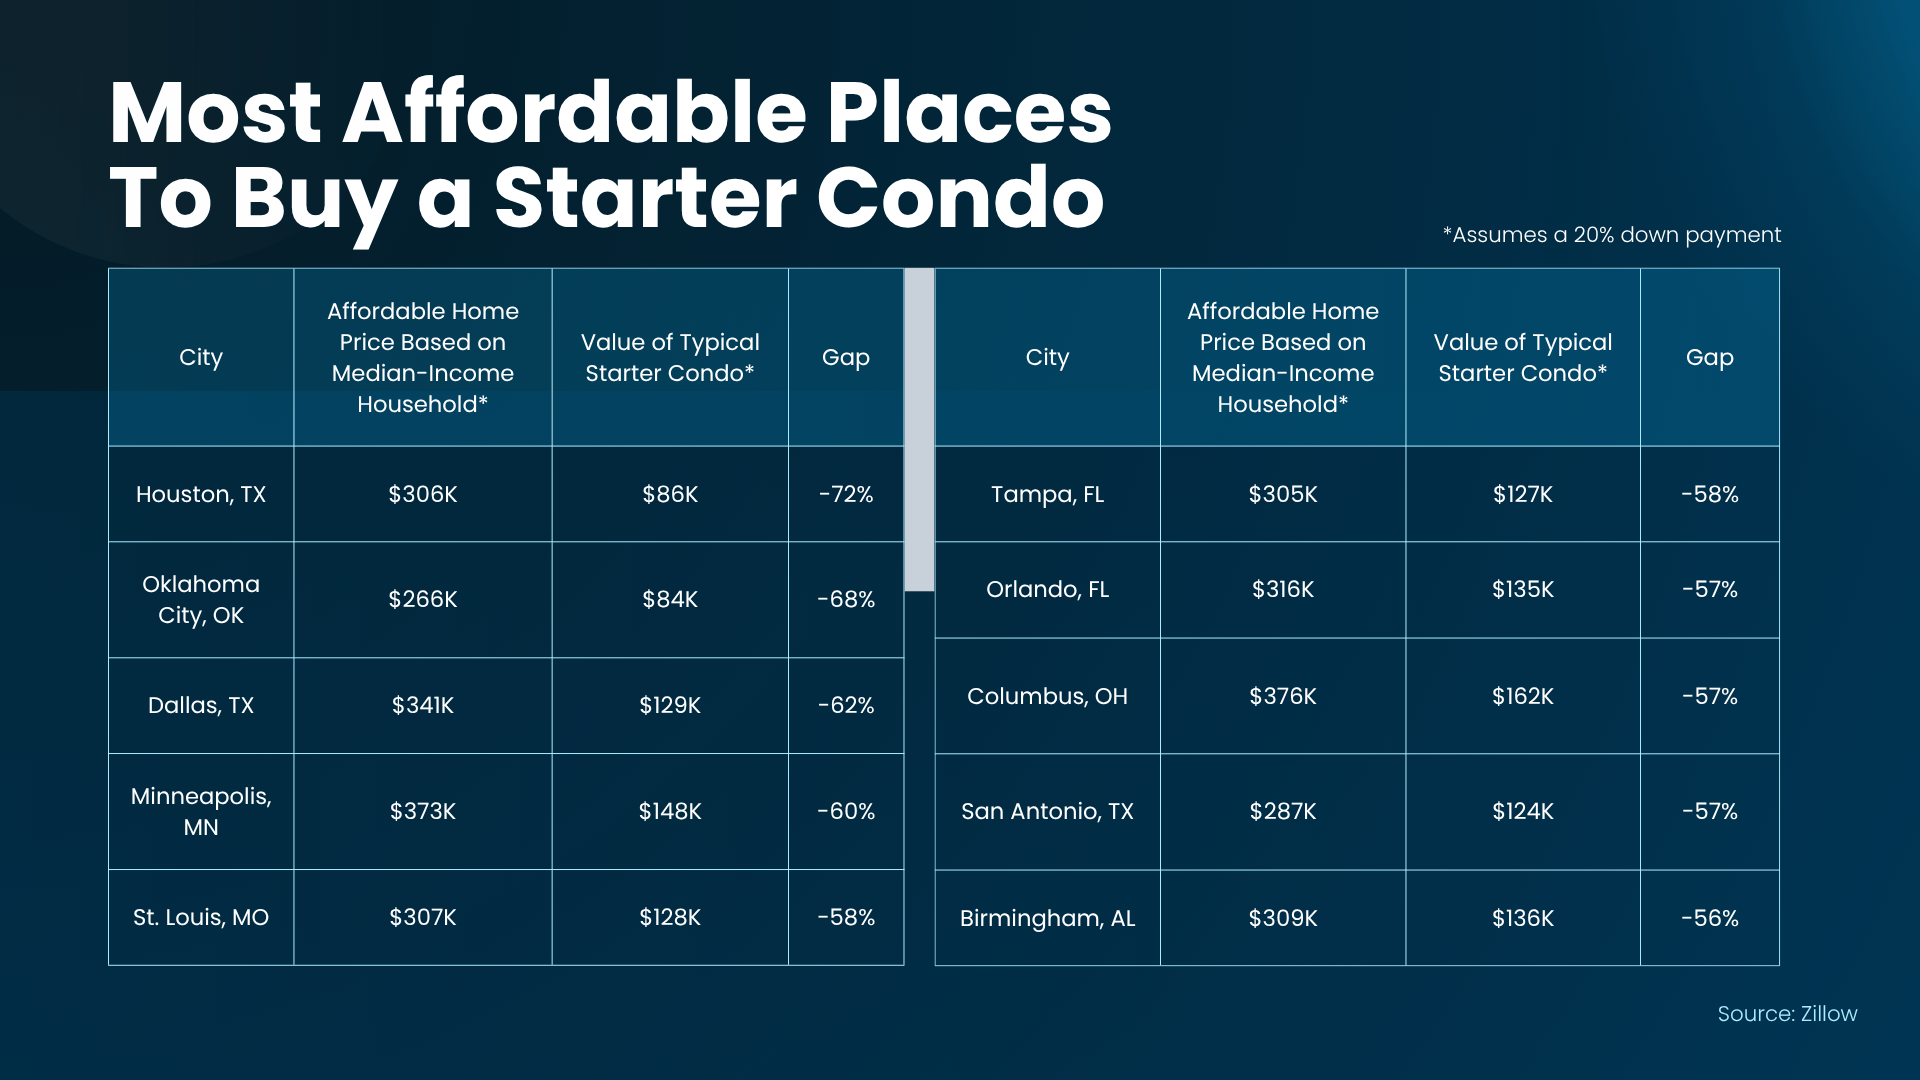
Of course, every market is different. But the bigger point is this: if you’ve only been searching for traditional single-family houses, you may be overlooking some of the more affordable options on the market.
And even if your city didn’t make this list, that’s okay. The trend holds true in many places across the country. Here’s why.
A Condo Could Give You a Different Way In
Part of the reason condos can cost less is pretty straightforward. They’re typically smaller. And less square footage can mean a lower purchase price.
So, if you can make do with a bit less space or you’re coming from a smaller apartment now, this can be a great way in. Plus, on the upside, you won’t have to buy a ton of furniture to fill out a bigger house. You can get a potentially lower price up front and spend less once you move in because you’ll need less new stuff to fill that empty space.
And more buyers are making that trade off on space to offset the current affordability challenges. Ali Wolf, Chief Economist for New Home Source, explains:
“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”
That’s really the heart of it. Looking at condos isn’t necessarily about wanting less. It’s about finding another way to make your move happen with the budget you have.
Don’t Rule Out an Option That Could Work
If you’ve been struggling to find a house you like at a price you can comfortably afford, talk to your agent about adding condos to your search.
You may find something in a neighborhood you thought was outside your budget. You could get access to amenities you wouldn’t otherwise have. And you may be able to become a homeowner sooner rather than waiting for the numbers on a single-family house to work.
While there are trade-offs like shared walls, less outdoor space, and an HOA fee to factor into your monthly budget, maybe that’s worth it if you finally get your own set of keys.
Plus, a lot of the times, a condo community comes with great amenities like pools, gyms, and the condo association handles at least some of the maintenance. Which is closer to what you’re used to from your apartment – it could make the transition to homeowner not just more affordable, but that much easier too.
Bottom Line
The first home you buy doesn’t have to be a single-family house. If affordability has been holding you back, talk to a local agent about expanding your search and see whether a condo could fit the price point you’re looking for.

Why Builders May Be More Motivated To Sell Than Homeowners

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today

To Sell or Rent? How To Choose the Best Path for Your House.


-
 Buying Tips4 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 For Sellers4 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability4 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Downsize3 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
-
 Affordability3 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Affordability3 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Affordability2 weeks ago
Why Most People Are Still Glad They Bought a Home
-
 Buying Tips1 week ago
The Biggest Credit Hurdle for Renters Who Want To Buy
You must be logged in to post a comment Login