Rent vs. Buy
The Perks of Buying over Renting
Thinking about buying a home? While today’s mortgage rates might seem a bit intimidating, here are two solid reasons why, if you’re ready and able, it could still be a smart move to get your own place.
1. Home Values Typically Go Up Over Time
There’s been some confusion over the past year or so about which way home prices are headed. Make no mistake, nationally they’re still going up. In fact, over the long-term, home prices almost always go up (see graph below):

Using data from the Federal Reserve (the Fed), you can see the overall trend is home prices have climbed steadily for the past 60 years. There was an exception during the 2008 housing crash when prices didn’t follow the normal pattern, but generally, home values kept rising.
This is a big reason why buying a home can be better than renting. As prices go up and you pay down your mortgage, you build equity. Over time, this growing equity can really increase your net worth. The Urban Institute says:
“Homeownership is critical for wealth building and financial stability.”
2. Rent Keeps Rising in the Long Run
Here’s another reason you may want to think about buying a home instead of renting – rent just keeps going up over the years. Sure, it might be cheaper to rent right now in some areas, but every time you renew your lease or sign a new one, you’re likely to feel the squeeze of your rent getting higher. According to data from iProperty Management, rent has been going up pretty consistently for the last 60 years, too (see graph below):
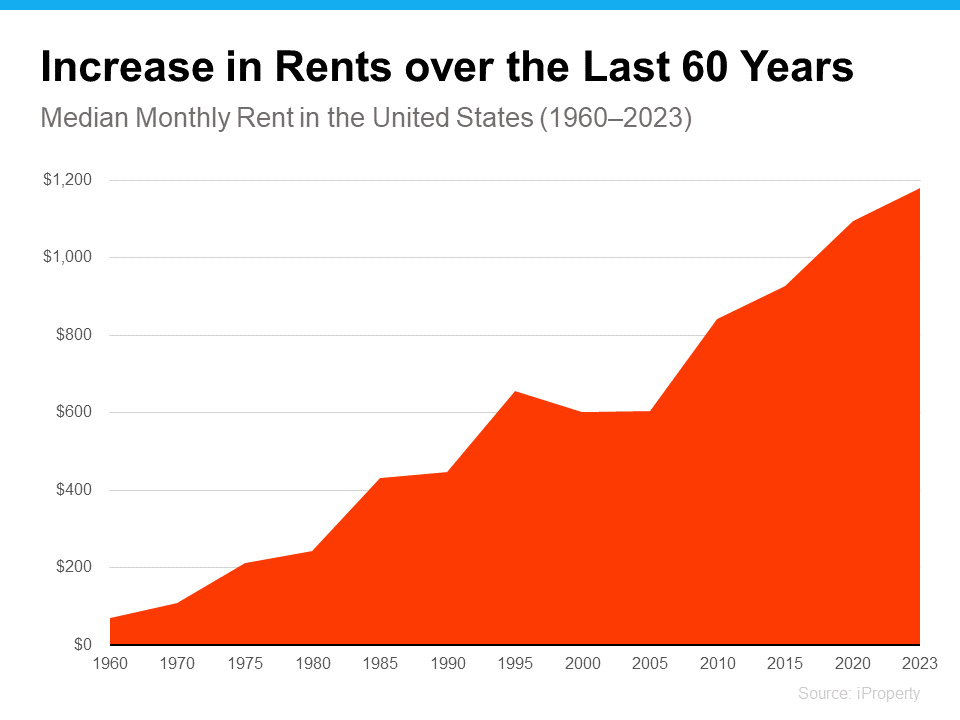
So how do you escape the cycle of rising rents? Buying a home with a fixed-rate mortgage helps you stabilize your housing costs and say goodbye to those annoying rent increases. That kind of stability is a big deal.
Your housing payments are like an investment, and you’ve got a decision to make. Do you want to invest in yourself or keep paying your landlord?
When you own your home, you’re investing in your own future. And even when renting is cheaper, that money you pay every month is gone for good.
As Dr. Jessica Lautz, Deputy Chief Economist and VP of Research at the National Association of Realtors (NAR), says:
“If a homebuyer is financially stable, able to manage monthly mortgage costs and can handle the associated household maintenance expenses, then it makes sense to purchase a home.”
Bottom Line
If you’re tired of your rent going up and want to explore the many benefits of homeownership, talk to a local real estate agent to explore your options.
For a lot of first-time buyers, owning a home can feel perpetually a few years out of reach. Saving for a down payment takes time, and each year you spend renting can make owning feel further off.
But buying your first home doesn’t have to happen to feel like a far away goal. Two choices you control can bring your first home years closer, even with affordability as tight as it is right now.
How Long Buying Really Takes
First, one quick definition. “Breaking even” is the point where owning has cost you about the same as renting would have over the same period. And after that point, owning starts to cost less than renting. Kara Ng, Senior Economist at Zillow, puts it this way:
“Buyers should think about not just when they can afford to buy, but how long they’d need to stay before owning makes more financial sense than renting.“
So how long does reaching that point usually take? And what are the shortcuts? Let’s do the math.
According to Zillow, it usually takes about 8.5 years to save for a 20% down payment, then roughly 6.2 more years before owning costs the same as renting. Together, that’s just under 15 years. But that math relies on two assumptions: that you’re buying a mid-priced home, and that you’re putting 20% down.
Change either one and your timeline gets shorter. Change both and it can shrink fast. It also varies widely by market, since local prices and rents are different depending on where you live.
A Starter Home Can Get You There Twice as Fast
A starter home usually means a home in the lower third of local prices. They’re often condos, townhomes, or single-family homes a little smaller or older than others in the area.
Choosing one over a mid-priced home can cut your wait down by a lot. And while that might sound obvious, you may not realize just how much it shortens your timeline. Because if you’re buying a more affordable home, you don’t have to save up as much or as long.
Zillow found that nationwide, a starter home takes half the time – about 7.2 years – to save for and come out ahead on, compared with renting (see graph below):
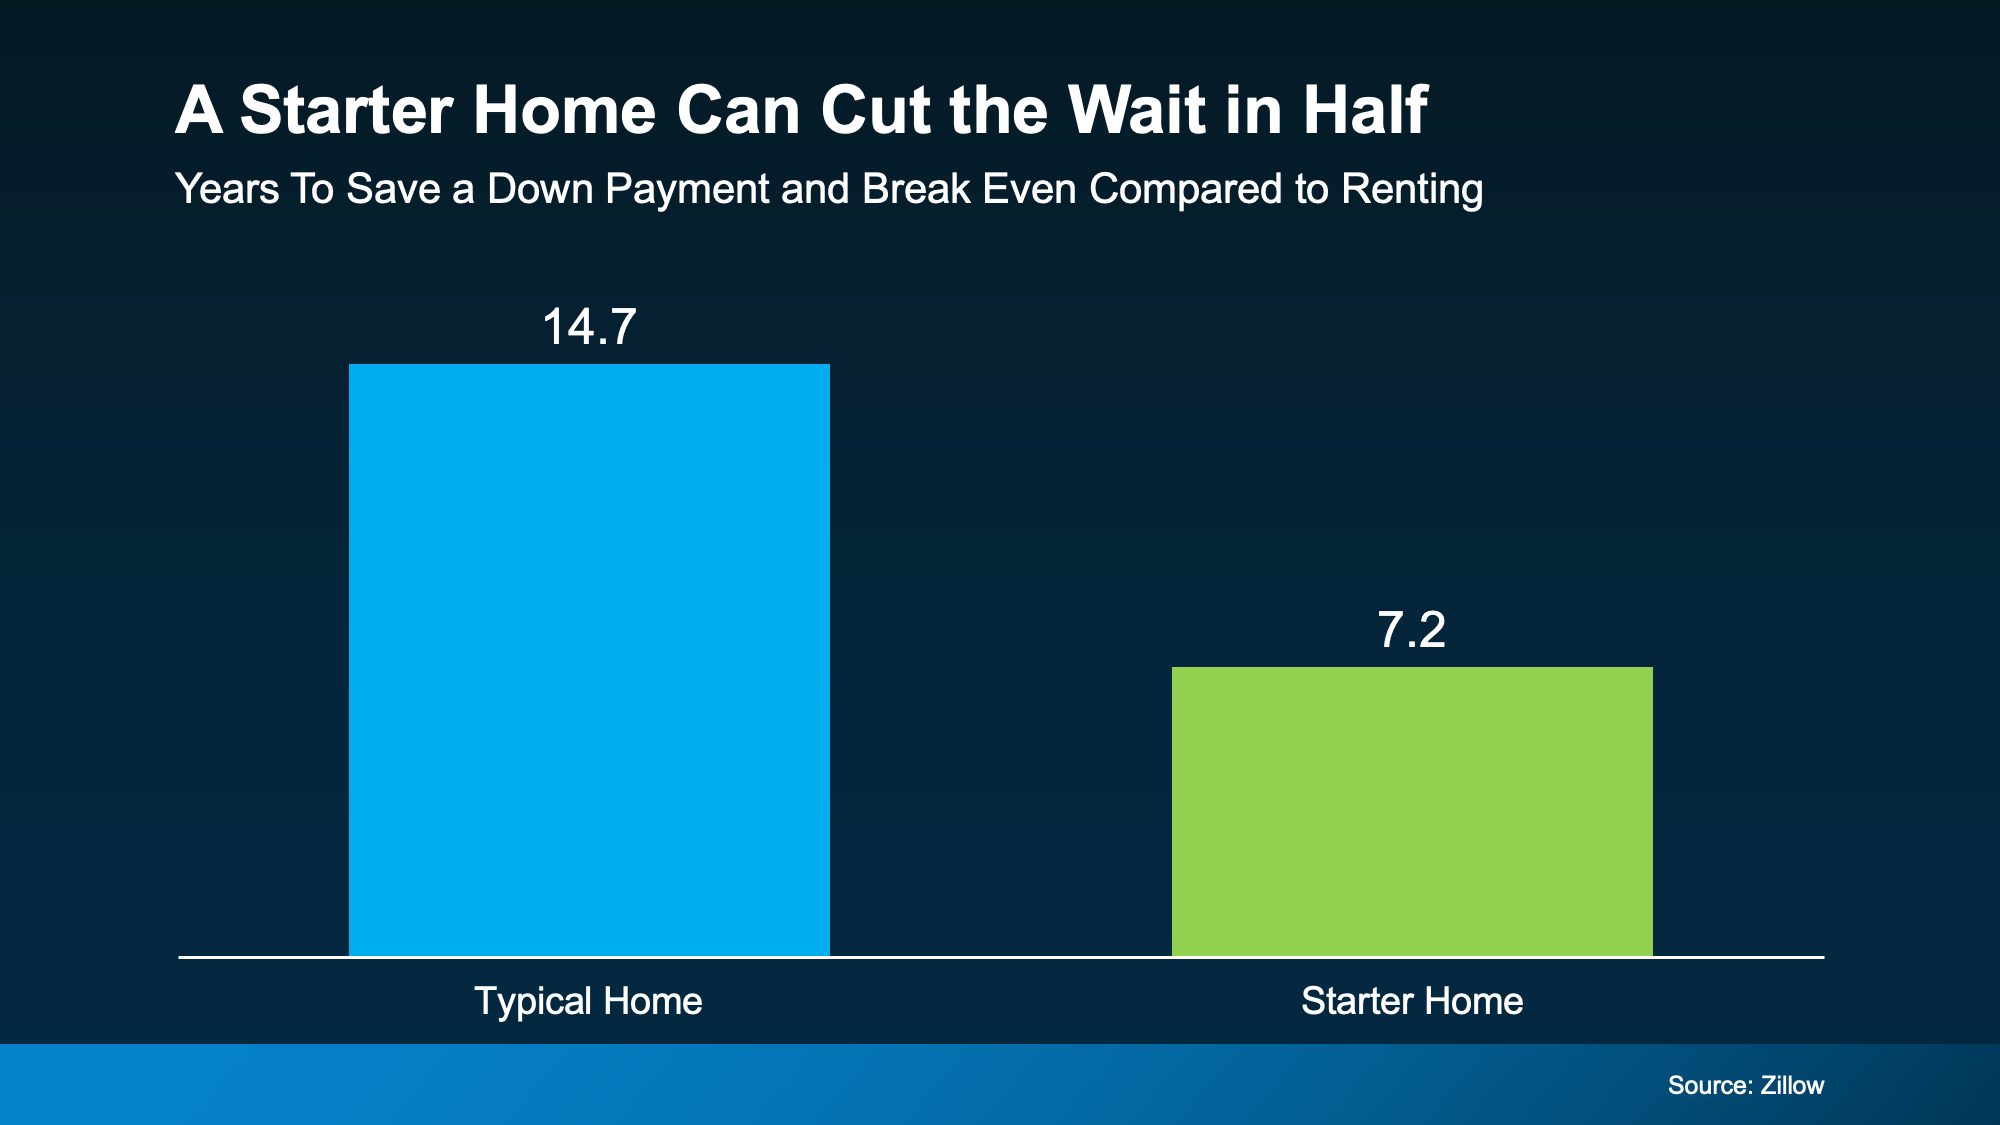
That works out to about 4.6 years to save and 2.6 years to break even. It won’t erase every affordability challenge, but it can take years off the wait. And if you’ve already been saving for a while, it could get you closer to making it a reality.
You Usually Don’t Need To Put 20% Down
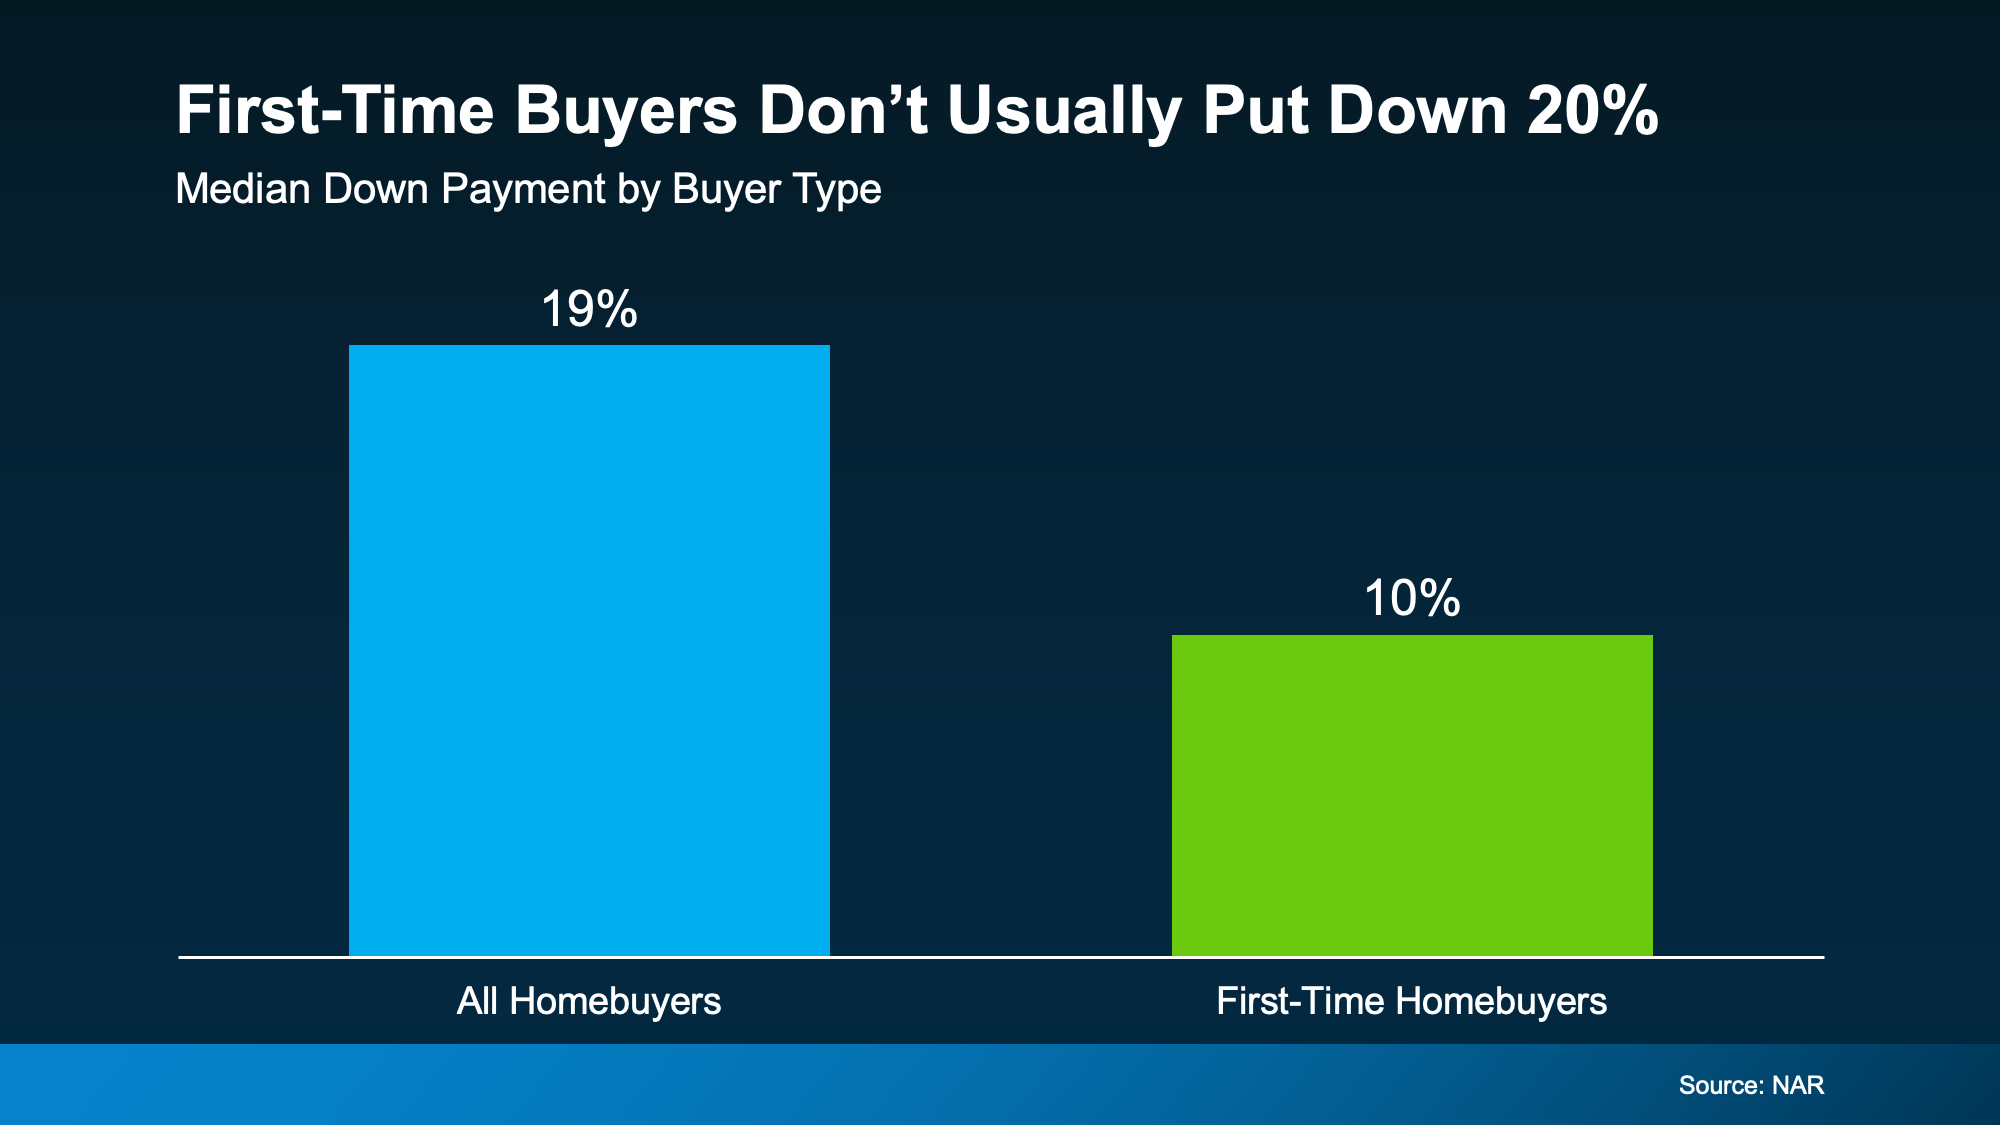
You, like many first-time homebuyers, might assume you need a 20% down payment to even consider buying. But a lot of the time, you don’t.
Most first-time buyers don’t put down anywhere near that. The National Association of Realtors shows the median down payment for first-time buyers is 10% (see graph below):
And the minimums go lower still. Some buyers put down as little as 3% on a conventional loan or 3.5% on an FHA loan, and eligible veterans or buyers in certain rural areas can put down nothing at all.
There’s help with the upfront costs of buying, too. Down Payment Resource counts 2,746 assistance programs nationwide, and some are even stackable:
“Some homebuyers can layer multiple sources of assistance to reduce their upfront costs. Layering means combining more than one eligible source of funding as part of your home purchase.”
Put those together – a lower price point, a smaller down payment, and help covering it – and the years you thought you needed start to come down.
Bottom Line
Your first home may not be as far off as it feels. When the numbers make sense for you, buying a starter home and putting down less than 20% can get you there years sooner.
Want to see which starter homes in your area could fit your budget? A local real estate agent can show you.
Quick gut reaction. Which investment do Americans trust more than stocks, gold, savings accounts, and bonds? The answer hasn’t changed in 14 years.
It’s real estate. And this year, that answer comes with even more conviction behind it. New data shows people aren’t just saying homeownership is a smart move, they’re feeling better about it than they have in years. Let’s dig into why.
Real Estate Takes the Top Spot – Again
Every year, Gallup asks Americans to name the best long-term investment. And for the 14th year in a row, real estate came out on top (see graph below):
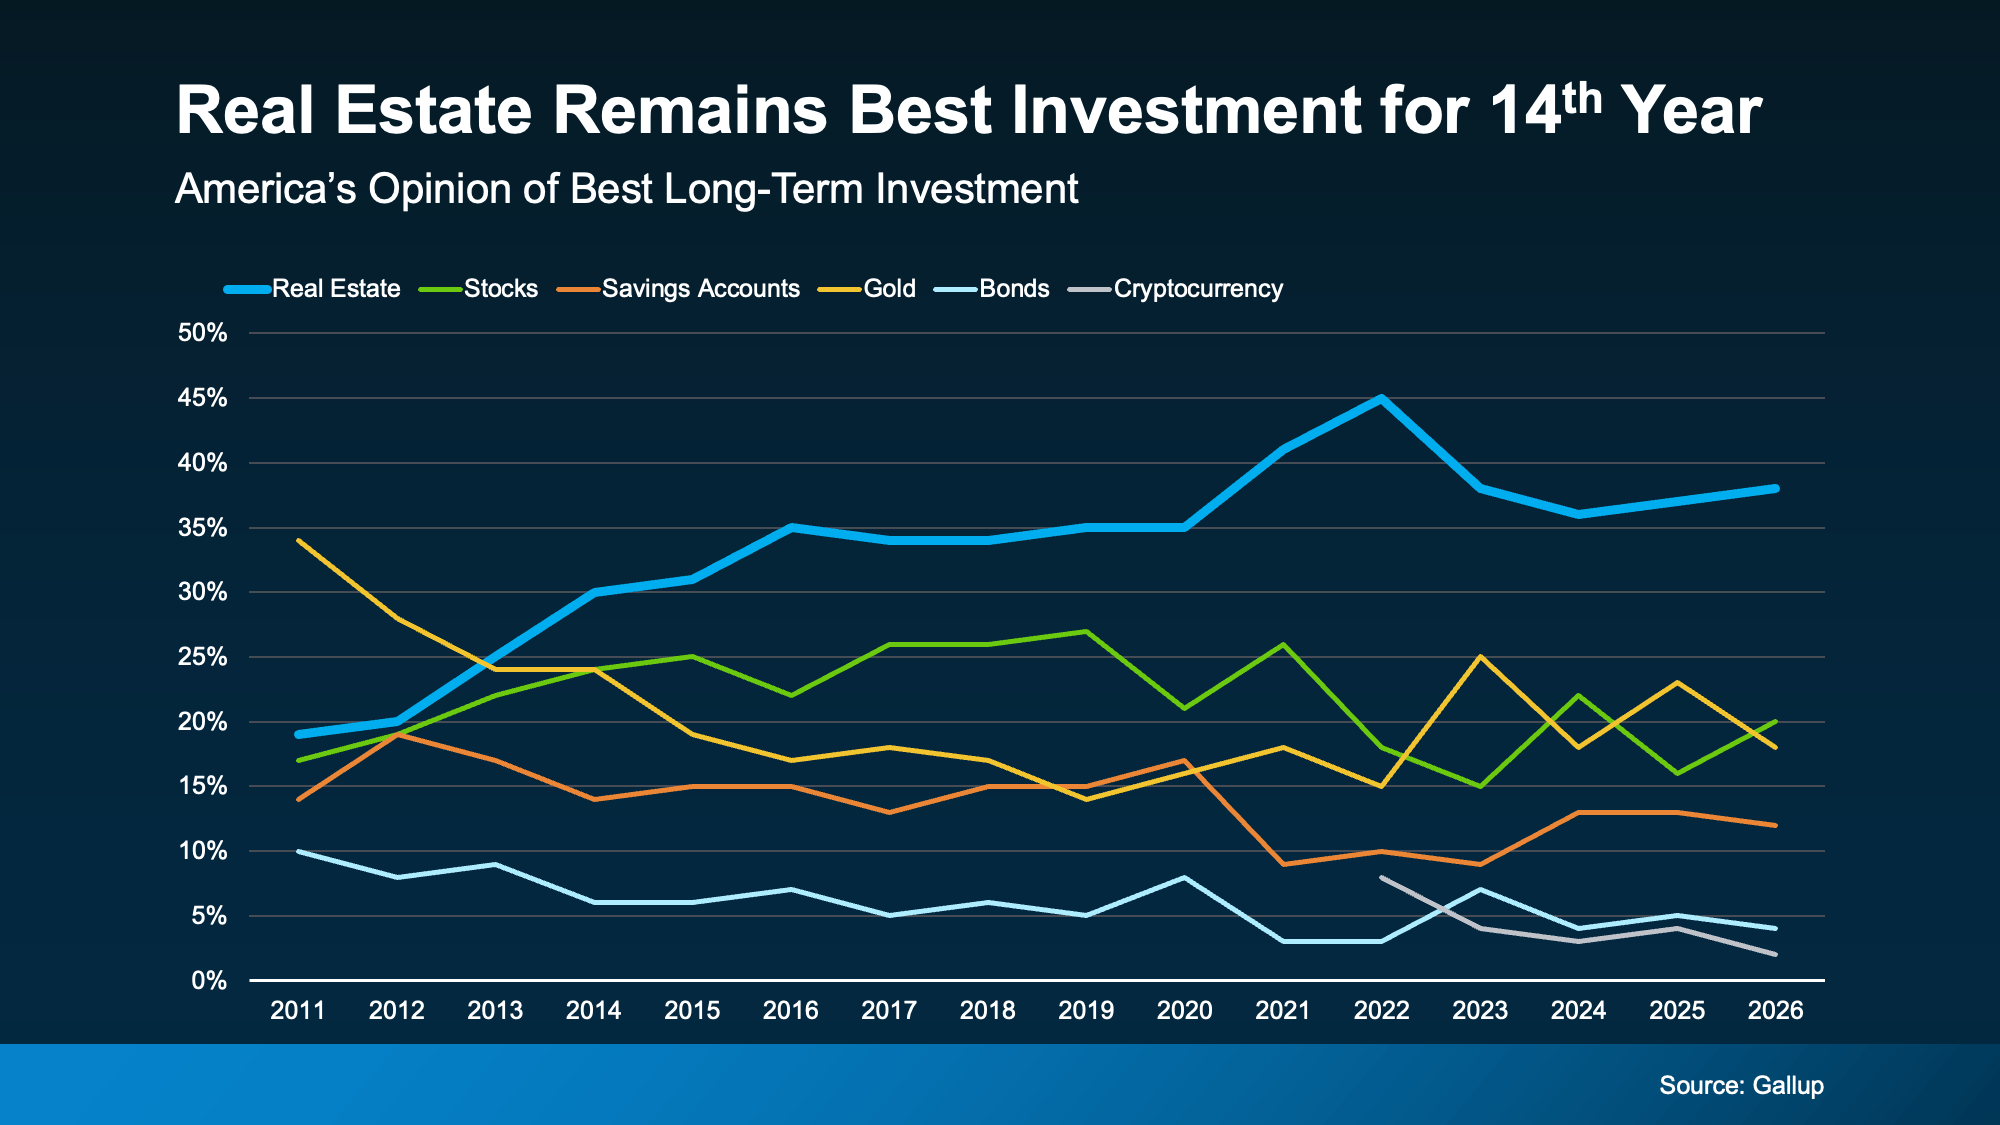
That’s not a fluke or a hot streak. That’s 14 straight years of beating out stocks, gold, and everything else.
Think about everything that’s happened in that stretch – rising rates, market swings, election years, you name it. Through all of it, Americans kept picking real estate. That kind of staying power says something about how people view homeownership – and it makes sense. Historically, it’s one of the best ways to build wealth in this country.
As Michelle Egan, Head of Credit Solutions, Impact Finance at JPMorgan Chase, explains:
“Owning a home has long been considered one of the most reliable ways to build wealth. Beyond providing shelter, a home is a valuable asset that can appreciate over time, build equity, and serve as a financial resource for generations.”
Now, you may have seen chatter online saying home prices are falling and wondered if that changes the math. It really shouldn’t. Nationally, home prices are still rising – just at a slower pace than a few years ago.
Yes, some local markets are seeing slight dips, but those dips are small compared to how much home values have grown over the past 5 years. Generally speaking, home prices almost always rise. As long as you plan to live there for a good length of time, you should still have the chance to build equity.
More People Say Buying Beats Renting
And while it’s true homeownership has been seen as a worthwhile pursuit for years now, something interesting is happening. It may actually be gaining a bit more popularity again.
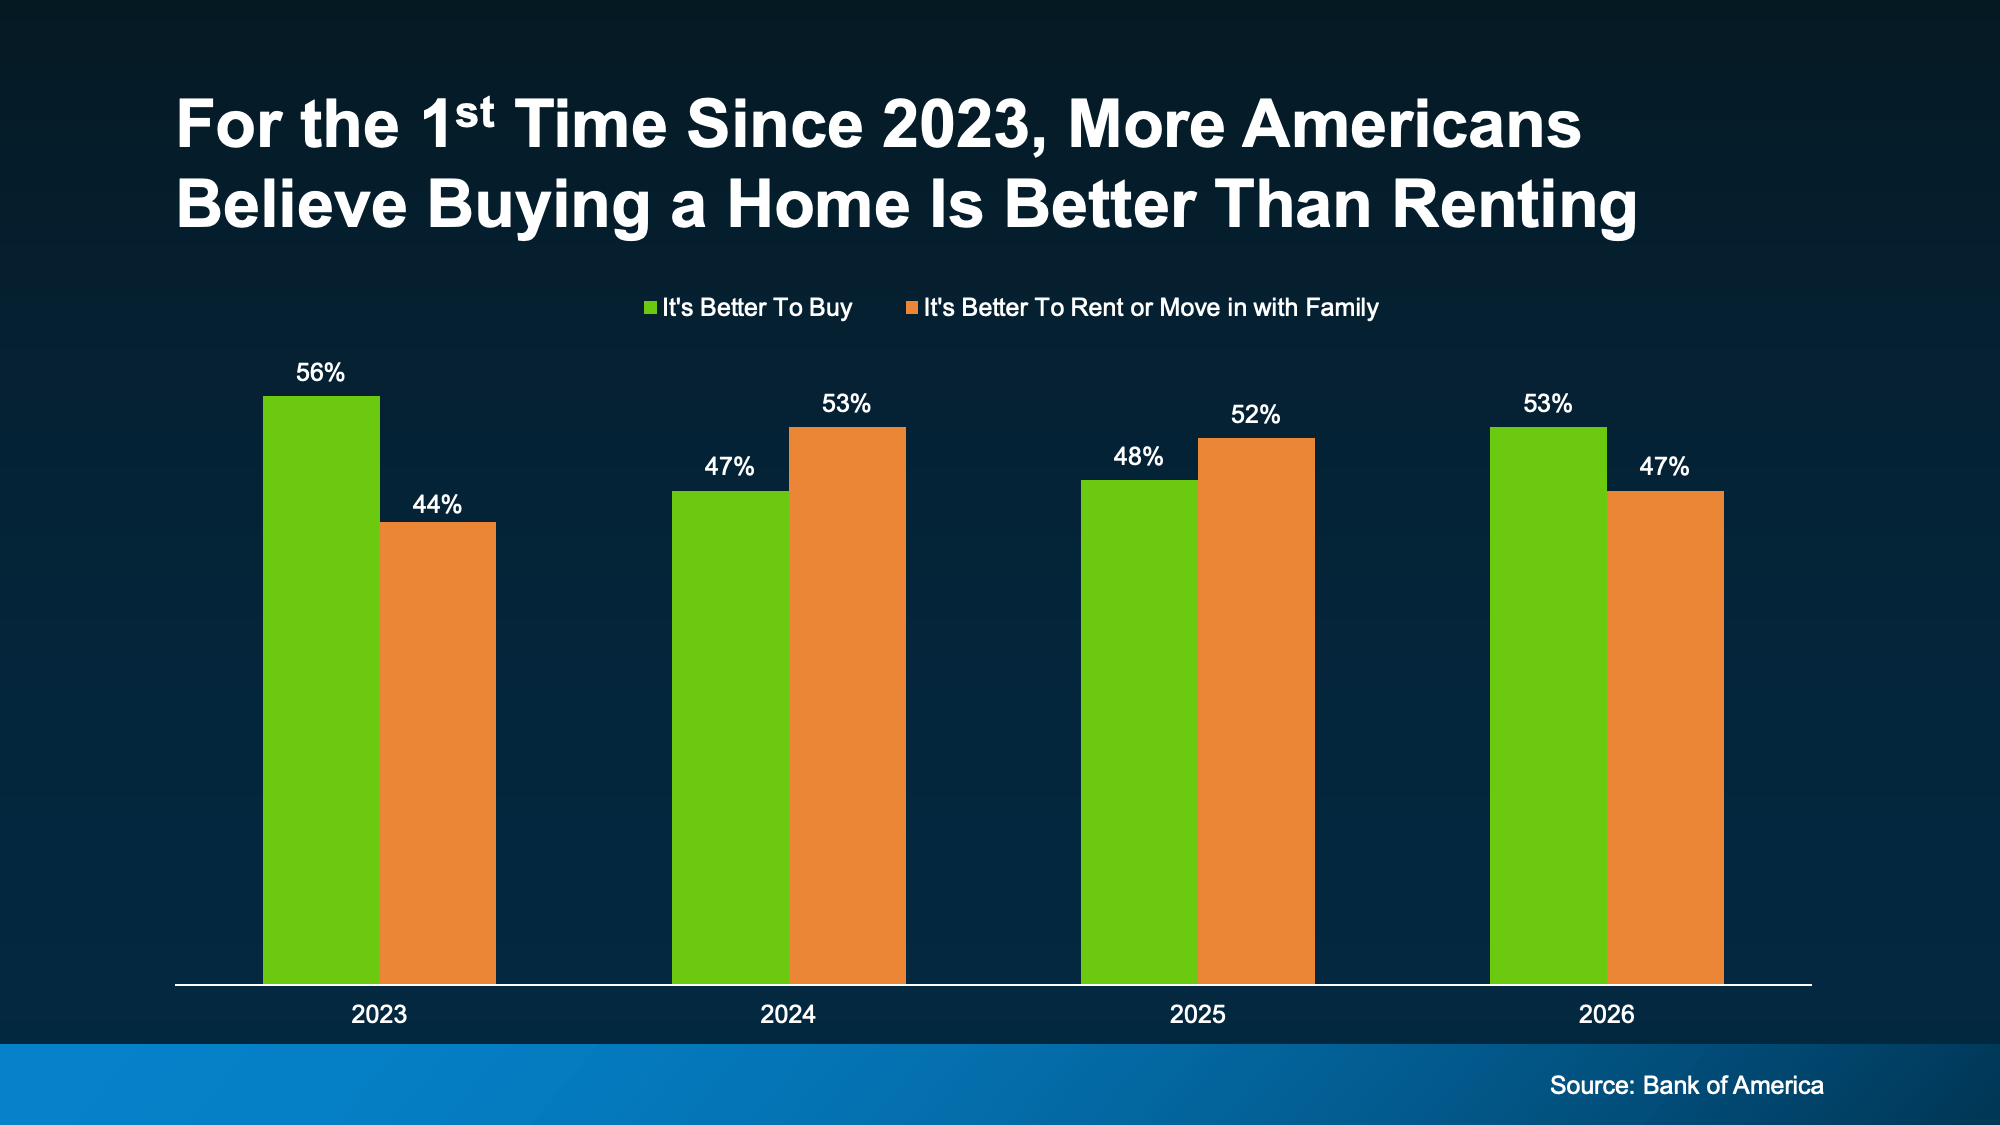
According to Bank of America‘s latest Homebuyer Insights Report, 53% of people now say it’s better to buy a home than to rent or move in with family. That’s the first time buying has taken the lead since 2023 (see graph below):
In that same report, here are a few other signals that confidence in homeownership is on the rise:
-
90% of people say a home is a valuable investment, up from 79% just last year.
-
And 94% say owning a home provides stability, up from 83% the year prior.
Those are relatively big jumps in a short amount of time. And here’s what may be driving it.
It’s About More Than Money
Sure, affordability is still tight and some markets are still hard to break into, but that hasn’t changed what people feel about homeownership as a goal. And the reason why is simple – it’s not just a financial decision. It’s a lifestyle choice.
A home pays you back in ways stocks never could. As Sheharyar Bokhari, Principal Economist at Redfin, says:
“For many homeowners, a home is more than a place to sleep and store belongings—it’s a reflection of who they are. Homeownership can help people put down roots, build relationships and create a space that feels uniquely their own.”
You can’t get that from a brokerage account. A home is the one investment that grows your wealth and gives you a place to build your life. And that means something.
Bottom Line
For 14 years straight, Americans have called real estate the best long-term investment, and confidence in owning a home is on the rise. If you’ve been weighing whether buying is worth it, connect with a local real estate agent and talk through what that first step could look like for you.
It’s one of the biggest hold ups some buyers have right now: “What if I buy, and home prices go down?”
With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.
When you zoom out and look at the full picture, home prices usually rise over time.
What the Data Really Shows
Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year going all the way back to the 1950s.
Here’s the key takeaway.
Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):
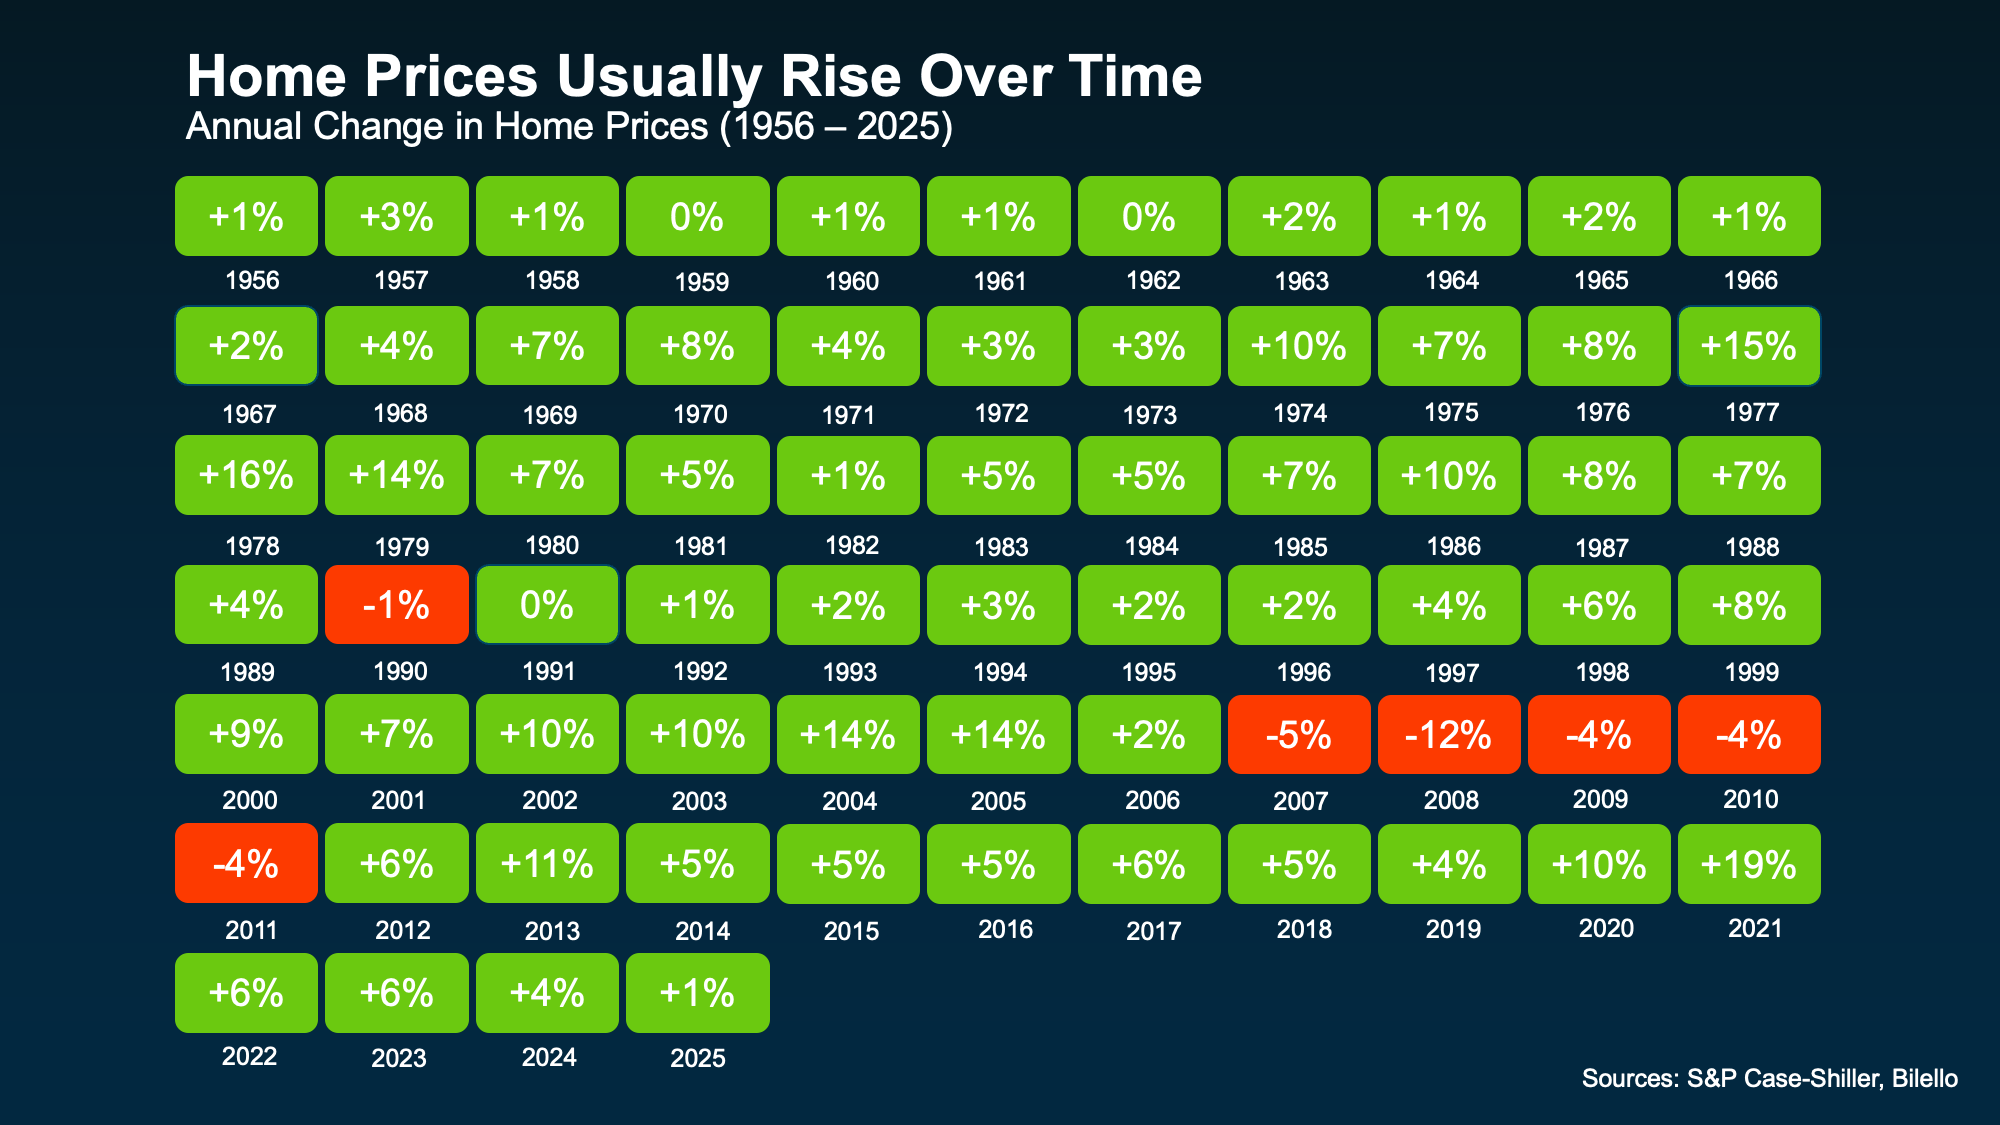 That’s a remarkably consistent track record. And it shows something a lot of headlines miss.
While short-term shifts can happen, it’s the long-term gains that really matter.
Why Prices Tend To Rise Over Time
There are a few core reasons prices usually go up each year:
- There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.
- There still aren’t enough homes for sale. While the number of homes for sale has grown, nationally there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.
- Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.
What That Means for You as a Buyer
It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.
That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.
But historically, the declines have been temporary.
That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And, it’s enough so you can ride out any short-term changes in the market.
Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.
The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.
Bottom Line
Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.
That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.
But if you’re interested, let this reassure you. If you want to talk about what home prices are doing in our market, your goals, or your timelines, reach out to a local agent.

Renovate or Relocate? What To Know Before You Decide To Age in Place

Myth vs. Reality: Does the Fed Control Mortgage Rates?

Two Moves That Can Get You Into Your First Home Sooner


-
 Agent Value4 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
-
 For Buyers4 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
-
 For Sellers3 weeks ago
Selling This Fall? You Want To Get These 4 Things Right.
-
 Agent Value4 weeks ago
Selling This Fall? You Haven’t Missed Your Window
-
 Affordability3 weeks ago
3 Things You Can Actually Control About Your Mortgage Rate Right Now
-
 Affordability3 weeks ago
The Best Time To Buy a Home in 2026 Is Almost Here
-
 Agent Value2 weeks ago
There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?
-
 Affordability2 weeks ago
Why So Many Sellers Are Cutting Their Price Right Now
You must be logged in to post a comment Login