
Mortgage Rates
What Is Going on with Mortgage Rates?
You may have heard mortgage rates are going to stay a bit higher for longer than originally expected. And if you’re wondering why, the answer lies in the latest economic data. Here’s a quick overview of what’s happening with mortgage rates and what experts say is ahead.
Economic Factors That Impact Mortgage Rates
When it comes to mortgage rates, things like the job market, the pace of inflation, consumer spending, geopolitical uncertainty, and more all have an impact. Another factor at play is the Federal Reserve (the Fed) and its decisions on monetary policy. And that’s what you may be hearing a lot about right now. Here’s why.
The Fed decided to start raising the Federal Funds Rate to try to slow down the economy (and inflation) in early 2022. That rate impacts how much it costs banks to borrow money from each other. It doesn’t determine mortgage rates, but mortgage rates do respond when this happens. And that’s when mortgage rates started to really climb.
And while there’s been a ton of headway seeing inflation come down since then, it still isn’t back to where the Fed wants it to be (2%). The graph below shows inflation since the spike in early 2022, and where we are now compared to their target rate:
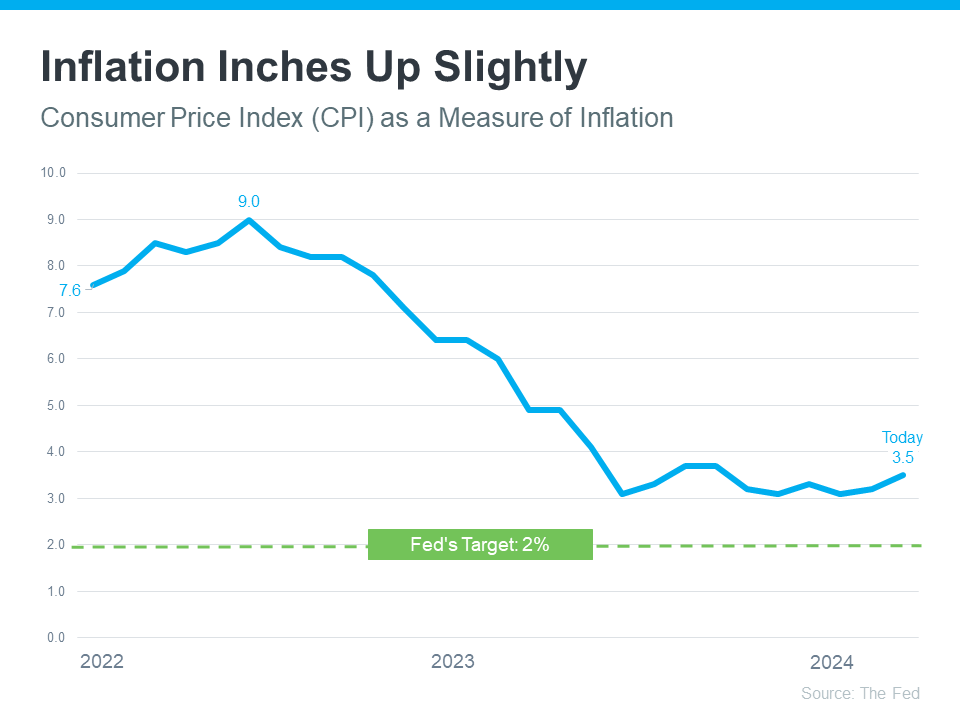
As the graph shows, we’re much closer to their goal of 2% inflation than we were in 2022 – but we’re not there yet. It’s even inched up a hair over the last 3 months – and that’s having an impact on the Fed’s plans. As Sam Khater, Chief Economist at Freddie Mac, explains:
“Strong incoming economic and inflation data has caused the market to re-evaluate the path of monetary policy, leading to higher mortgage rates.”
Basically, long story short, inflation and its impact on the broader economy are going to be key moving forward. As Greg McBride, Chief Financial Analyst at Bankrate, says:
“It’s the longer-term outlook for economic growth and inflation that have the greatest bearing on the level and direction of mortgage rates. Inflation, inflation, inflation — that’s really the hub on the wheel.”
When Will Mortgage Rates Come Down?
Based on current market data, experts think inflation will be more under control and we still may see the Fed lower the Federal Funds Rate this year. It’ll just be later than originally expected. As Mike Fratantoni, Chief Economist at the Mortgage Bankers Association (MBA), said in response to the Federal Open Market Committee (FOMC) decision yesterday:
“The FOMC did not change the federal funds target at its May meeting, as incoming data regarding the strength of the economy and stubbornly high inflation have resulted in a shift in the timing of a first rate cut. We expect mortgage rates to drop later this year, but not as far or as fast as we previously had predicted.”
In the simplest sense, what this says is that mortgage rates should still come down later this year. But timing can shift as new employment and economic data come in, geopolitical uncertainty remains, and more. This is one of the reasons it’s usually not a good strategy to try to time the market. An article in Bankrate gives buyers this advice:
“ . . . trying to time the market is generally a bad idea. If buying a house is the right move for you now, don’t stress about trends or economic outlooks.”
Bottom Line
If you have questions about what’s happening in the housing market and what that means for you, connect with a trusted real estate professional.
When mortgage rates climb, buying a home can start to feel like trying to hit a moving target. Every jump in rates makes monthly payments bigger, and that pushes a lot of buyers to look for another way in.
More and more of them are finding it in the adjustable-rate mortgage, or ARM.
The ARM Option
Here’s how an ARM differs from a more traditional mortgage. With a regular fixed-rate mortgage, your rate stays the same for your whole loan. But with an ARM, your rate is locked for the first few years, then it can move up or down based on market conditions.
Some people don’t like that level of uncertainty – and that’s okay. But others are drawn to this option specifically because there’s usually a lower rate to start when you opt for an ARM. And in an affordability-strapped market, that’s going to gain popularity.
Bankrate recently found that, in September, rates for ARM products were over a full percentage point lower than a regular fixed-rate loan. Depending on the ARM product, that can make a difference of $150-300 in the monthly payment on a median-priced home.
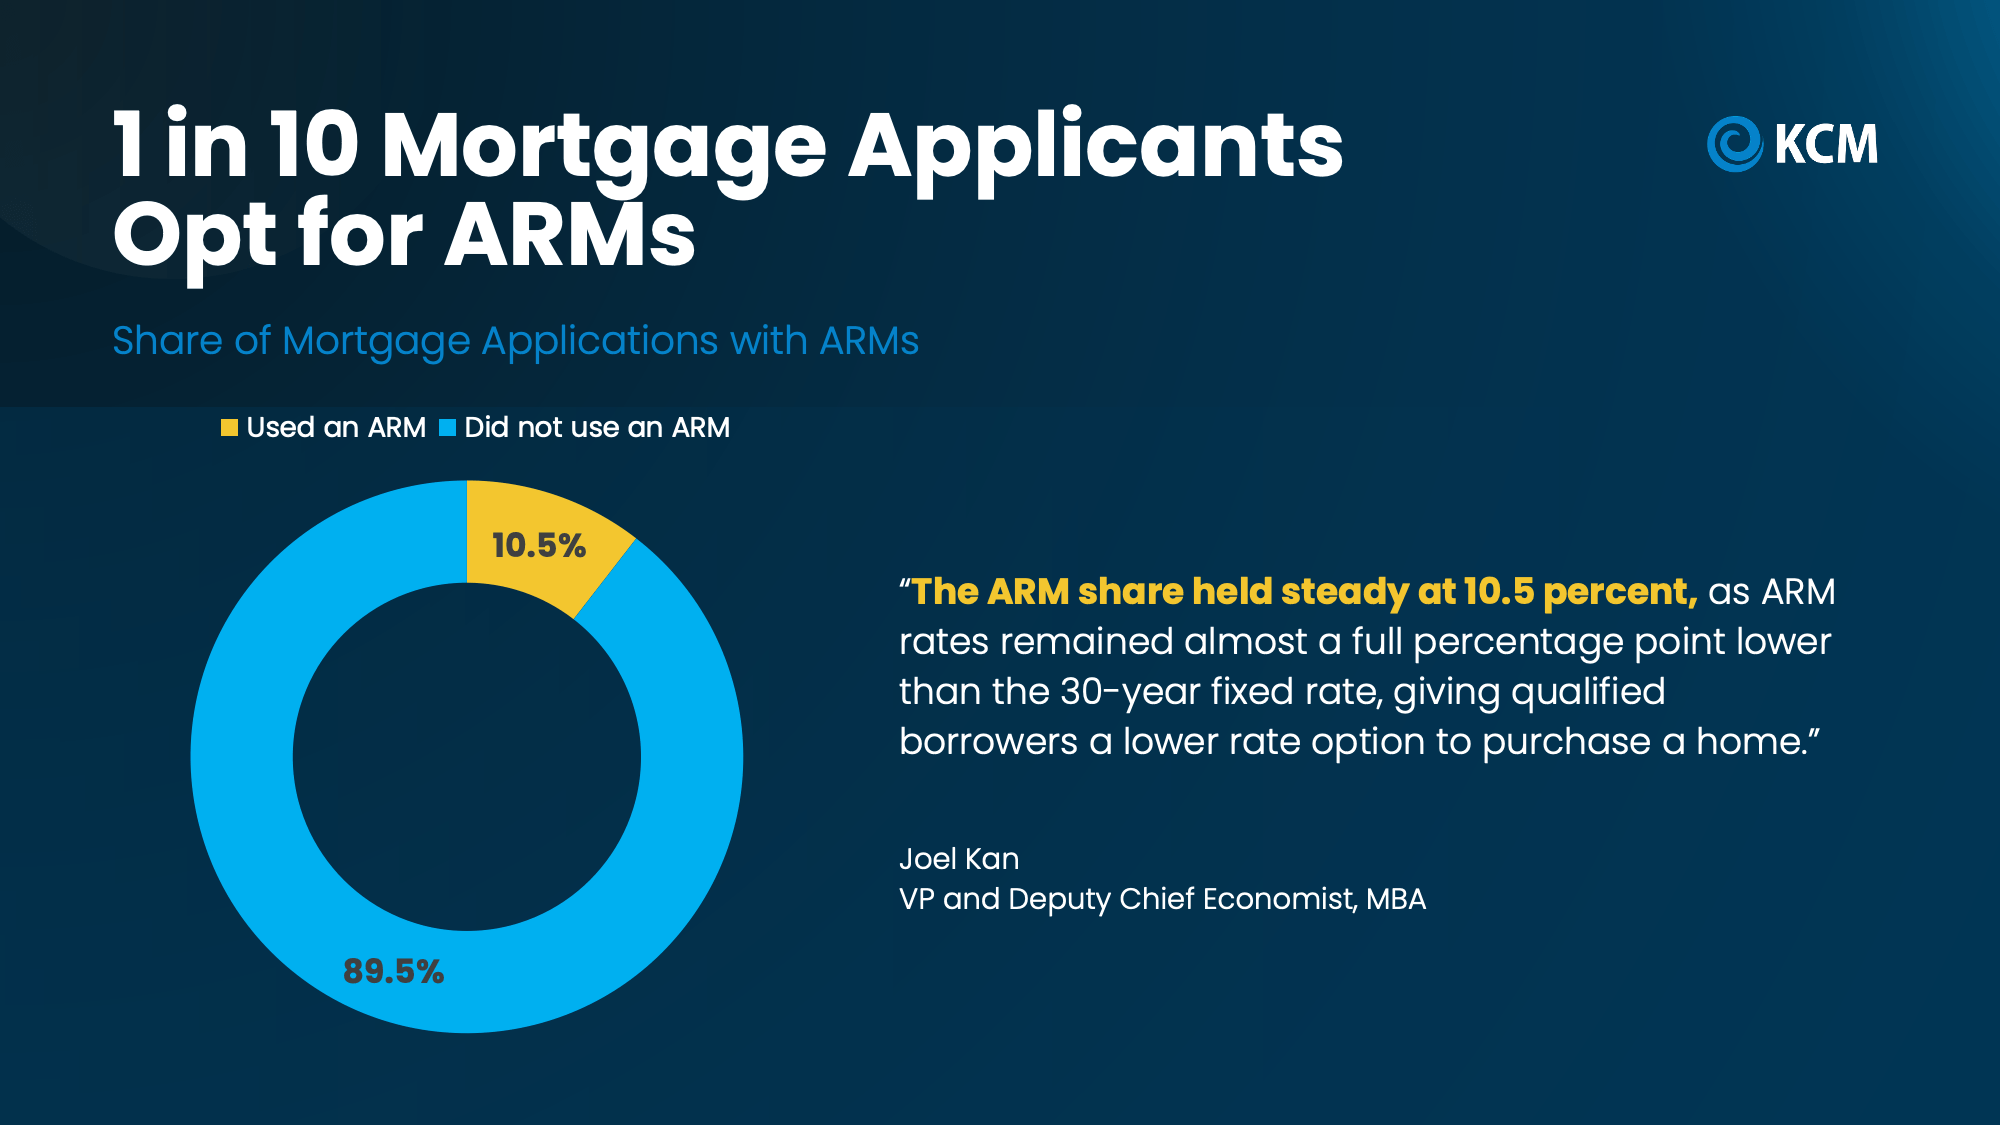
And for some buyers, that’s enough to turn “not right now” into “let’s do this.” You can see it in the numbers. Data from the Mortgage Bankers Association (MBA) shows that, in October, roughly 1 in 10 people applying for a mortgage chose an ARM (see graph below):
If you think you may want to consider this yourself, here’s what you need to know about how it works.
The 5/1 ARM
An ARM is like a phone or cable plan that has an introductory deal for new customers. You start out at a lower price, and then it adjusts after a specified amount of time. A popular loan is the 5/1 ARM.
The “5” means your introductory rate is locked for the first five years, and the “1” means that the rate can change every year after that. The rate change is called the “reset.” And here’s the really important part.
When your rate resets, your mortgage payment could go up or down. The good news is that most ARMs have caps, which are limits on how much your rate can rise each year and over the life of the loan. But either way, you have to be ready.
The Upsides and Potential Downsides
To see if this type of loan may be right for you, here are some things to think about and discuss with your loan officer:
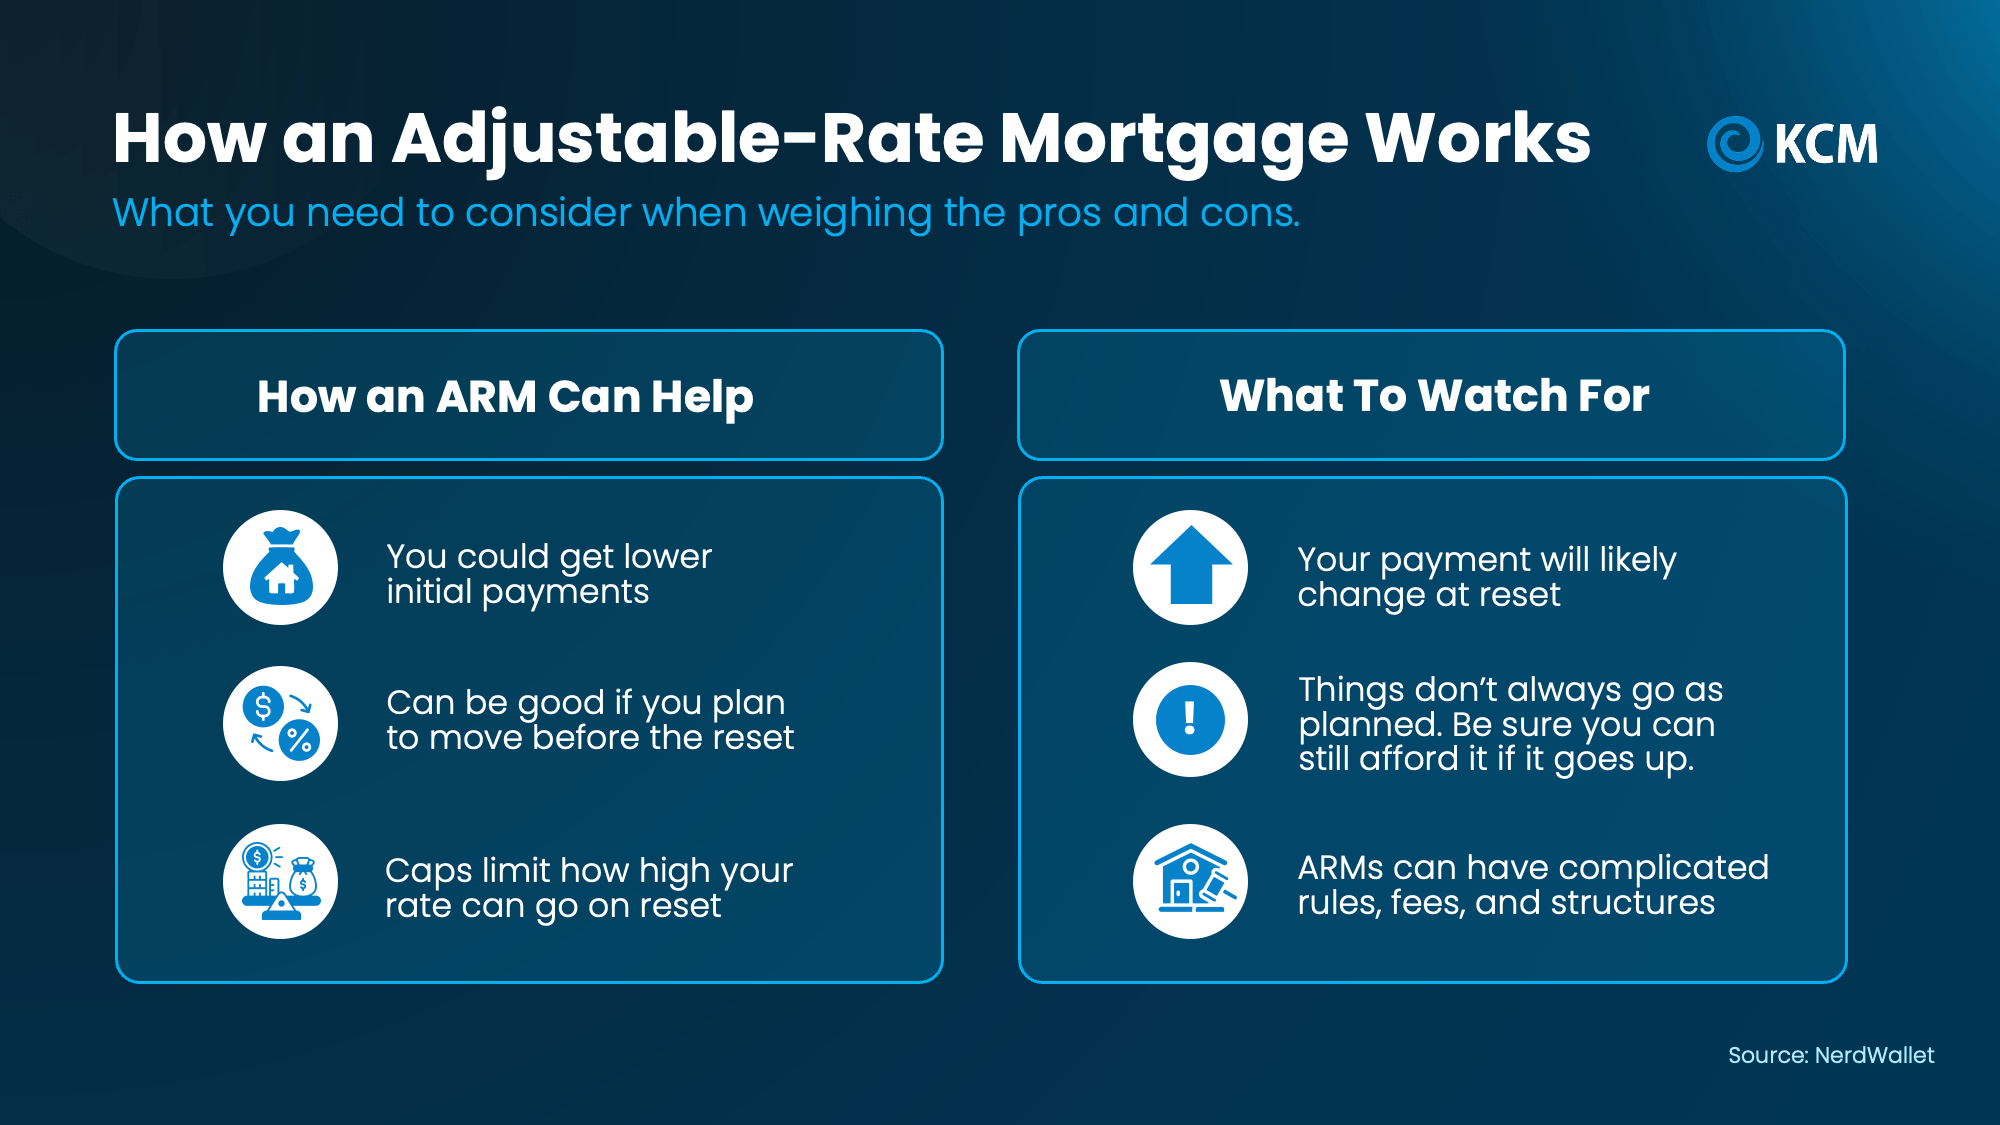
Before you decide, ask your lender to work up the numbers and walk you through the different potential scenarios you could run into with an ARM. That way, you go in with your eyes open.
Be Ready for the Reset
And, if you do go with an adjustable-rate mortgage, just know that you’ll have choices when the reset time arrives. You could:
-
Do nothing and keep your loan in place if the new payment still fits your budget.
-
Refinance into a fixed-rate loan with a payment that never changes.
-
Refinance into another ARM with a new lower rate locked for a specified timeframe.
-
Sell your home.
-
Talk to the loan servicer about assistance or modification.
Remember, a refinance is a brand-new loan that you’ll have to qualify for – even if it’s on a home you already own. So, keep tabs on your credit and debt levels and ask your loan officer how major financial moves like job changes and major purchases will affect your mortgage readiness. It’s important to keep your credit and finances in “mortgage shape.”
Today’s ARMs Aren’t Like 2008
One more quick note. ARMs got a bad name after the financial crisis of 2008. Back then, there were some risky loans with small starting payments that later shot way up. Others let people borrow without proving how much money they earned.
But now, there are new laws to protect both borrowers and lenders. The biggest change is the Ability-to-Repay Rule, which says that before a lender makes a home loan, it has to check real paperwork (like pay stubs, W-2 forms, and tax returns) to make sure you can afford it. The lender also has to look at what your payment could be after the reset, not just the low starting payment.
So, you don’t have to worry that today’s ARMs are the same as the ones we saw back during the crash.
Bottom Line
Today’s market has more options than many people realize. Finding the right one could be as simple as getting more information about tools like ARMs. A trusted lender can run the numbers with you, walk you through the what-ifs, and help you explore the possibilities.
Is an ARM a good option for you? Talk to a loan officer to find out.
You’ve probably heard the Federal Reserve (the Fed) is raising rates again. And if you’re planning to buy or sell a house, you may be wondering what that means for you.
With all the headlines, it’s easy to think the Fed sets mortgage rates. That’s actually a common myth. But the Fed’s decisions can still have an impact on them.
So, where does that leave you? The next few months could get a little bumpy. But the Fed is playing the long game. And with the right plan, you can still make a move that works. Let’s break it down.
Why the Fed Is Raising Rates
It all comes back to inflation. With prices rising fast, everything is getting more expensive – and that leaves buyers with less spending power and makes homes cost more to build.
So, the Fed raises its key short-term rate (the Federal Funds Rate) to slow down inflation. And that’s where a lot of people get tripped up.
-
MYTH: The Fed controls mortgage rates.
-
REALITY: The Fed has an impact on mortgage rates, but it’s only one piece of the puzzle.
As NerdWallet explains:
“The Federal Reserve influences mortgage rates, but doesn’t set them. . . Mortgage rates are influenced by many elements, including the inflation rate, the pace of job creation, and whether the economy is growing or shrinking. The Federal Reserve’s monetary policy is a factor, too . . .”
Here’s the simplest way to explain how it all fits together. Mortgage rates tend to follow something called the 10-year treasury yield. That’s the return investors get for lending money to the government for 10 years. And that yield moves up and down based on what investors expect from inflation and the economy.
Right now, one of the biggest things moving that yield is the conflict in Iran. It’s pushed oil prices higher, which has investors worried about inflation. That’s why any news about the conflict can move mortgage rates. If there’s resolution in Iran, that could take some pressure off inflation and mortgage rates. But the timing is hard to predict.
What the Fed does can move that yield, too. When they hike the Federal Funds Rate to fight inflation, investors pay attention. That can push the 10-year yield up, and mortgage rates usually follow. But once inflation cools, the yield has room to come back down, and mortgage rates can, too. That gives buyers some of their purchasing power back (see graphic below):
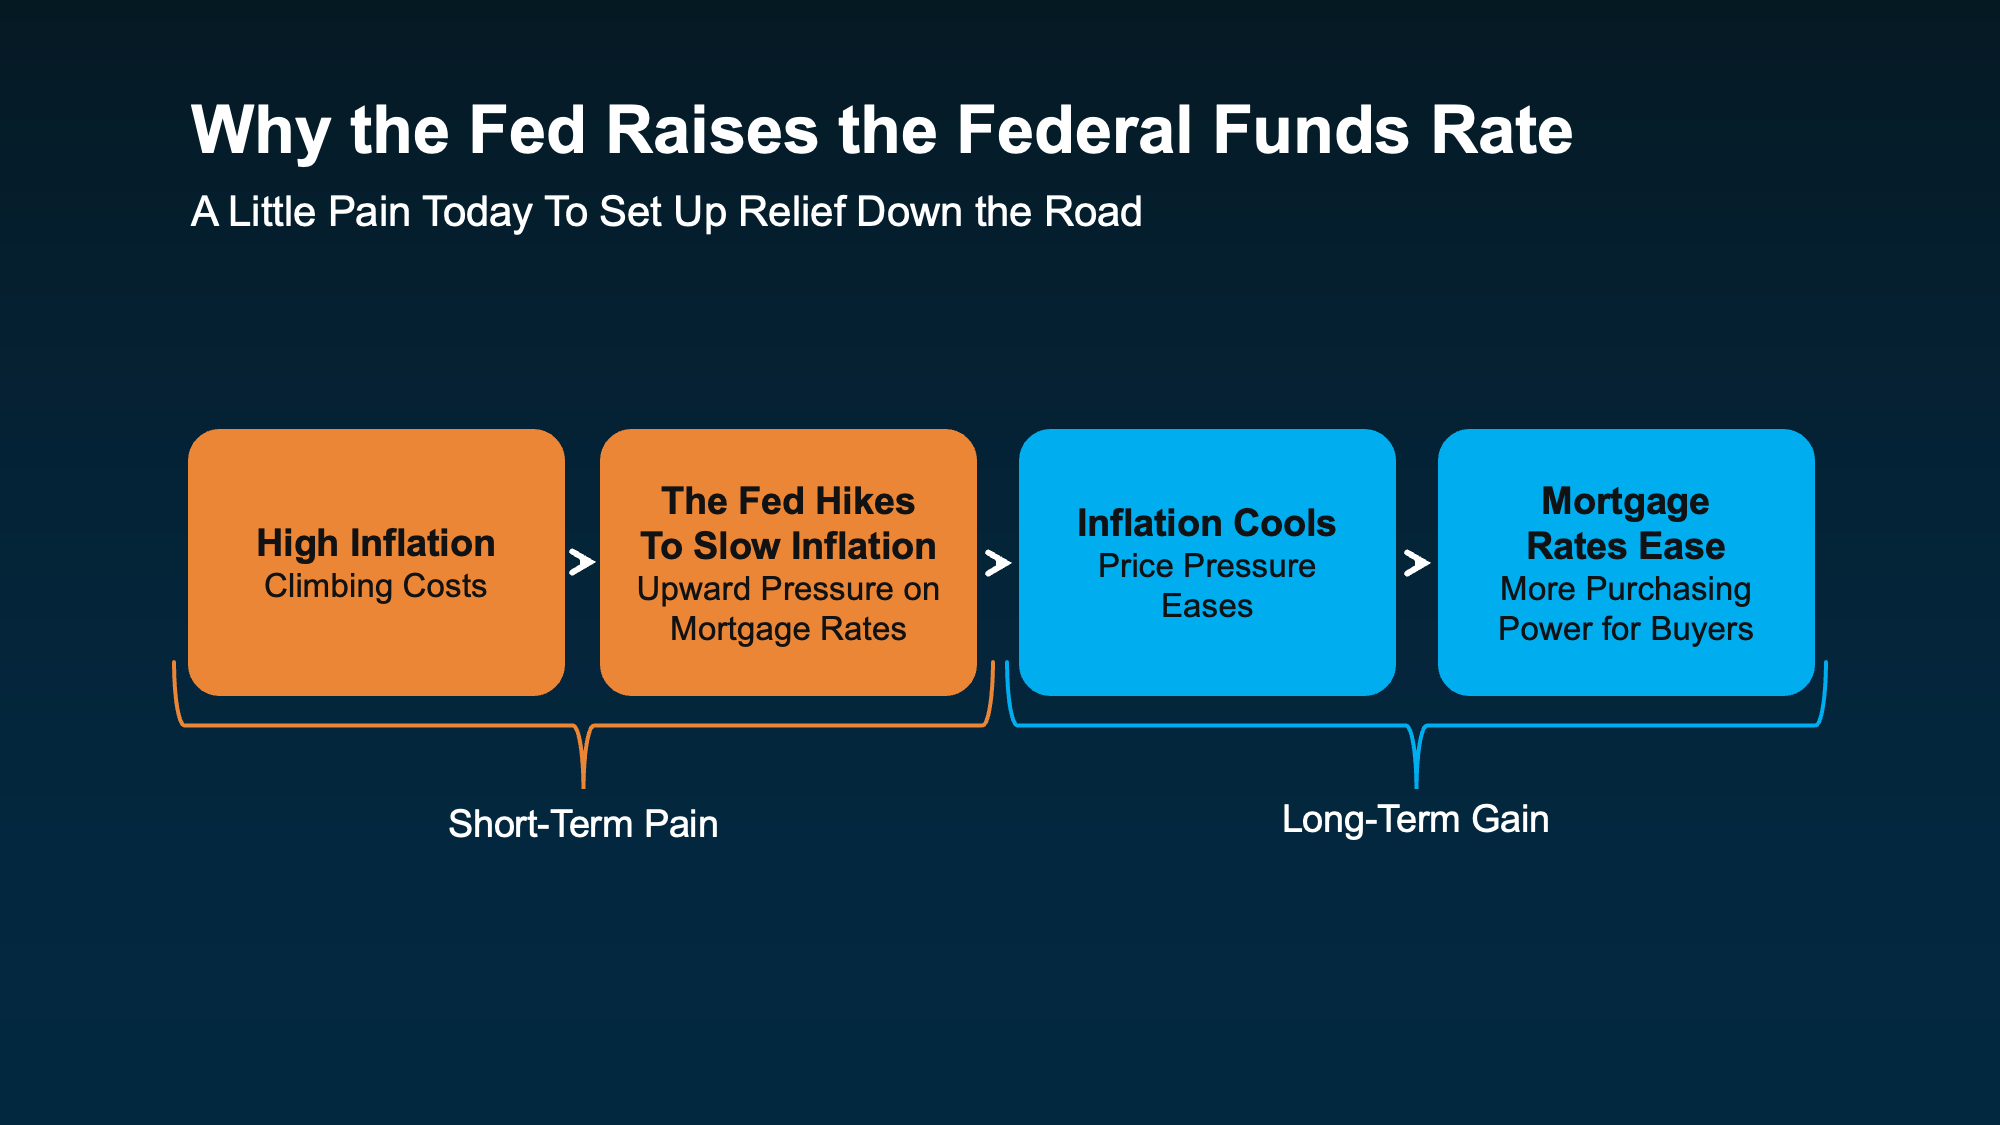
Think of it as a little pain today to set up some relief down the road. But how long could that short-term pain last? A lot depends on what the Fed does next.
There’s a Strong Possibility the Fed Will Hike Again This Year
According to CME FedWatch, there’s over an 80% chance the Fed hikes their federal funds rate at least once more before the end of 2026 (see graph below):

Remember, the Fed doesn’t set mortgage rates. But another hike will likely keep upward pressure on them in the short term. So, should you wait it out? Sam Williamson, Senior Economist at First American, says this:
“Over time, firmer Fed action could help steady the bond market and open the door to lower mortgage rates, but only if investors become more confident that inflation is coming under control.“
And there are some early signs that’s starting to happen. Inflation cooled faster than experts expected in August:
-
PCE inflation dropped to 3.4%, down from 3.7% in July.
-
Core PCE (the Fed’s preferred measure which leaves out food and energy prices) fell to 3%, down from 3.3%.
That’s a step in the right direction, and it’s part of why the odds of a hike at the Fed’s October meeting have come down recently. But inflation’s still above the Fed’s 2% target, and it’s been that way for about 5 years. So, lower rates could still take a while. Your best bet is a plan that works at today’s rates.
How To Make Your Move Work Right Now
While this rate hike cycle isn’t the headline you want to see, it doesn’t mean you have to wait. There are still ways to move, even now.
-
If you’re buying: Get pre-approved so you know your real budget. Ask your lender about your options to get the best rate possible. And once you’re under contract, lock your rate so a jump before closing doesn’t raise your payment.
-
If you’re selling: Decide what matters most to you – a quick sale or top dollar. Each one can call for a different plan. Price for today’s buyers, whose budgets are smaller with higher rates. And think about offering a rate buydown or other concession. They can do more for a buyer’s budget than a price cut.
Bottom Line
The Fed doesn’t set mortgage rates, but its hikes can keep them higher for a while. The goal is to bring inflation, and eventually rates, down over time. With more hikes likely this year, waiting may not pay off. So, connect with a local real estate agent to map out a plan that works at today’s rates.
Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too.
That’s because today’s buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they’re looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.
If you’re planning to sell, that doesn’t mean you can’t compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.
Builders Are Competing on the Monthly Payment
New construction has something interesting going for it right now. While existing-home sales (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.
In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.
One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:
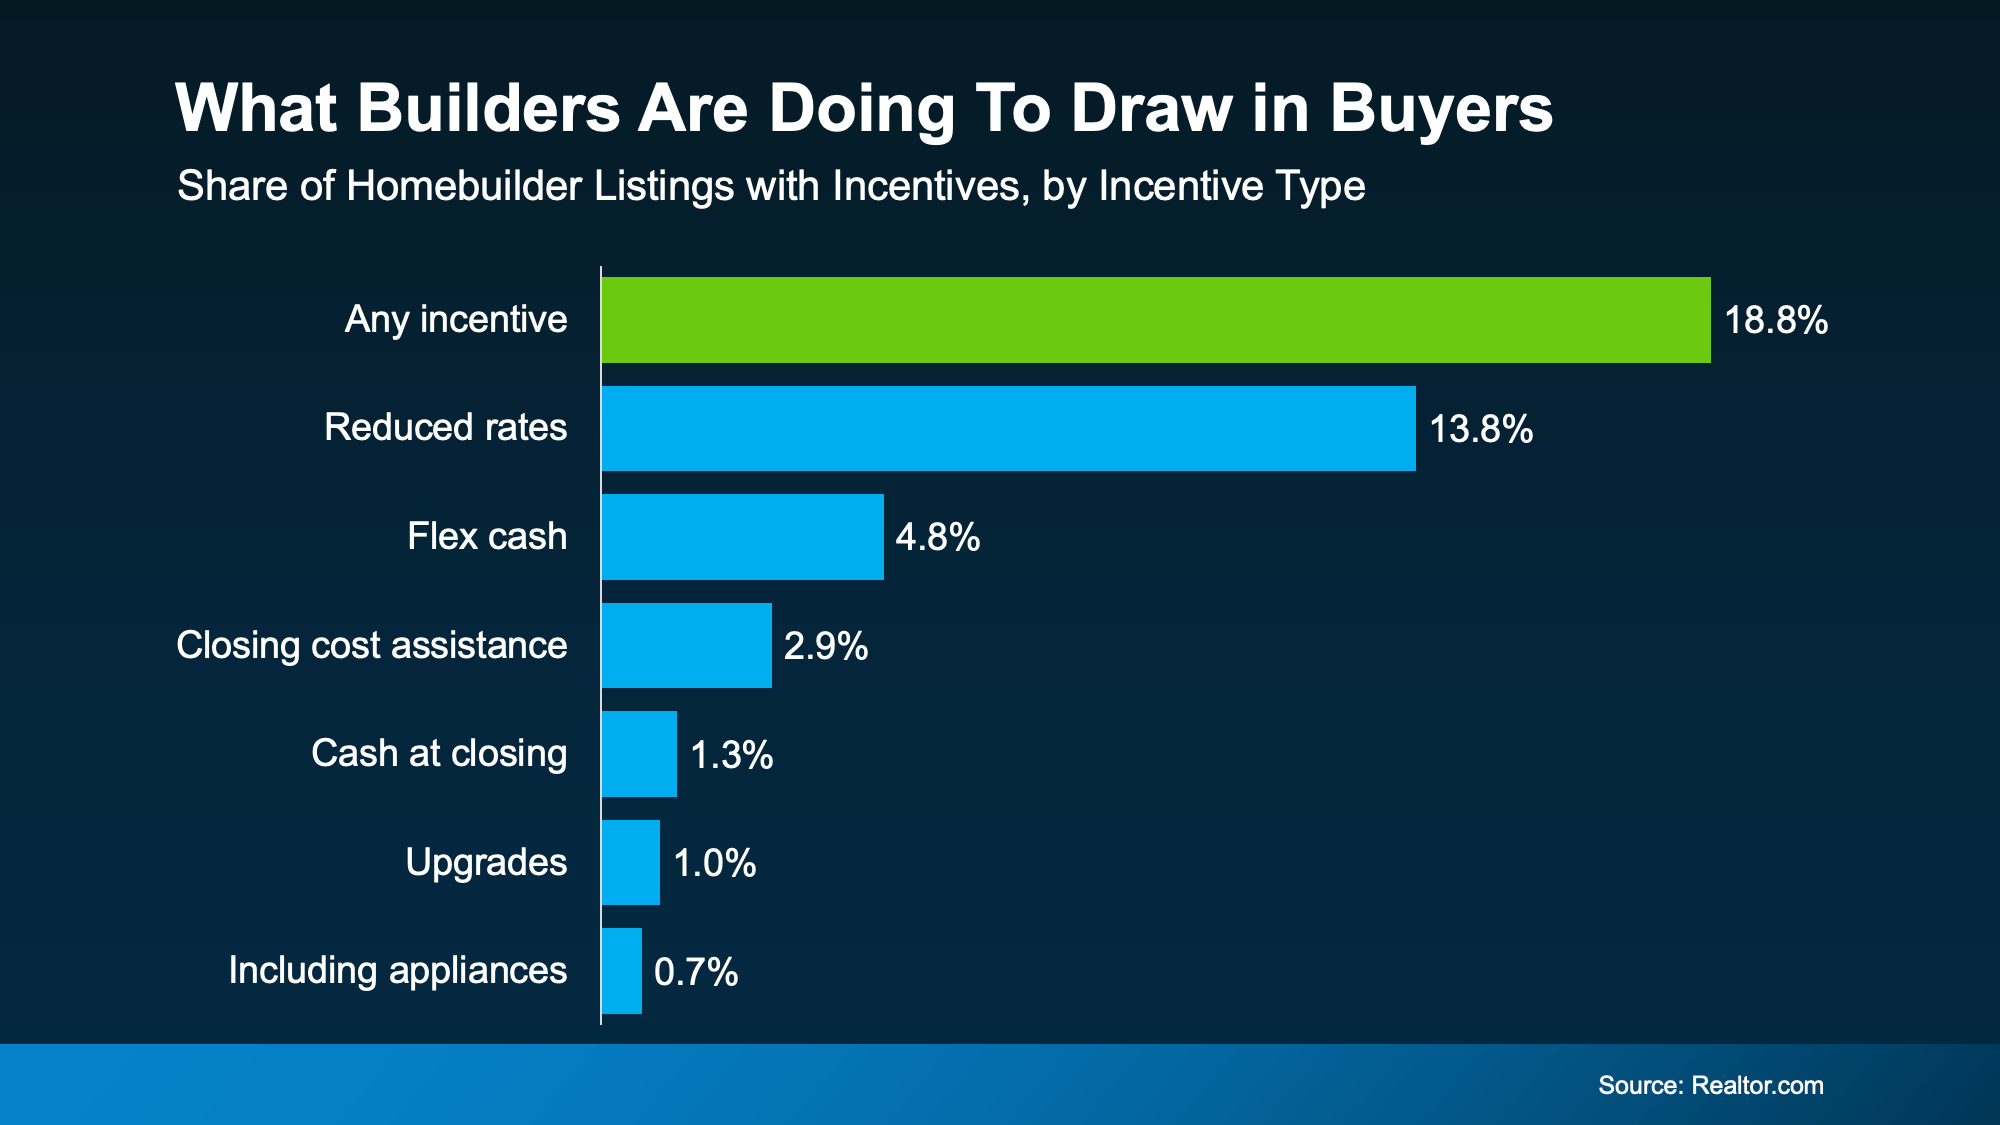
The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.
It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.
In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That’s a big difference to a buyer who are feeling the pinch right now.
So, How Can Sellers Like You Compete?
First, don’t assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer’s rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.
A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can’t. That’s why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:
“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”
A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.
Today’s Market Rewards Sellers Who Adapt
Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That’s putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:
“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”
That’s an important message if you’re hoping to sell.
You don’t automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.
And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren’t equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.
Bottom Line
Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with rate buydowns, closing-cost help, price reductions, and other incentives.
If you’re thinking about selling, talk to an agent about what buyers are getting from other homes in your area – including new construction – so you can make sure your house is positioned to compete.

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today

To Sell or Rent? How To Choose the Best Path for Your House.

Confused by Home Price Headlines? Here’s Why.


-
 Buying Tips3 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 For Sellers3 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability4 weeks ago
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.
-
 Affordability3 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Affordability2 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Downsize2 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
-
 Affordability2 weeks ago
Why Most People Are Still Glad They Bought a Home
-
 Buying Tips1 week ago
Why There are More Homes for Sale Right Now (and What It Means for You)
You must be logged in to post a comment Login