First-Time Buyers
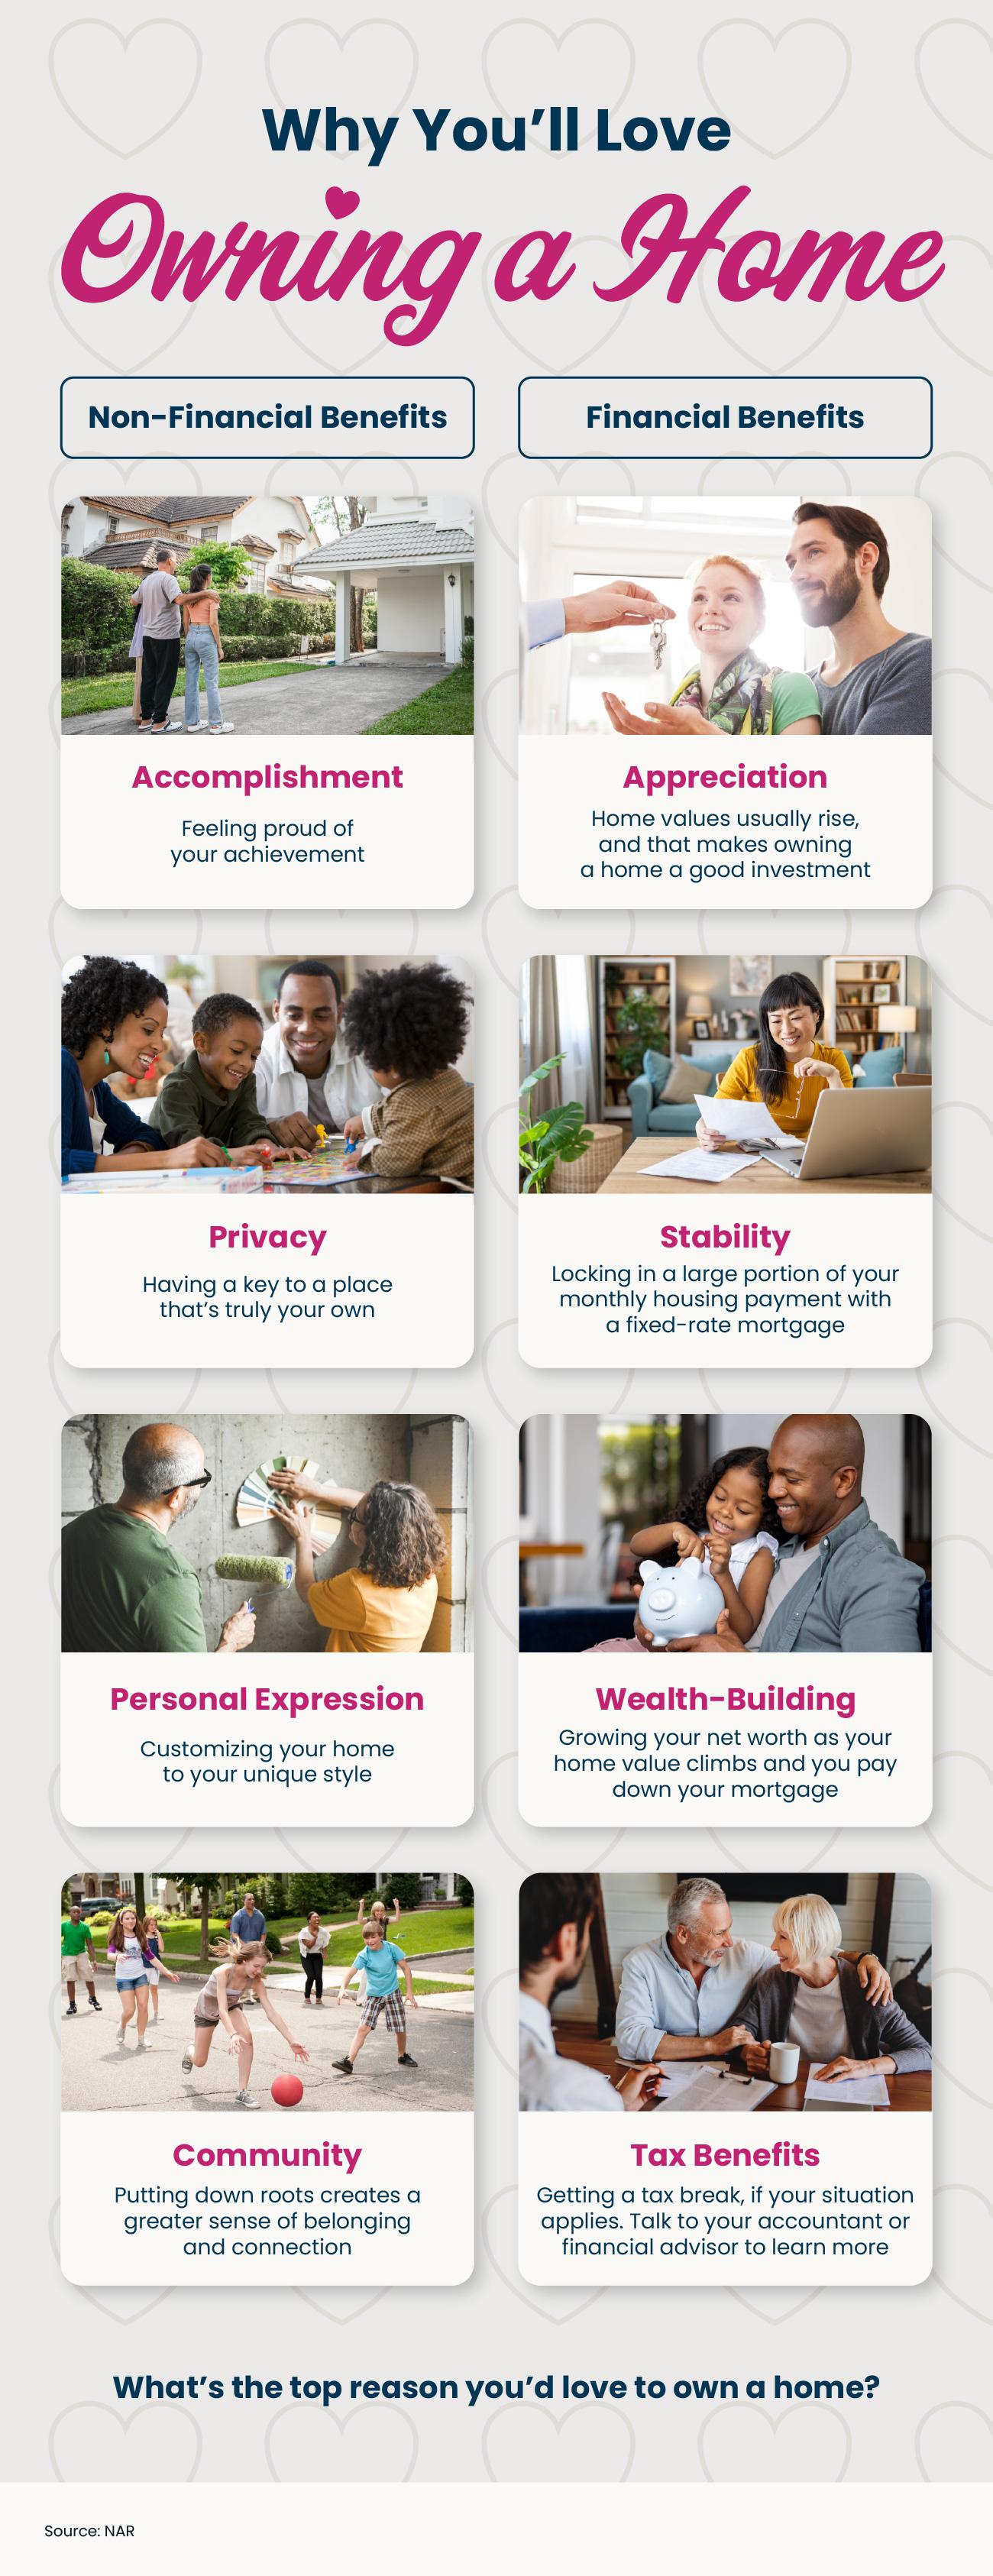
Why You’ll Love Owning a Home
Some Highlights
- Owning a home comes with many benefits, both non-financial and financial.
- From the sense of accomplishment and freedom of expression, to growing your net worth, it’s easy to fall in love with homeownership.
- What’s the top reason you’d love to own a home? Connect with an agent to come up with a plan that makes it possible.
You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember…
That’s not necessarily the number you’d get.
It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about.
What Determines Your Real Rate?
Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that.
That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:
-
Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.
-
Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.
-
The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage.
-
The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs.
Even after you find a home you love, other things can have an impact too. For example:
-
A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.
-
Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate.
There’s a lot that can ultimately have an impact on your actual rate.
Your First Step? Getting Pre-Approved.
If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be.
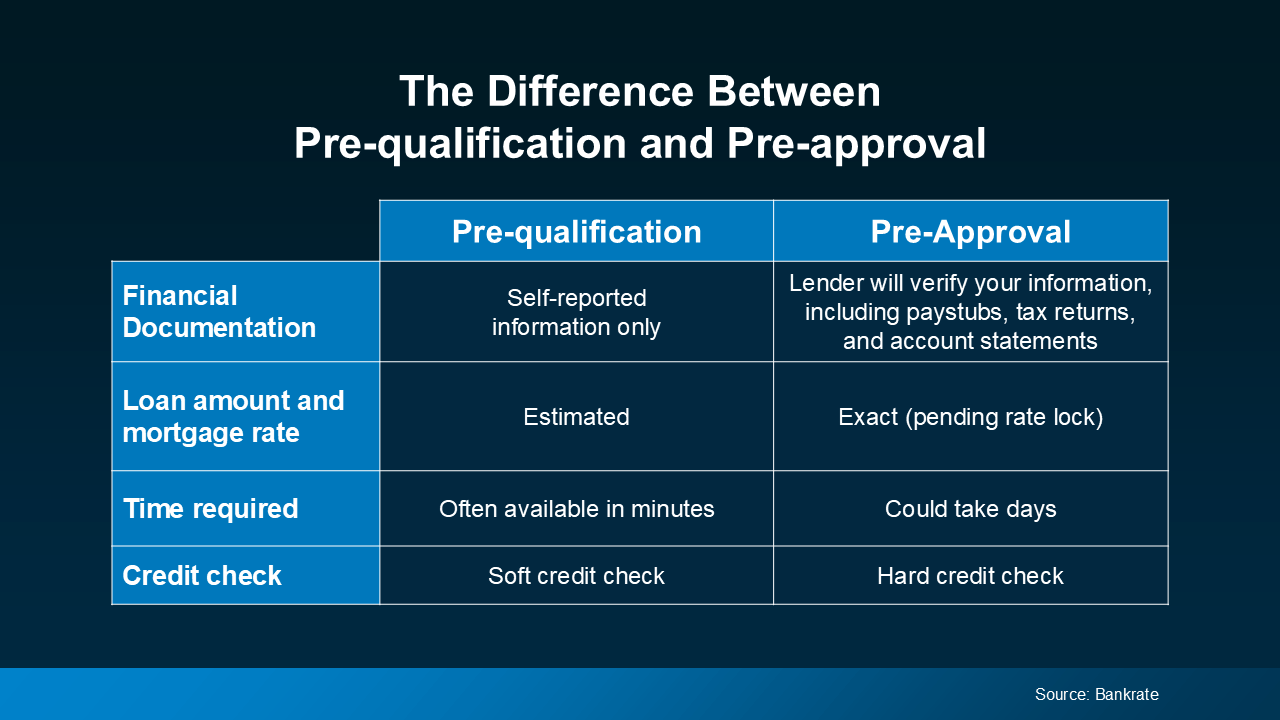
Your lender may recommend a pre-qualification and pre-approval:
-
Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information.
-
On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information.
Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:
How To Get Ready for the Conversation
Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk:
-
What will I gain or lose by waiting to buy a home for 3, 6, or 12 months?
-
Will I get any tax advantages by buying a home – and what are they?
-
What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?
-
How will rate changes in either direction affect me?
Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.
Bottom Line
Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender.
With the right help, you can find out what your real rate is – and where it can take you.
Want to buy a house this year, but not sure if the timing’s right? Seasonally, it may actually be a better time to buy than you expect.
Yes, mortgage rates have been ticking up lately – and that’s creating some real challenges with affordability. No one’s arguing that. But there are also predictable trends that happen this time every year that can put some wind back in your sails.
According to research coming out of Realtor.com, nationally, the week of September 27 – October 3 will be the best time to buy this year for this very reason:
“The week of September 27–October 3 brings together the market conditions buyers value most—elevated inventory, less competition and prices that have eased from their seasonal high—giving prepared buyers a way to offset high rates with savings on price and room to negotiate with confidence.”
But that’s the national best week. Depending on where you live, your local sweet spot may come a little earlier or later (see map below):
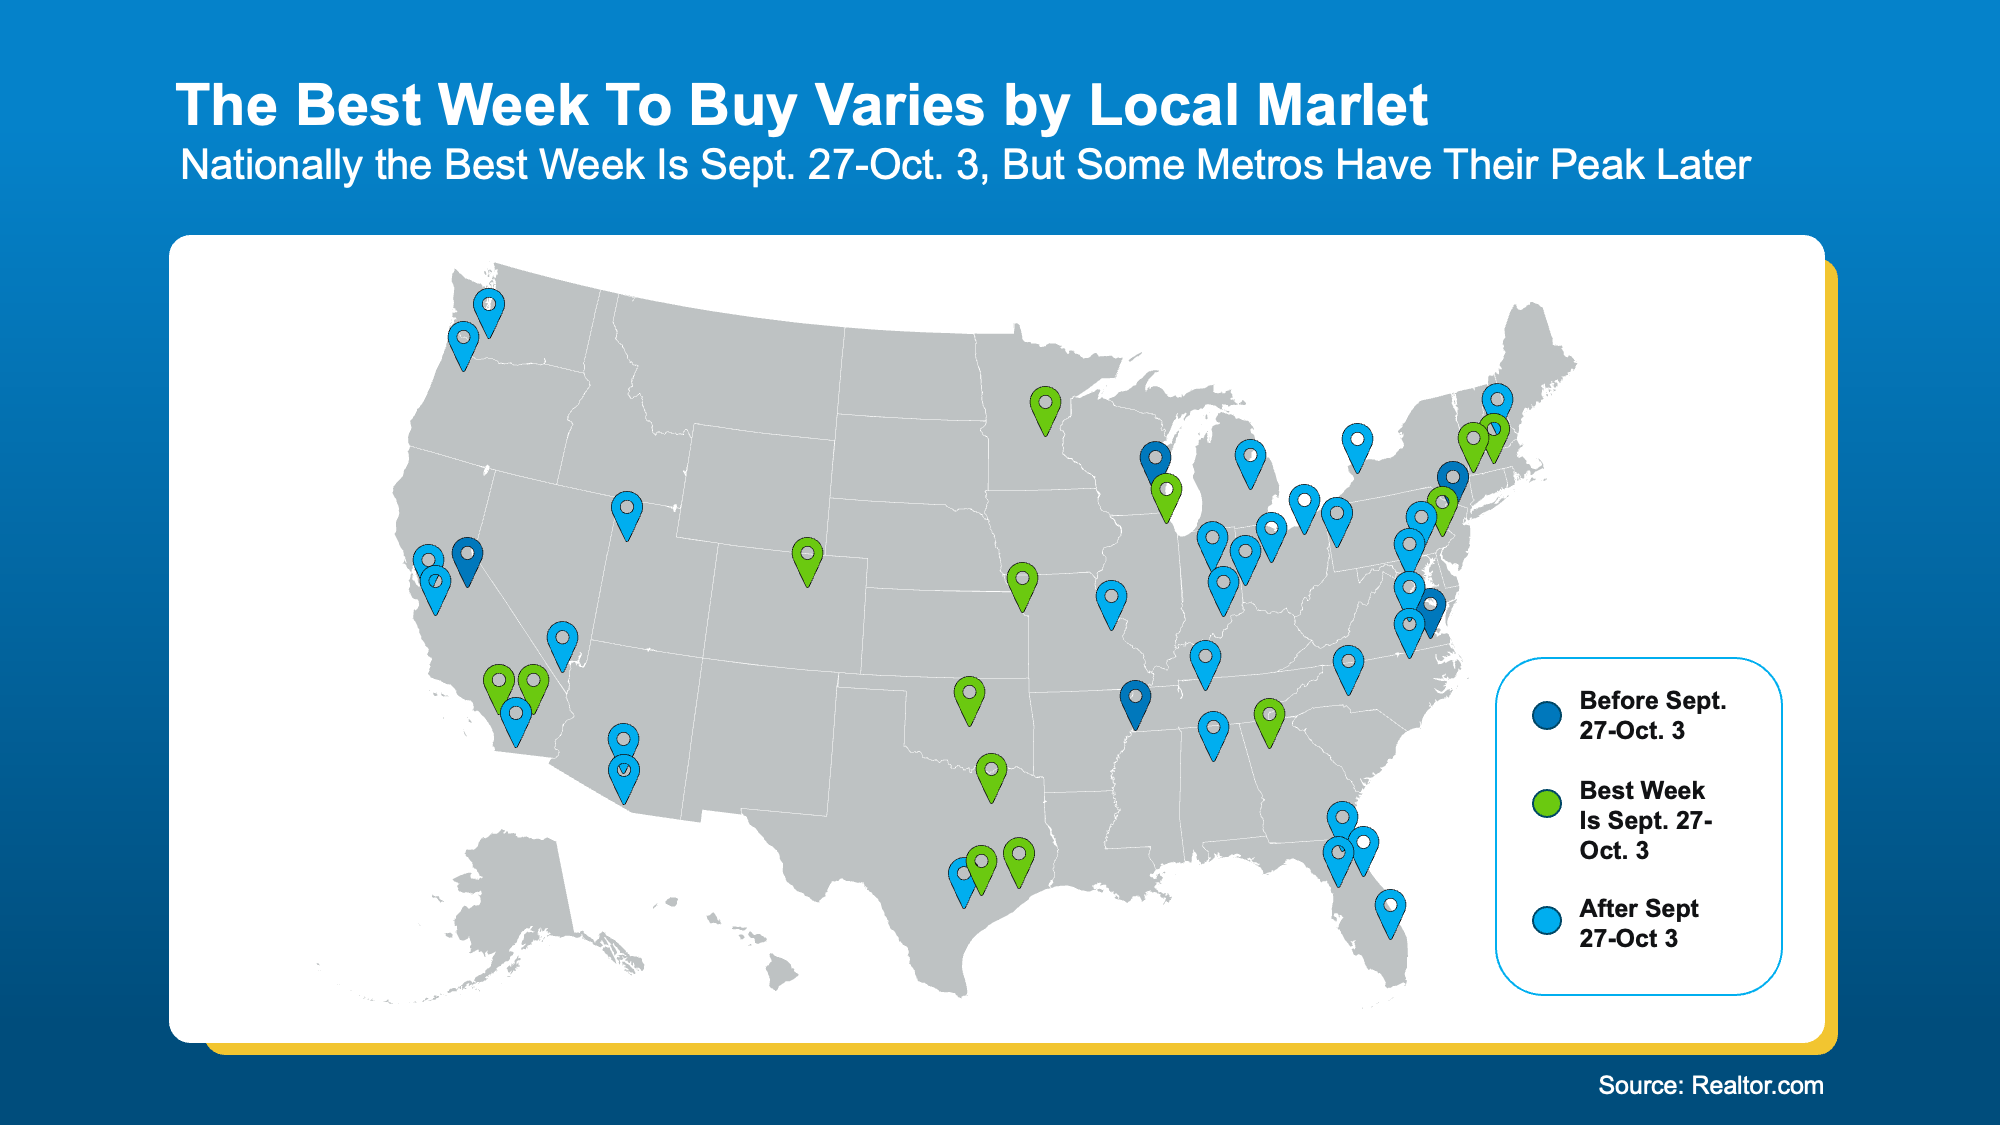
It all depends on local trends and how inventory and buyer demand ebbs and flows seasonally where you want to live. But no matter when your market hits its peak, here are some of the perks you can expect this time of year.
More Choices, Better Prices, and Less Competition
For starters, there are more homes to choose from. In fact, data from the National Association of Realtors (NAR) shows the number of homes for sale recently reached its highest level in more than 10 years:
“NAR’s data does show a strong uptick in for-sale inventory at the end of the summer, reaching the highest level in more than 10 years.”
That means you may have a better shot at finding something you love and can afford without making as many compromises. And that’s not the only advantage.
Realtor.com says buyers during this window could see home prices about $14,000 lower than the summer peak, along with 30% less competition from other buyers. Plus, homes tend to stay on the market almost 2 weeks longer (13 days), giving you a little more breathing room to make a decision.
-
More choices.
-
Better pricing.
-
Less competition.
That combination could be enough to ease some of the pressure higher mortgage rates are putting on your budget.
The Window Doesn’t Close After This One Week
But you certainly don’t have to buy during that very specific window. This isn’t a one-week-only opportunity. History tells us conditions should be tipped in your favor for the entire month of October:
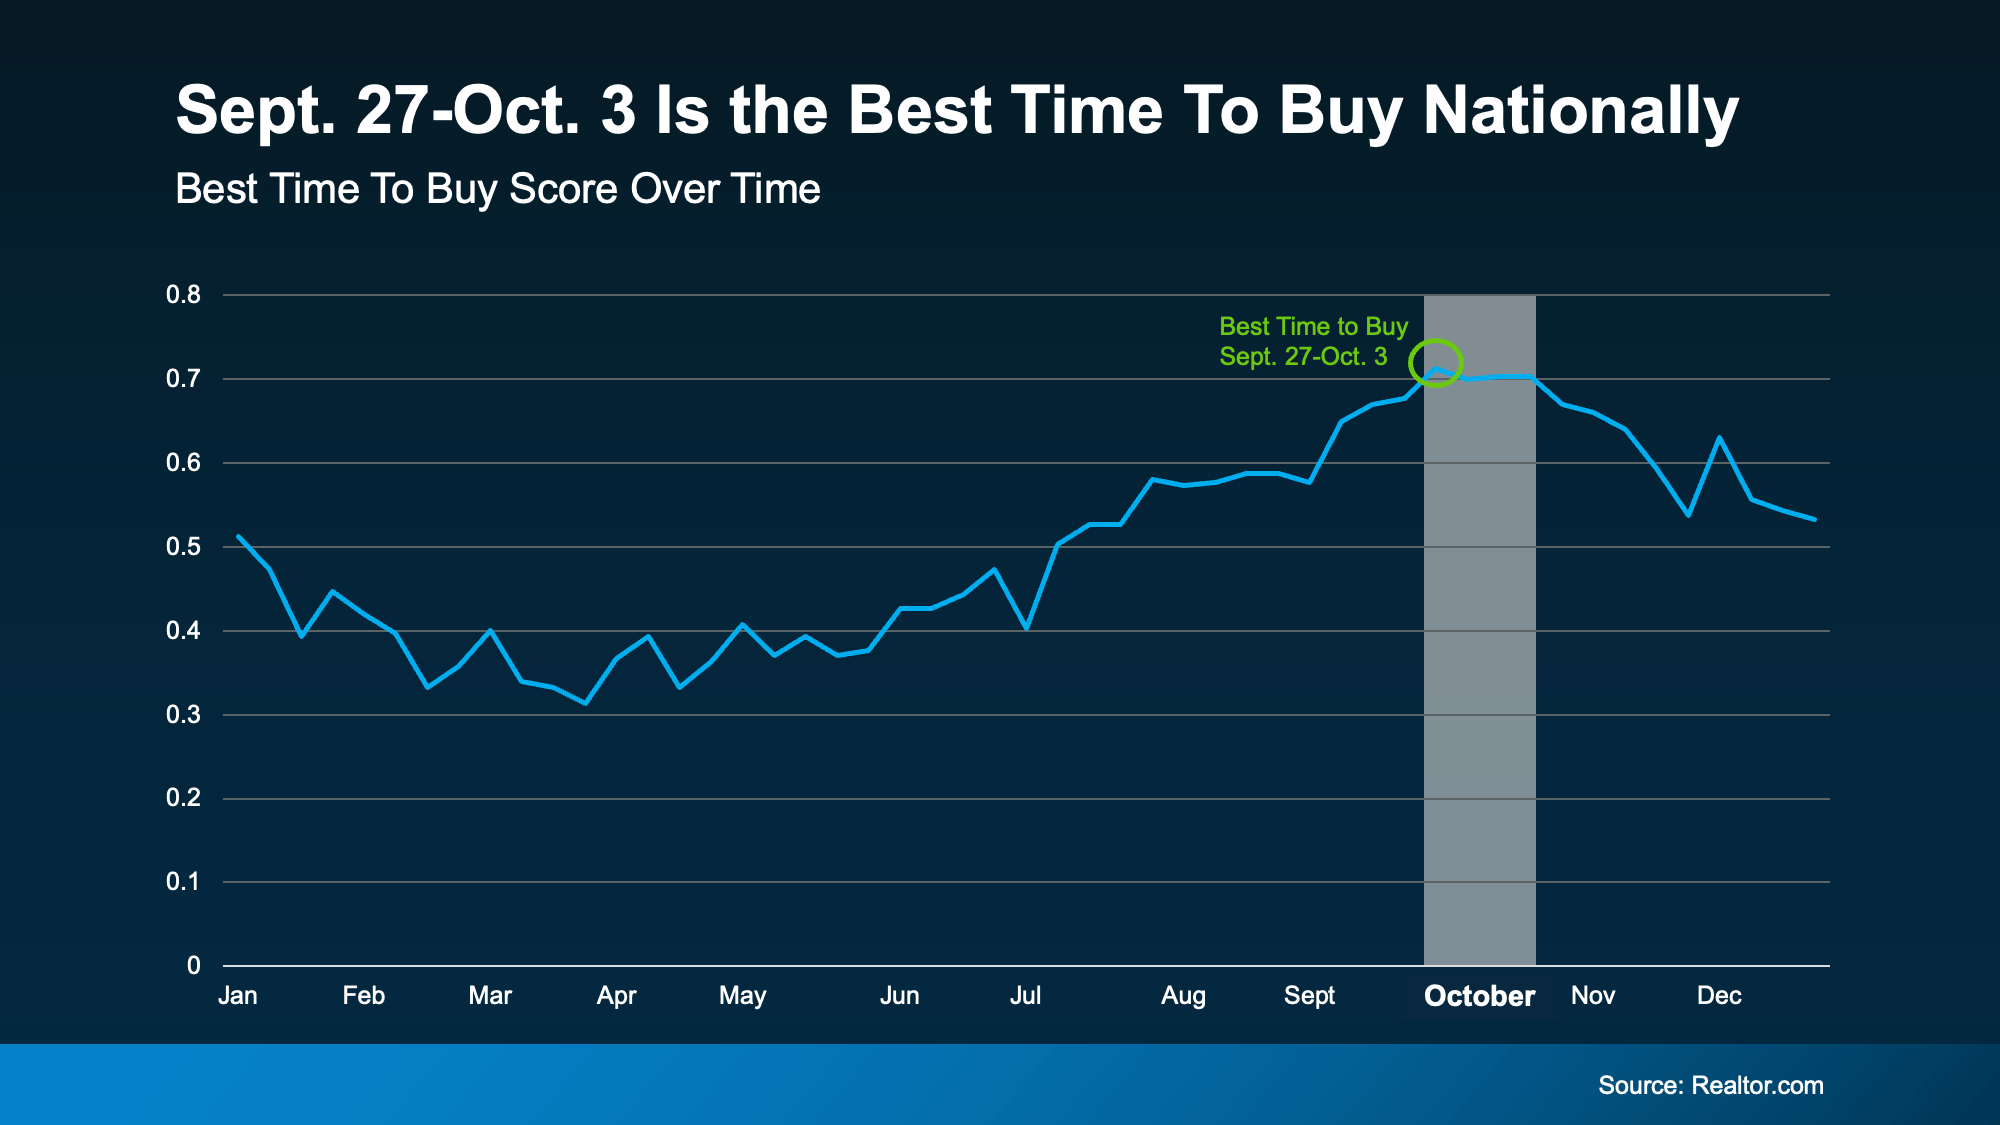
In fact, Realtor.com says 42 of the 50 largest metros see their best week to buy fall sometime during October. So, don’t feel like you have to rush to hit one specific date. Use the time now to get things lined up, then jump in when the timing is right for you. As Guaranteed Rate explains:
“The best time to buy a home depends on your needs. Certain seasons can give you an advantage when starting your homebuying journey.”
Bottom Line
If you want to buy a house this year, there’s still a way to make it happen, even with today’s rates. This fall gives you the chance to get some of the best seasonal perks the market has to offer.
Want help figuring out when those advantages typically show up in your market?
Have a quick conversation with a lender and a local agent about how your market works and the steps you’ll need to take to get ready.
For most first-time buyers, the hardest part of buying a home is making the numbers work. You budget, you save, and the finish line still feels far away.
But your salary is only half the equation. Where you live shapes what you can afford just as much. And if you can work remotely, you have an advantage a lot of buyers don’t.
You’re not tied to living where the jobs are, so you can look where your money goes further.
Where You Work Doesn’t Have To Dictate Where You Live
Remote job openings are on the rise. According to FlexJobs, remote job postings climbed 22% from the quarter before. That’s the second quarter in a row of double-digit growth.
More remote roles mean more people can choose a home base around the life they want to build. As Forbes puts it:
“Remote employees, freelancers, consultants, entrepreneurs, and business owners have the flexibility to choose a home base based on the life they want to build, whether that means more space, a lower cost of living, better access to nature, or simply somewhere new.”
And you can use that freedom to look somewhere more affordable.
Your Paycheck Goes Much Further in Some States
Your cost of living – what you spend on housing, groceries, utilities, and the rest of daily life – varies a lot from one state to the next. In some, according to data from Extra Space, it runs far enough below the national average to change what you can afford (see map below):
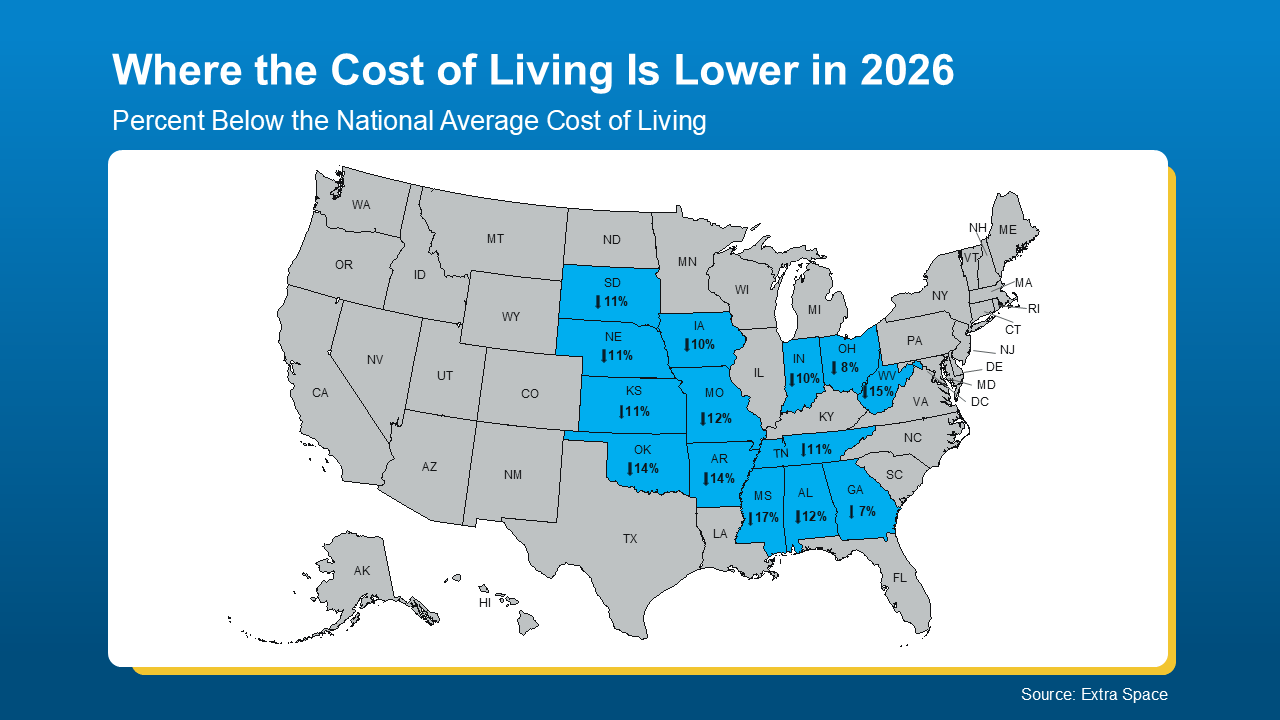 Take Mississippi, for example, where the cost of living sits about 17% below average, or West Virginia at roughly 15% below. When day-to-day life costs less, you can put more of your income toward your goals, homeownership included. Relocate Right describes it this way:
“Remote work has fundamentally changed the calculus of where to live. When your employer is in San Francisco, but you can work from anywhere, the question is no longer ‘where are the jobs’ but ‘where does my salary go furthest and what kind of life can I build.'”
For a first-time buyer, working remotely could be a chance to put down roots and finally buy. Because with that kind of flexibility, you get to choose where to live and which places work best for your life and goals.
What To Weigh Before You Go
A lower cost of living is a great start. But it’s also important to consider the things a budget spreadsheet won’t show you, because a place can look like a great fit on paper and still not feel like home.
-
Is the internet fast and steady enough to do your job without interruptions?
-
Will it be easy to make friends and settle into a routine once you arrive?
-
Does it have the amenities you want, like public transportation or decent takeout?
This is where a local real estate agent comes in. They can help you weigh a big move against a nearby one, because every state has more affordable pockets. Sometimes they’re closer than you think.
An agent will know which neighborhoods fit your budget and have the features you’re after, whether that’s walkability, good restaurants, parks, or a nearby farmer’s market.
Bottom Line
With remote work, where you live can be your decision instead of your employer’s. And that puts more affordable places within reach.
Want to explore where that could take you? Connect with a local real estate agent to see what’s possible.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

Why So Many Sellers Are Cutting Their Price Right Now

There Are 4 Types of Housing Markets Right Now. Which 1 Are You In?


-
 Affordability4 weeks ago
Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.
-
 Affordability4 weeks ago
Why Buyers Shouldn’t Overlook a Fall Move
-
 Affordability4 weeks ago
Think New Homes Cost More? Not Right Now.
-
 Affordability3 weeks ago
Remote Work Could Be Your Affordability Answer
-
 For Buyers3 weeks ago
Data Centers Are Moving Closer to Homes. What Does That Mean for You?
-
 Agent Value3 weeks ago
The Housing Market Split in 2. Which Side Is Your House On?
-
 Agent Value2 weeks ago
Selling This Fall? You Haven’t Missed Your Window
-
 For Sellers2 weeks ago
Selling This Fall? You Want To Get These 4 Things Right.
You must be logged in to post a comment Login