For Buyers
Mortgage Rates Hit Lowest Point So Far This Year
If you’ve been holding off on buying a home because of high mortgage rates, you might want to take another look at the market. That’s because mortgage rates have been trending down lately – and that gives you a chance to jump back in.
Mortgage rates have been declining for seven straight weeks now, according to data from Freddie Mac. And the average weekly rate is now at the lowest level so far this year (see graph below):
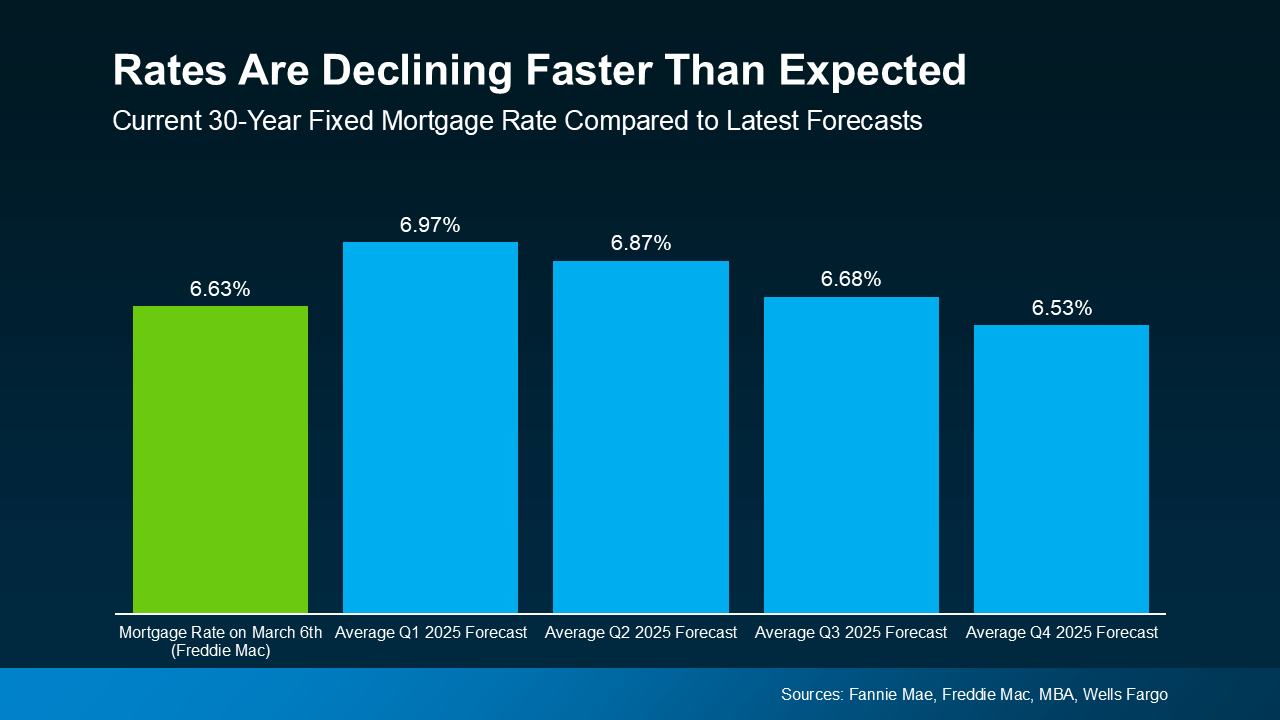
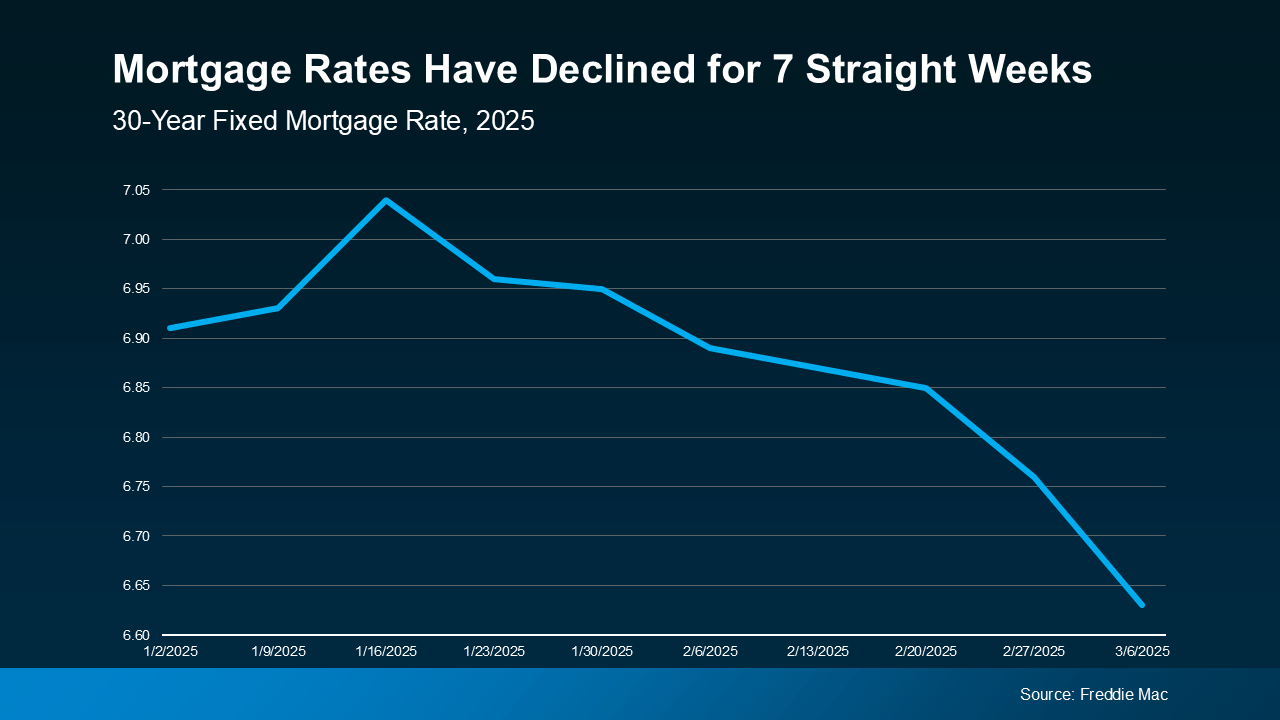 While that may not sound like a significant shift, it is noteworthy. Because the meaningful drop from over 7% to the mid-6’s can change your mindset when it comes to buying a home. Especially when the forecasts said we wouldn’t hit this number until roughly Q3 of this year (see graph below):
Why Are Rates Coming Down?
According to Joel Kan, VP and Deputy Chief Economist at the Mortgage Bankers Association (MBA), recent economic uncertainty is playing a role in pushing rates lower:
“Mortgage rates declined last week on souring consumer sentiment regarding the economy and increasing uncertainty over the impact of new tariffs levied on imported goods into the U.S. Those factors resulted in the largest weekly decline in the 30-year fixed rate since November 2024.”
And the timing of this recent decline is great because it gives you a little bit of relief going into the spring market. Just remember, mortgage rates can be a quickly moving target, so you should expect some volatility going forward. But the window you have as they’re coming down right now might be the sweet spot for your purchasing power now.
What Lower Rates Mean for Your Buying Power
Even small changes in rates can make a difference to your monthly payment. Here’s how the math shakes out. The chart below shows what a monthly payment (principal and interest) would look like on a $400K home loan if you purchased a house when rates were 7.04% back in mid-January (this year’s mortgage rate high), versus what it could look like if you buy a home now (see below):
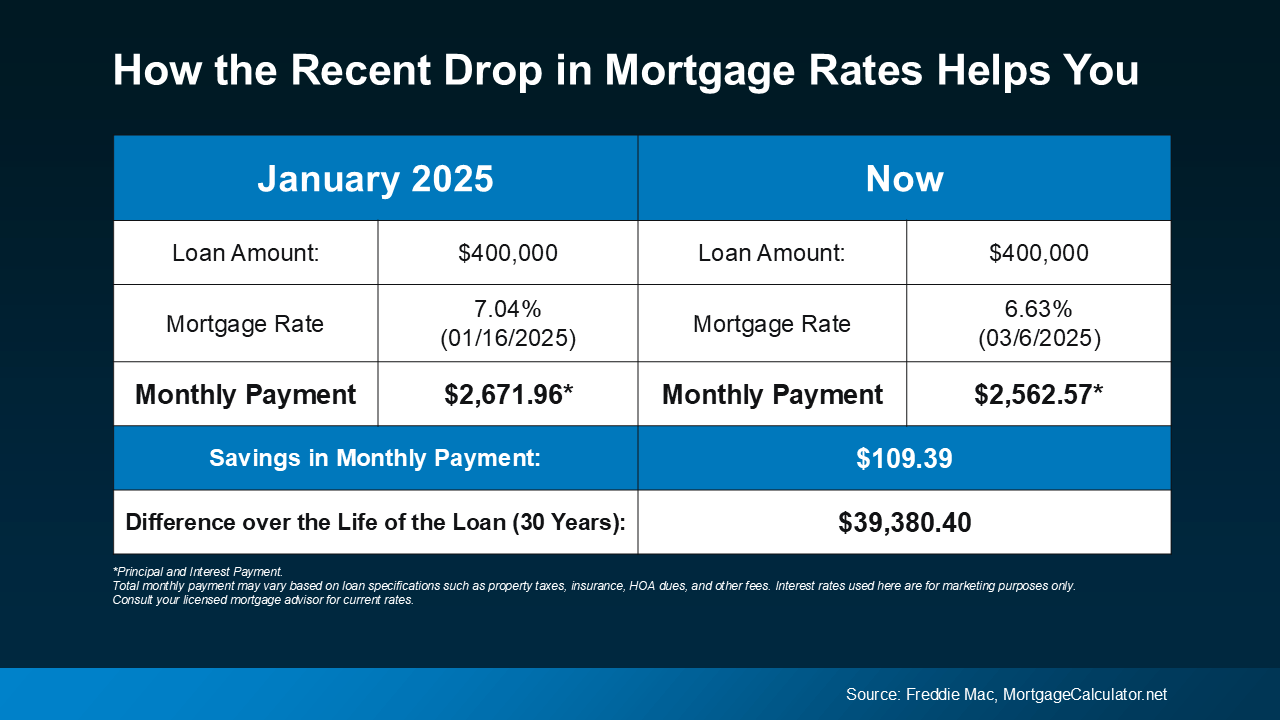 In just a matter of weeks, the anticipated payment on a $400K loan has come down by over $100 per month. That’s a significant savings. When you’re making a decision as big as buying a home, every bit counts.
Just remember, shifts in the economy drove rates down faster than expected. But that can change, making rates volatile in the days and months ahead. So, if you’re waiting for rates to fall further before you buy, think hard about the current window of opportunity if you’re ready to act.
Bottom Line
Mortgage rates have dipped, giving buyers a bit more immediate breathing room. If you’ve been waiting for rates to ease before jumping in, this could be your window.
Would a lower monthly payment make buying a home feel more doable for you?
Connect with an agent to break down the numbers and find out.
You’ve been waiting for something to change before you buy. It just might not be the thing you expected…
While everyone’s paying attention to mortgage rates, only the savviest buyers know that the changing season can start tipping things in their favor.
Because every fall, buyers tend to get more to choose from, better prices, and more room to negotiate. And that’s why Hannah Jones, Senior Economist at Realtor.com, says:
“We always see that the best time to buy window usually falls in the early fall around October.”
And that’s exactly why, if you’ve been waiting for a better moment to buy, this season may be worth a closer look – even with rates where they are.
1. There Are More Homes To Choose From
One of the biggest frustrations buyers have had over the past few years has been a lack of choices. Fall tends to help with that.
Based on seasonal trends, Realtor.com data shows there are typically more homes available for sale in September through November than during any other season of the year (see graph below):
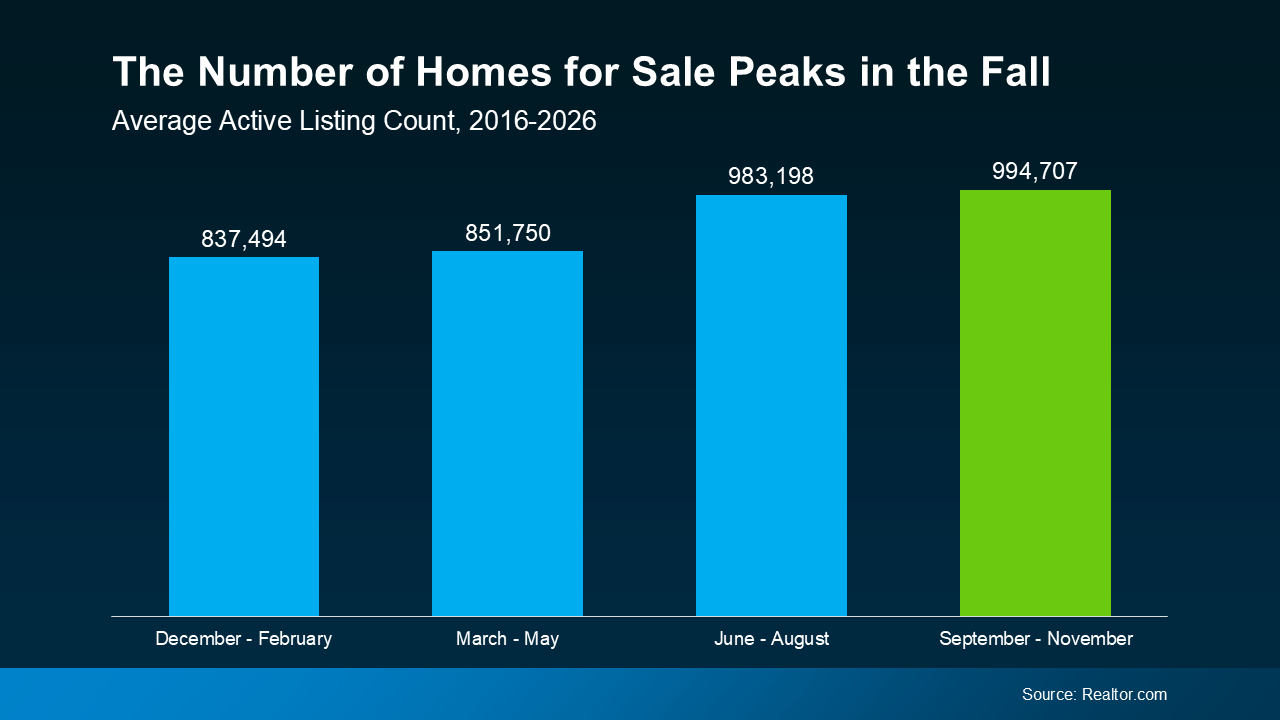 Why does this happen? Homes that hit the market in spring and summer don’t all close right away. Some sit. New listings keep coming. And inventory builds as the year goes on.
By fall, you’re looking at the largest pool of available homes all year. That makes it easier to find one that works for your needs and your budget. And if anything, this should be more true this year. Rates that are higher for longer tend to help inventory grow even more.
More choices can mean fewer compromises. You’re more likely to find the right home, not just the one that happens to be available.
2. Asking Prices Start To Drop
Having more choices is great. But if every home is still priced too high, that only gets you so far. That’s where fall’s second advantage kicks in: asking prices start their seasonal decline.
HousingWire data shows this trend over time (see graph below):
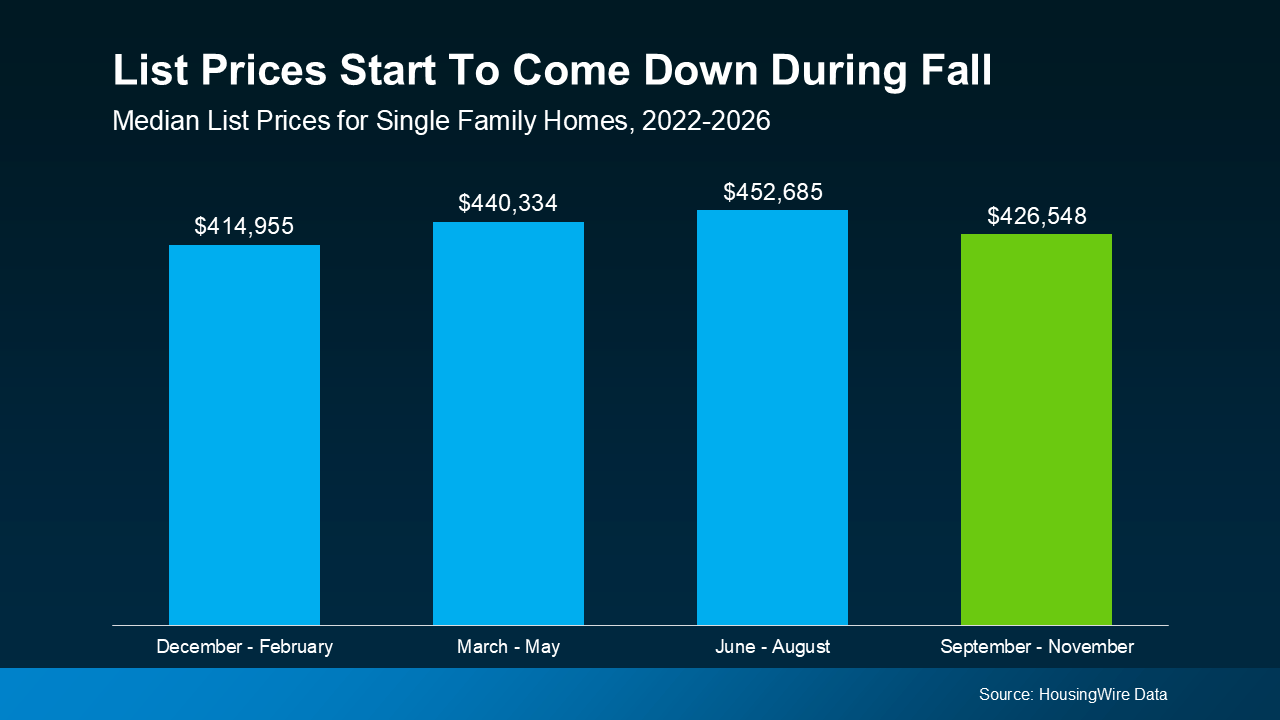 It works like this. Spring and early summer are when sellers feel the most confident because that’s when demand is typically strongest. So, many homeowners price their homes higher during those periods because of the uptick in demand.
But every year, like clockwork, that dynamic starts to change by fall. Buyer activity slows down as the weather cools off. So, sellers have to price a bit lower to try to draw buyers in. And that’s good for your bottom line.
3. More Sellers Are Willing To Negotiate
But fall doesn’t just bring more choices and lower asking prices. It also brings more sellers who are increasingly motivated to get a deal done.
You can see it in the data. Most years, fall is when price cuts peak according to Realtor.com data (see graph below):
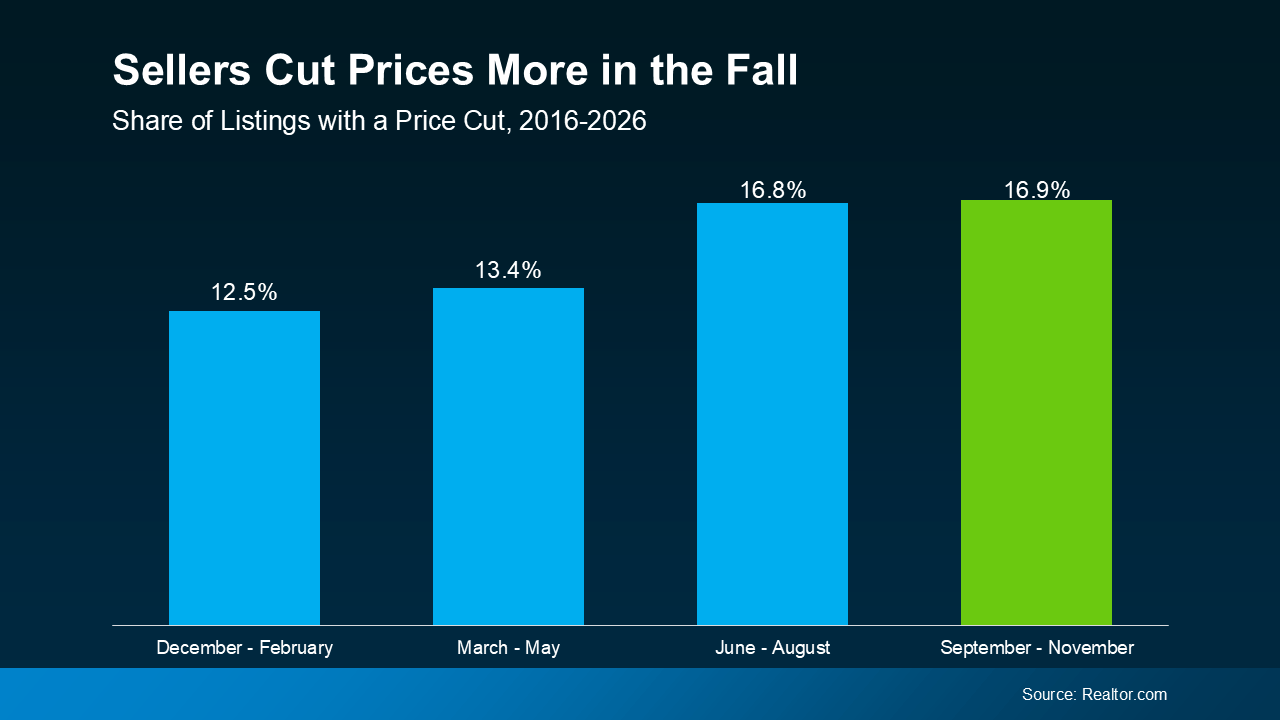
While it’s not a big difference from summer, this fall you’ll have more negotiation power than you’d have if you wait until the first half of 2027. Here’s why.
If a home is on the market in the fall, many sellers are eager to get it sold before the holidays. And since there are usually fewer buyers active in the fall, that often leads to another opportunity to snag a better deal. As the National Association of Realtors (NAR) explains:
“Less competition can lead to better deals. While homes are not selling as fast as during the summer, sellers may be more willing to negotiate.”
Even a small seller compromise here can make a meaningful difference for you.
As an example, a 5% price drop on a $500,000 home is $25,000. That could mean you end up borrowing less, keeping more money in savings, having room in the budget for updates after you move in, or simply making the monthly payment feel more manageable.
Bottom Line
Of course, every market moves a little differently. But here’s what doesn’t change: Fall consistently buyers. More homes. Lower asking prices. Motivated sellers.
If you’ve been waiting for your search to feel a little more doable, this season may be worth another look.
Have a quick conversation with a local agent about what’s happening in your market. That way you can find out whether this fall gives you opportunities you may not have had a few months ago.
Most people think a newly built home costs more than an existing one. But right now, that’s actually backwards. Newly built homes are more affordable than existing ones in a lot of markets. And that’s because builders are cutting prices and stacking on incentives to try to keep their inventory moving.
Here’s why that’s really important for any would-be homebuyer to know.
Newly Built Homes Are the Better Deal Right Now
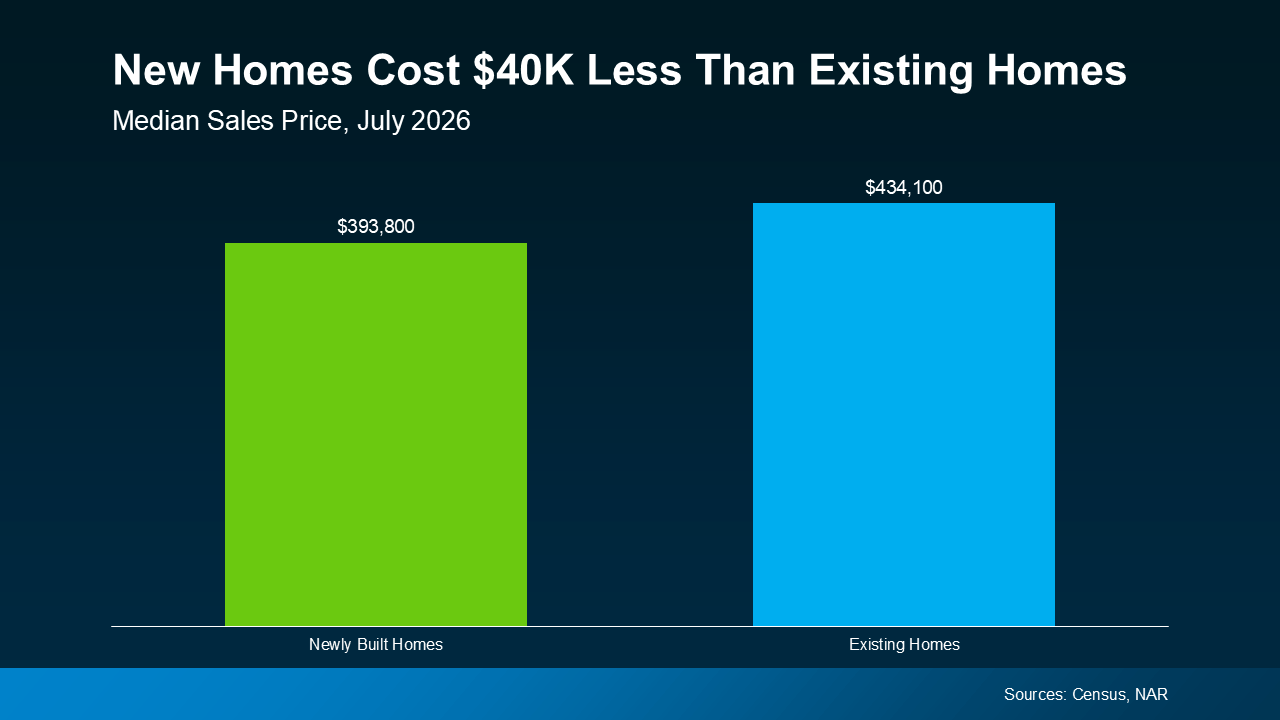
According to the latest data from the Census and the National Association of Realtors (NAR), a newly built home now typically costs about $40,000 less than an existing one (see graph below):
 Builders aren’t like homeowners who can wait for the right offer. Unsold homes cost them money as long as they sit empty. So, builders cut prices and add incentives to keep them moving. That trend has carried into August. NAHB’s latest numbers:
-
35% of builders cut prices, with an average reduction of 6%.
-
63% offered incentives like covering closing costs or buying down your mortgage rate.
And those incentives can make a real dent in what you pay upfront and every month after. Plus, since everything is new and many builders offer warranties, you could save on home maintenance costs too. And with affordability where it is, every dollar counts.
So, don’t cross new builds off your list just yet. Yes, you may think they cost more, but that’s not always the case.
If you can get brand-new everything for less than buying an existing home, isn’t that at least worth looking into?
Don’t Let the Builder Pick Your Teammate
But before you tour a single model home, there’s one thing worth figuring out first – who’s actually working for you once you walk through that door.
That friendly rep in the builder’s sales office works for the builder, not you. Their job is to protect the builder’s bottom line, not yours. Your own agent flips that.
They know the local market, so they can tell you if the builder’s price and upgrades stack up against other options nearby. They’ll negotiate on your behalf, whether that’s a lower price, free upgrades, or a rate buydown.
A good agent will also push for a home inspection. Builders won’t always bring it up, but it’s a step you shouldn’t skip, even on a new build. And your agent will be in your corner, so you know what you’re buying and get the best deal possible.
Bottom Line
New homes may actually cost less than an existing home right now. And that’s opening up a window for you to get brand-new for less.
If you want a list of new home communities near you that are currently offering incentives or doing price cuts, reach out to a local agent. When you have your own agent, you’ll have someone in your corner helping you get the best deal possible.
Lately, headlines have floated an eye-catching idea about tapping into your 401(k) to cover a down payment on a home. Maybe you’ve caught the buzz and wondered whether that money could get you into a home faster, especially with affordability as tough as it is.
Here’s what you need to remember. Pulling from your retirement savings is a big decision, so take time to weigh all your options first and be sure to talk with a financial expert before you do anything.
Why Dipping into a 401(k) Can Be Tempting
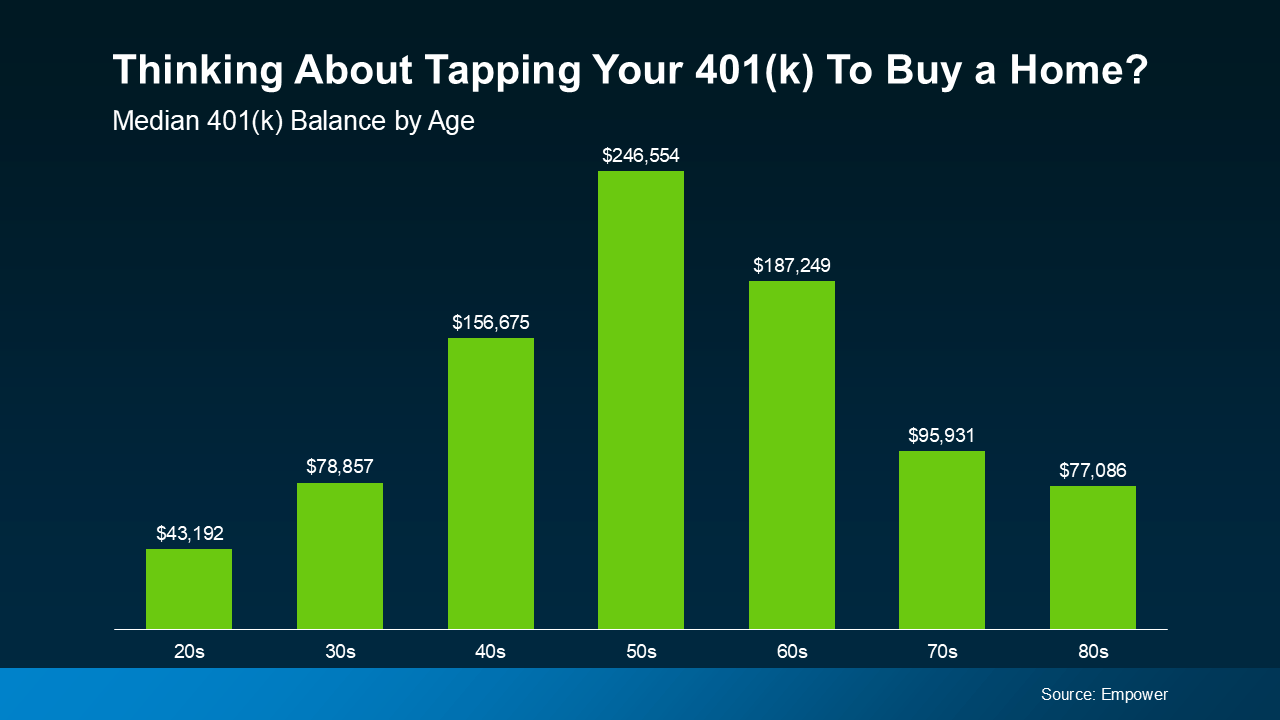
Data from Empower shows many Americans have built up considerable retirement savings. The median 401(k) amount for anyone in their 40s-60s is six figures (see graph below):
 And when you’ve got a good chunk saved and your dream home is right there, reaching for it can feel like an easy call.
But dipping into your retirement savings to buy a home could cost you a penalty and set back your finances later on. That’s why it’s a good idea to explore other options for your down payment first. As Redfin says:
“If you’re struggling to save enough for a down payment, you may be wondering if tapping into your 401(k) is the right option. While it’s possible, doing so comes with significant risks, like early withdrawal penalties and lost investment growth.“
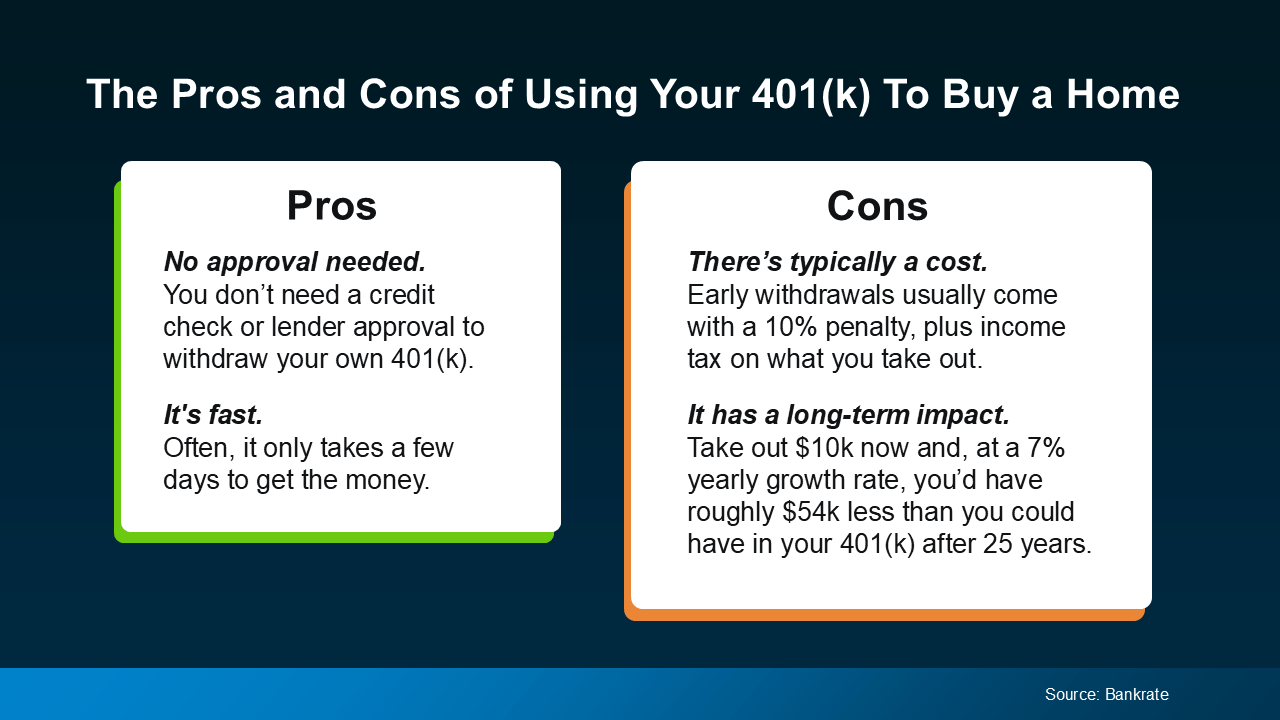
Before you decide, have a financial advisor help you compare the upsides to the risks. Bankrate points to a few of each (see visual):
Other Options Worth Exploring First
Your 401(k) isn’t the only way to finance a home purchase. Redfin outlines a few other options to look into before you decide what to do:
-
Low and No-Down Payment Loans: FHA loans, for example, allow qualified buyers to put down as little as 3.5% of the home’s price, depending on their credit scores.
-
Down Payment Assistance Programs: Many national and local programs can help reduce what you pay toward your down payment or closing costs.
Make a Plan Before You Make a Move
No matter which route you take, talk with a financial expert first. The buyers who come out ahead build a solid plan with the right professionals before starting their journey to homeownership. As NerdWallet puts it:
“Even if you’re convinced a 401(k) loan is the way to go, it’s important to understand the risks at the outset.“
Bottom Line
Affordability is definitely a challenge, but that doesn’t mean tapping your 401(k) is your only way in if you want to buy.
If you’re considering using your 401(k) savings for a down payment, weigh all your options and talk with a trusted financial advisor before you make any decisions. They’ll help you make a plan to fit your goals and your budget.

Why Buyers Shouldn’t Overlook a Fall Move

Think New Homes Cost More? Not Right Now.

Thinking About Tapping into Your 401(k) To Buy a Home? Read This First.


-
 Buying Tips3 weeks ago
Who Has the Upper Hand in Today’s Housing Market?
-
 Affordability4 weeks ago
The Case for Putting 20% Down on Your Next Home
-
 Affordability4 weeks ago
Here’s Why Mortgage Rates Are What They Are Right Now
-
 Downsize3 weeks ago
The Kind of House Buyers Are Willing To Pay More For
-
 Downsize3 weeks ago
One Number Could Change Everything About Your Next Move
-
 For Buyers3 weeks ago
Higher Rates Could Actually Help Housing Supply – Here’s How.
-
 Agent Value2 weeks ago
Most Home Sales Close – Here’s How To Keep Yours on Track
-

 For Buyers2 weeks ago
Worried About a Housing Crash? The Numbers Tell a Calmer Story.
You must be logged in to post a comment Login