For Sellers
Why You May Want To Cash in on Your Second Home
Ryan Serhant, CEO of SERHANT, says there isn’t just 1 housing market right now. There are really 4: cash buyers, buyers who need a mortgage, homeowners with low mortgage rates, and builders.
Today, let’s zoom in on the 1st group – cash buyers.
According to the National Association of Realtors (NAR), 27% of homes sold in September were bought with all cash. That’s more than 1 in 4 buyers. And that’s a pretty big number, especially when so many people are struggling with affordability.
So where is all that cash coming from? When you hear a number like that, it’s easy to picture wealthy investors buying up houses left and right. But that’s not necessarily the case. Some of those cash buyers are actually homeowners who’ve built up enough equity to buy their next home outright.
Here’s what you should know about who’s paying cash and what that really means for the market.
Who’s Paying Cash?
Cash buyers tend to fall into a few groups, according to NAR:
-
Homeowners who sold a house and are using that money to buy their next one
-
People buying a 2nd home
-
Investors
So, it’s not all those big investors social media talks about. That 1st group may include people a lot more like you. Here’s how. According to Cotality, the average homeowner with a mortgage has about $310,000 in equity.
That’s a big deal right now. Many homeowners feel stuck because they don’t want to give up the low mortgage rate they have today. But once they learn they may have enough equity to move and pay cash for their next home, today’s rates don’t matter nearly as much. Because buying in all cash means…
-
No monthly mortgage payment
-
No need to borrow at today’s mortgage rates
-
No loan approval process, so you may be able to close faster
And even if the equity won’t cover the whole purchase, putting more of it toward the next home means borrowing less. That can mean a smaller monthly payment, too.
But cash buyers like this are more common in some places than others. And how big of a segment of your local market this is, is going to depend on where you live.
For example, Realtor.com data shows cash buyers made up almost 47% of sales in Mississippi and 46% in Montana earlier this year (see map below).
Where does your state fall?
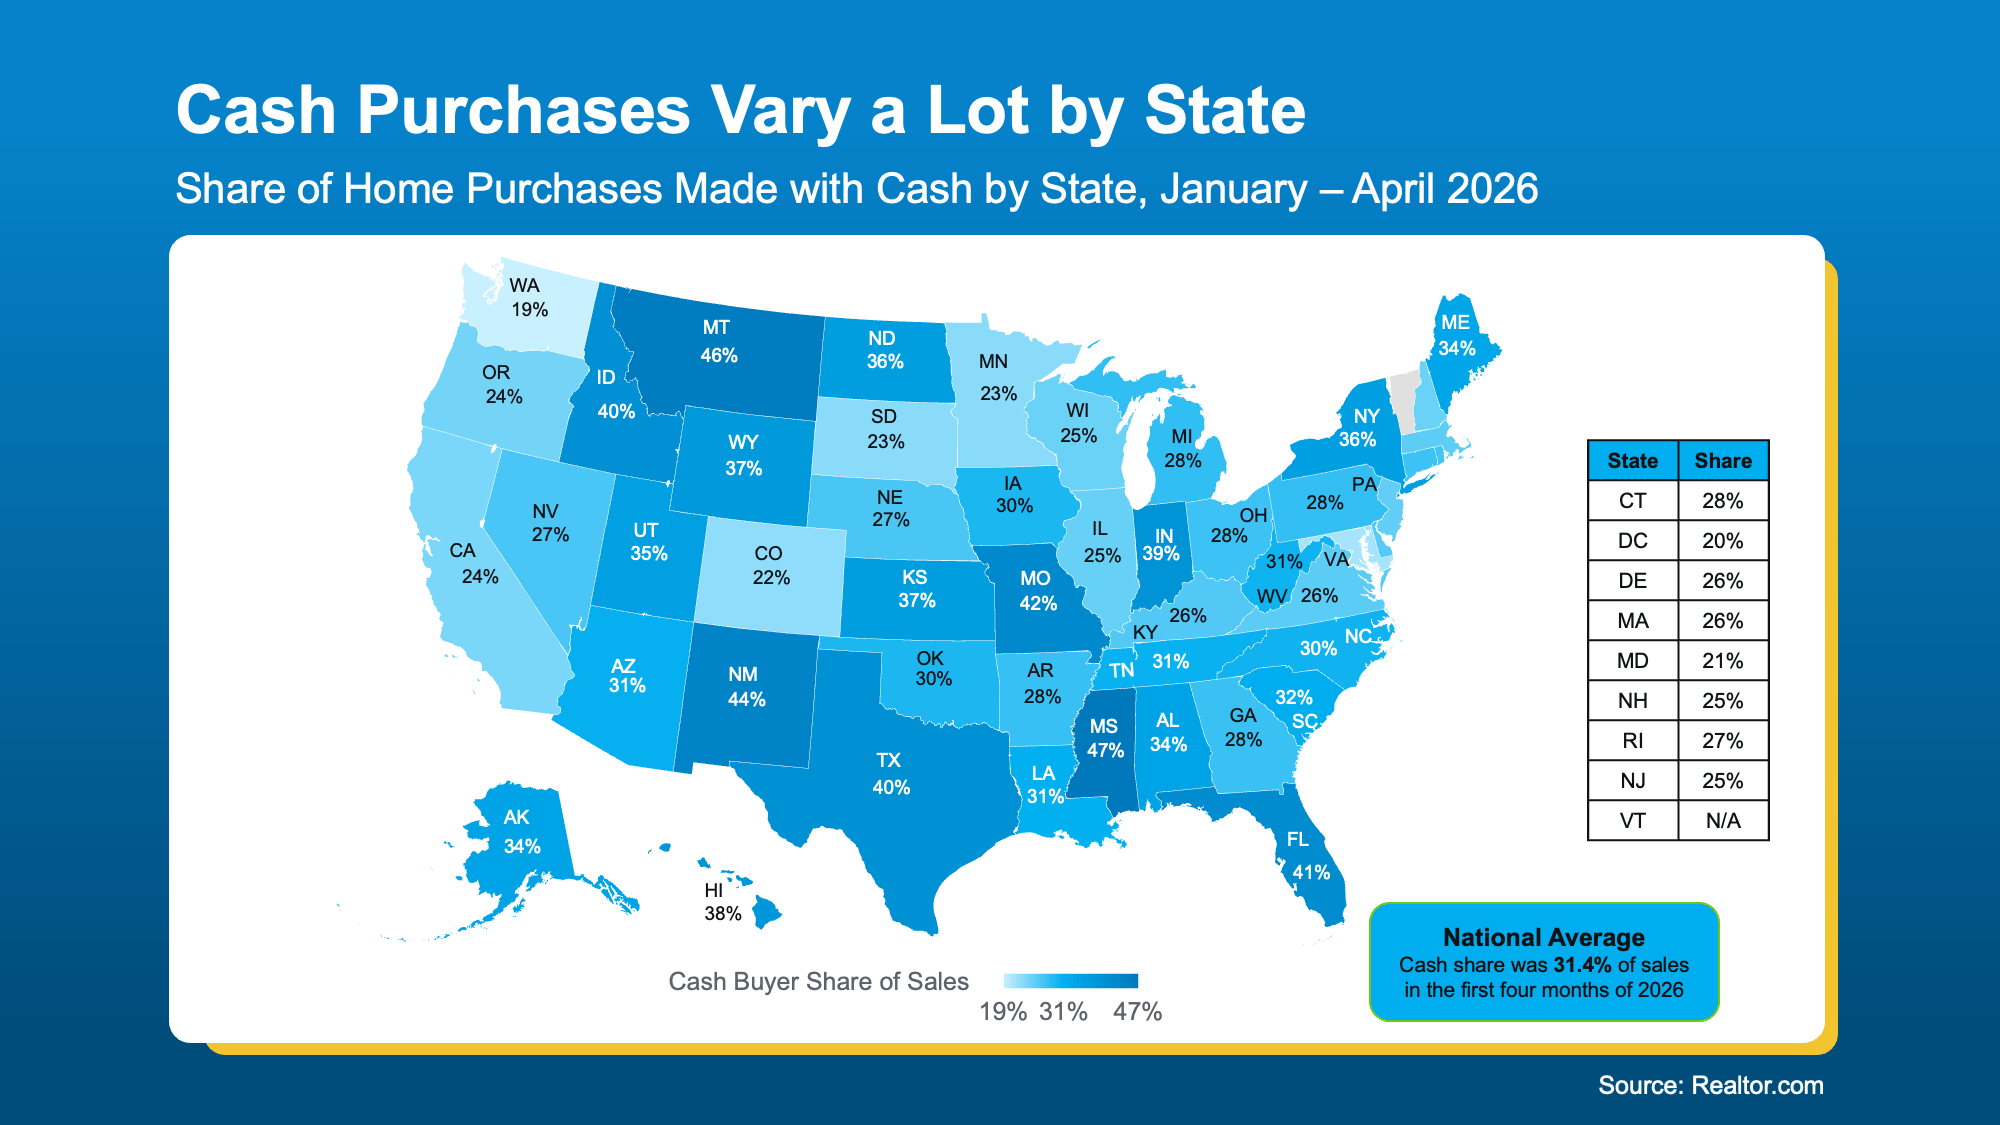
According to Realtor.com, the states with the most cash buyers reflect “a mix of affordability, wealth and buyer demographics.” Think places with lower home prices, or lots of retirees and 2nd-home buyers.
So, depending on where you live, you may see a lot more (or a lot fewer) cash buyers than the national number suggests. An agent who knows your area can tell you who’s actually buying near you.
Most Buyers Are Still Using a Mortgage
And if all of this has you thinking everyone’s paying cash, they’re not. If you’re planning to buy and need a mortgage, you’re actually in the majority.
Based on NAR’s numbers, nearly 3 out of 4 home purchases still involve financing. And for homes priced between $200,000 and $750,000, only about 1 in 5 sold for cash, according to Realtor.com (see graph below):
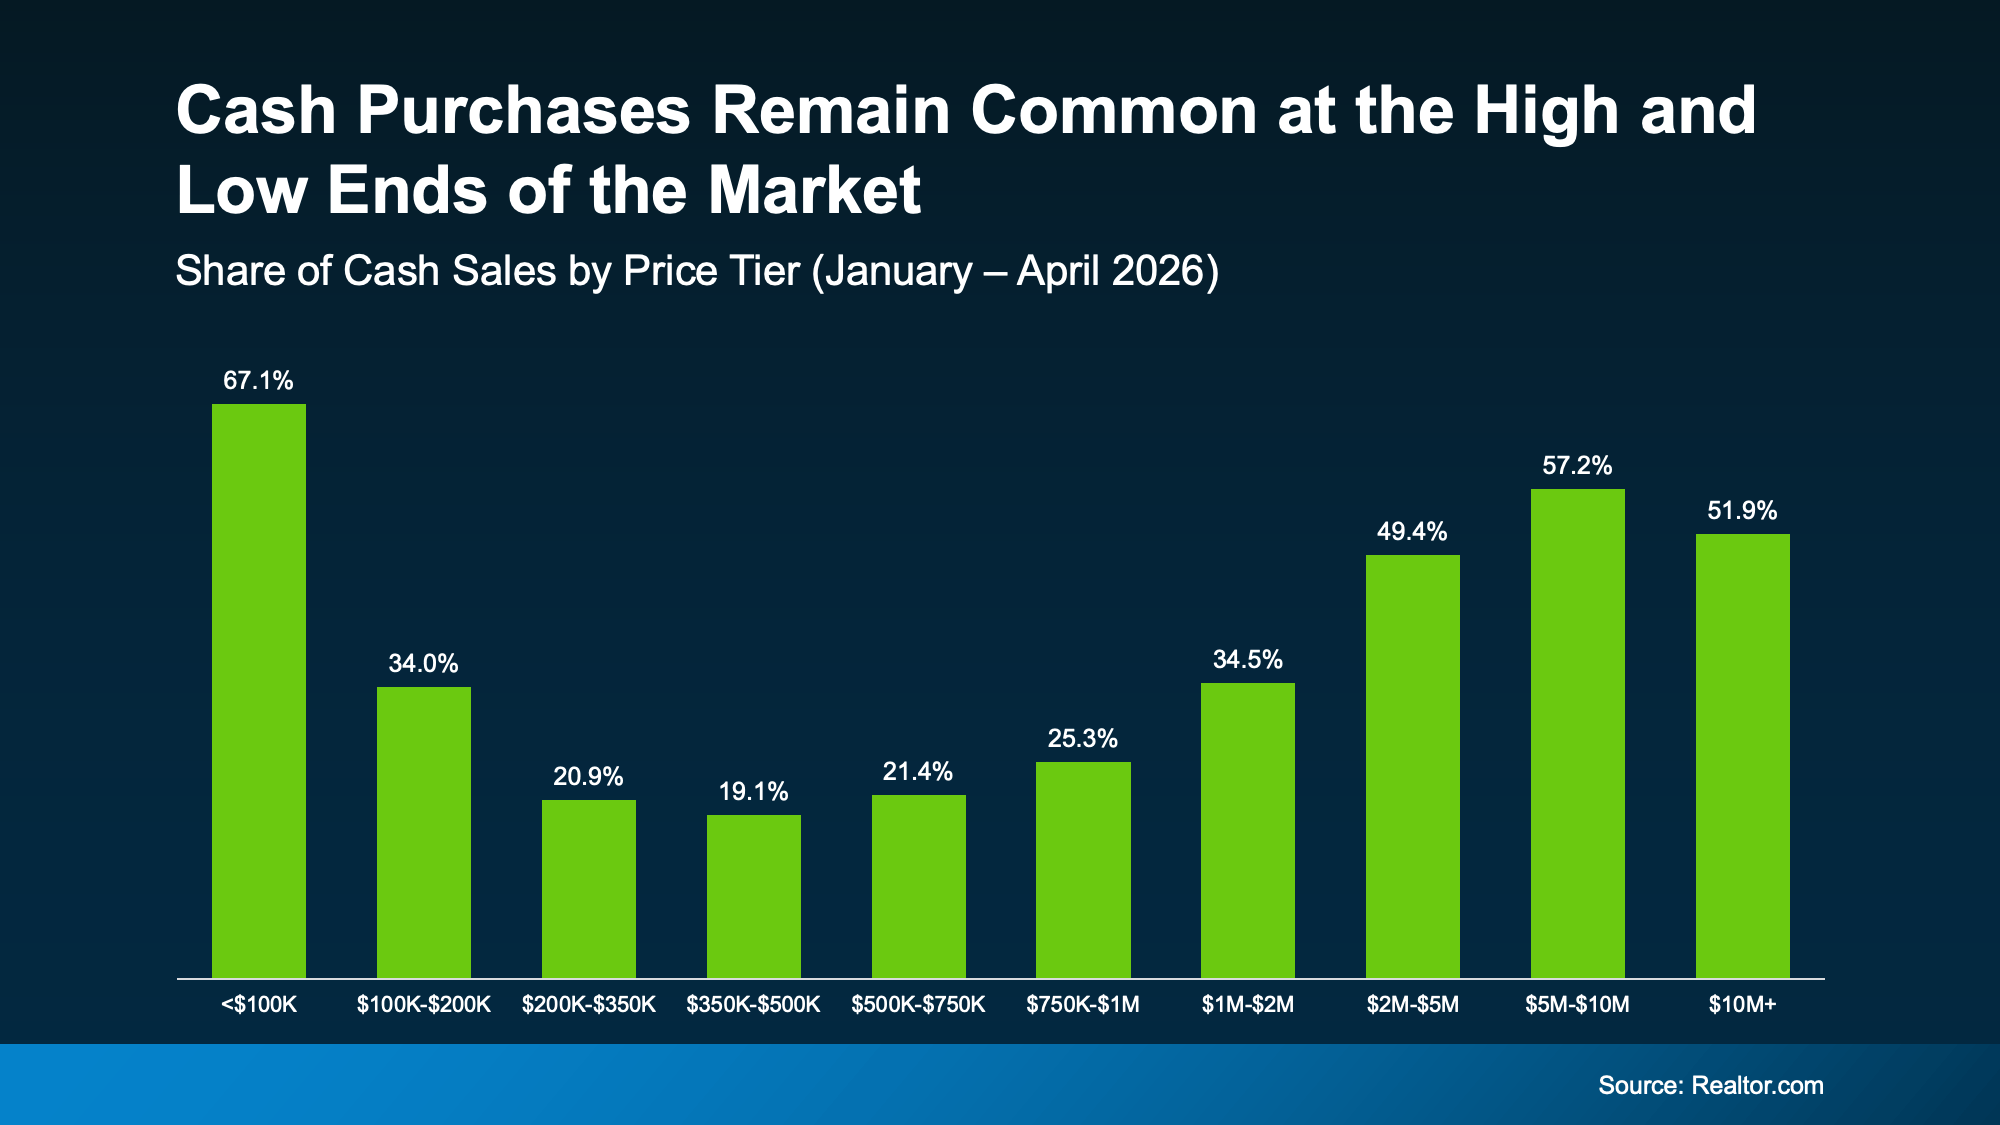
That means most people buying in that price range are financing their purchase, too. So, there’s no need to assume you’re at a disadvantage just because you’re using a loan.
Cash Buyers and Your Move
So, what does all this mean for you? Maybe more than you think.
If you already own a house, you may have enough equity to make your next move more affordable than you realize. And if you’re buying with a mortgage, remember, you’re in good company. Most buyers are financing their purchases, too.
The takeaway? Don’t make assumptions about what’s possible based on how other people are buying homes. What really matters is your equity, your budget, and what’s happening in your local market.
Bottom Line
Cash buyers are a meaningful part of today’s market, but they aren’t the whole market.
Whether you’re hoping to put your equity to work or you’re buying with a mortgage, a local real estate agent can help you see how much equity you have, who’s buying in your area, and what that means for your next move.
Selling your house is a big step, and you want it to go smoothly. And with houses taking a little longer to sell these days, renting it out might start to sound like a nice backup plan.
But the reality is, while renting can work well for some people, it’s also a big commitment. So before you decide, it helps to see the whole picture first.
Why Some Sellers Are Deciding To Rent Instead
Lately, some sellers are choosing to hang on to their houses and rent them out instead. According to Parcl, around 9% of homes for rent right now were previously up for sale.
Here’s why.
Some homeowners put their houses on the market expecting a faster process than they got or a certain price buyers didn’t respond to. And when things didn’t go exactly as planned, they decided to rent instead. As Kara Ng, Senior Economist at Zillow, explains:
“Bargaining power is tilting toward buyers and homes are taking longer to sell, making renting out a property one way to buy time rather than compete aggressively on price.”
But here’s the important distinction. Just because some sellers are choosing to rent doesn’t mean selling isn’t working. In many cases, the difference comes down to how well a house is priced, prepared, and marketed for today’s buyers.
Parcl data shows where these “accidental landlords” – owners who planned to sell but decided to rent instead – are most common (see graph below):
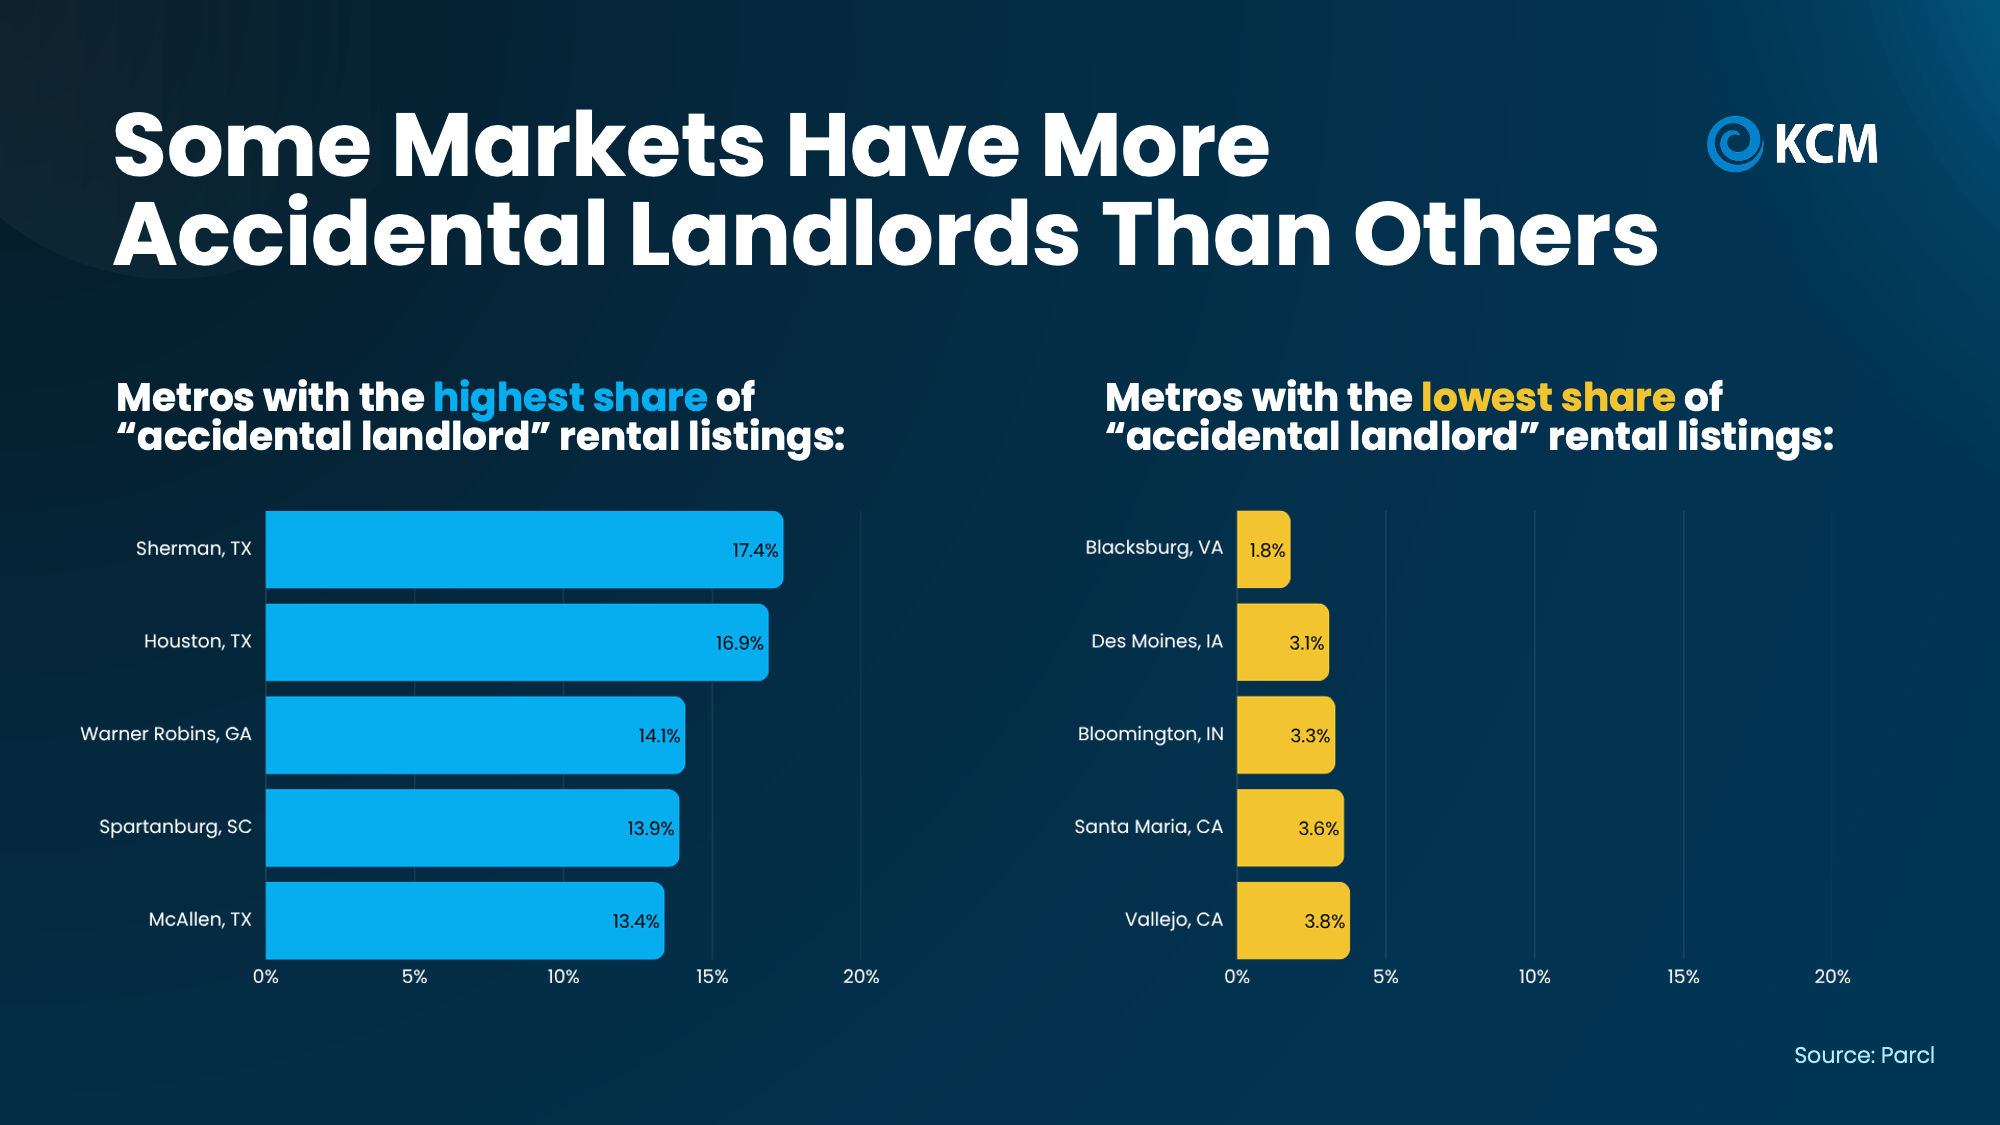
They make up around 17% of homes for rent in places like Sherman and Houston, TX, but less than 4% in markets like Des Moines, IA and Bloomington, IN.
That’s a pretty big difference. And it shows why you have to know what’s happening in your neighborhood. Your market, your asking price, and your strategy all play a role in how your sale goes.
A local agent can show you how houses like yours are selling, what strategies work best, and help you weigh your options – not to push you to sell, but so you at least have the full picture based on today’s market. And part of making an informed decision is understanding what renting your house would actually take.
What Being a Landlord Actually Looks Like
While renting might sound like easy passive income on paper, in practice, it’s a hands-on job with rules to follow. As Invest West Management puts it:
“Even if you never intended to become a landlord, the law still sees you as one — and you must meet all legal obligations that come with that role. This often includes registering the tenancy, providing tenants with certain disclosures, and ensuring the property meets safety standards.”
You’d also be the one chasing missed rent payments, fixing damage between tenants, and covering unexpected repairs. Not to mention fielding weekend calls about leaky dishwashers or broken AC units.
There are expenses beyond regular maintenance and repairs, too. According to Bankrate, these are a few of the biggest:
-
Insurance premiums (landlord insurance typically costs about 25% more than a standard homeowners policy)
-
Management fees (if you hire a property manager, they usually charge around 10% of the rent)
-
Gaps between tenants, when you pay the mortgage without rental income
How To Give Your House a Strong Start
If you want to be a landlord and you’re prepared for the responsibility, renting may be a great fit. But if you’d really rather sell, don’t let today’s market convince you that you can’t.
A great agent can make it happen. The key is having an open conversation up front with your agent about pricing and how to market your house. Nailing those details from day 1 helps your house make a great first impression, so renting doesn’t have to be your fallback.
Bottom Line
Renting can be a good fit for the right person with the right house, but it isn’t the only option. A smart sales strategy can help your house stand out to buyers from day one.
So, if you’re on the fence, a local real estate agent can help you compare what selling and renting would each look like for you.
Whether you own a house already or you’re looking to buy one, you probably care about home prices. But it’s not always easy to figure out what’s really happening right now, especially if you look at the headlines.
One says home prices are falling. The next says they’re still climbing.
So, which one’s right? It comes down to where you live.
What’s Really Going on with Asking Prices
Part of the confusion out there may be based on what’s happening to asking prices and how the media is talking about it. They’re calling attention to how asking prices are falling, but don’t give the full context or say that seasonality is at play. So here it is.
Right now, there are more homes on the market than at any other time since November 2019. And with mortgage rates rising since the spring, those homes are taking a little longer to sell. One way to help a home sell quickly in that environment is to have a lower asking price.
According to HousingWire Data, the median asking price is down from $449k in early August to $435k just 2 months later (see graph below):
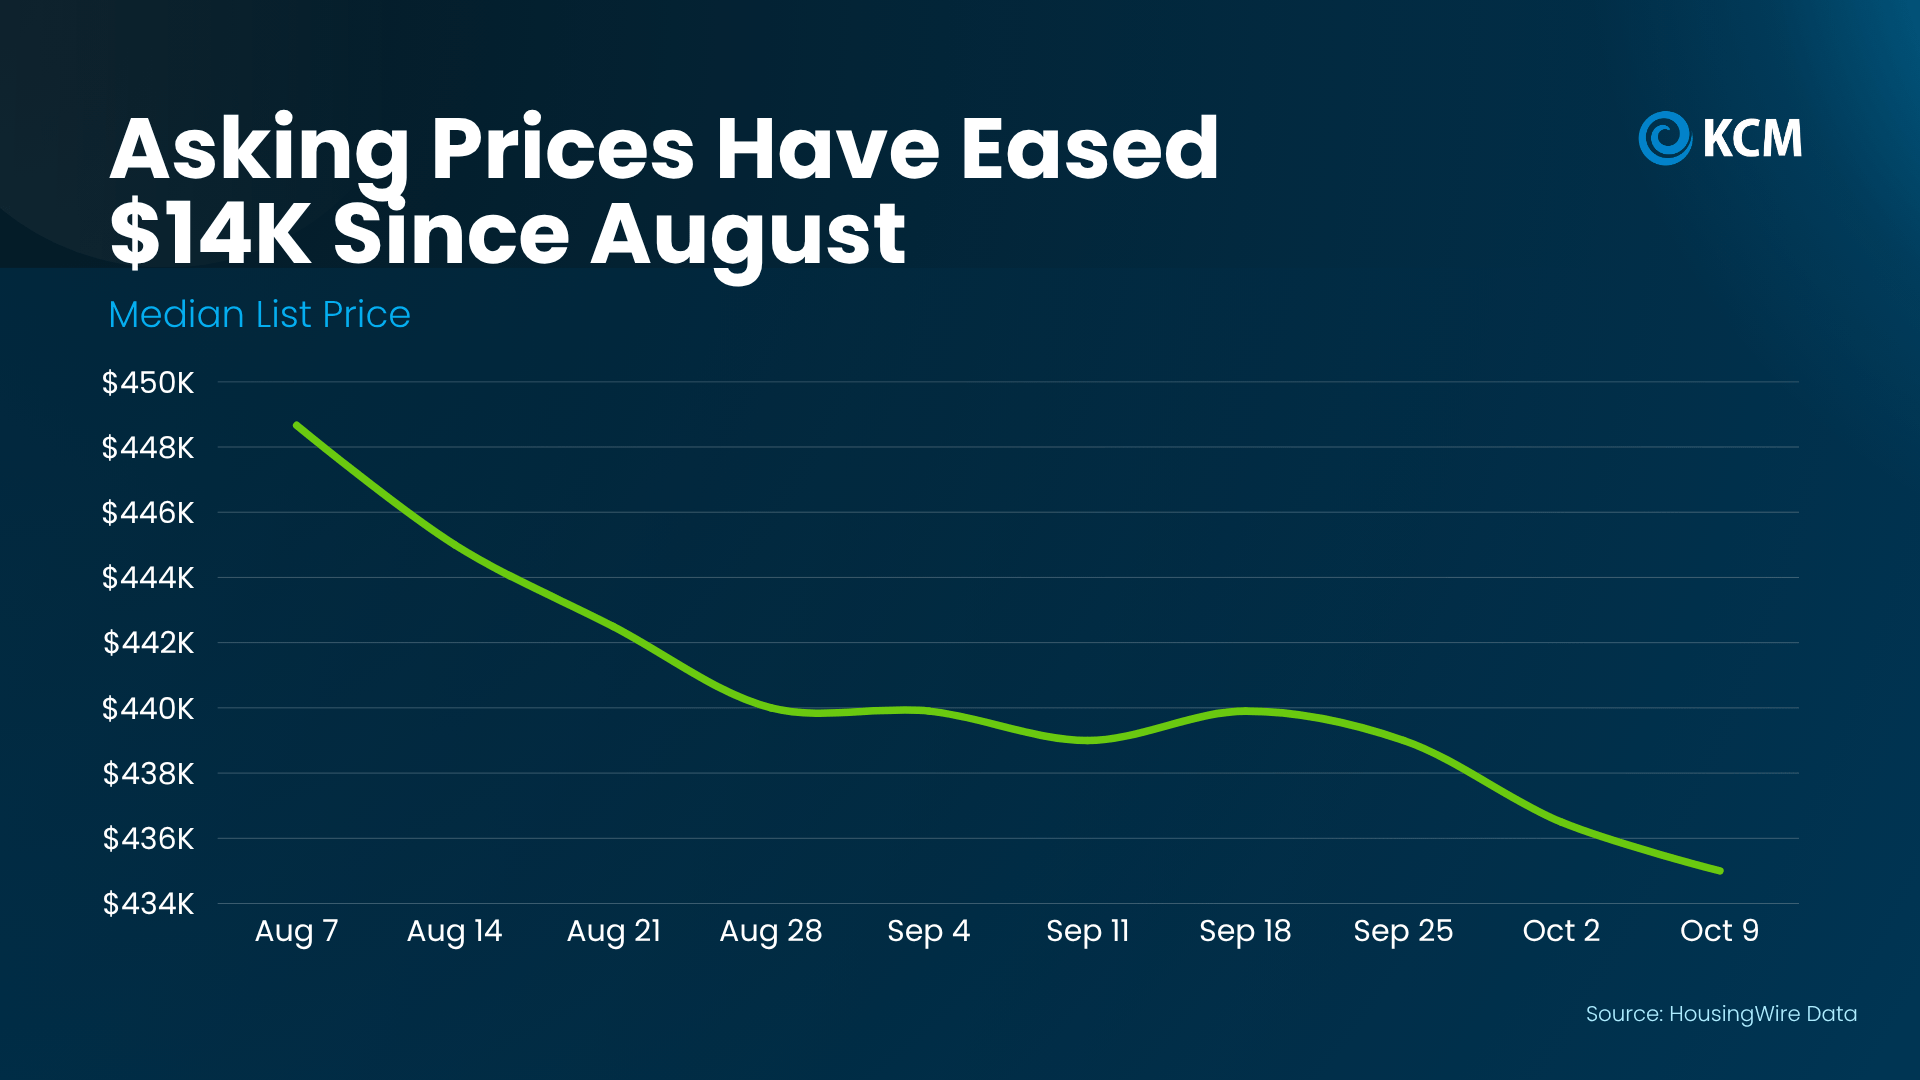
That’s a dip of about 3%, and a lot of it is normal for this time of year.
Asking prices cool off every fall once the busy summer season wraps up. With fewer buyers this time of year, sellers price a bit more competitively. Today’s rates play a role too, since sellers are pricing to match what buyers can afford right now. And that’s a good thing. Smart pricing helps homes sell.
Just keep in mind, that’s a national list price. It doesn’t show what homes near you are actually selling for. So before you react to a headline, ask a local agent what’s really happening in your area.
Where You Live Changes Everything
Realtor.com explains:
“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”
The latest numbers from S&P Cotality Case-Shiller Index show how true that is. Over the past year, sales prices in Chicago rose almost 7%. In Seattle, they dipped about 1.6%. That’s a gap of nearly 9 percentage points between two major cities (see graph below):
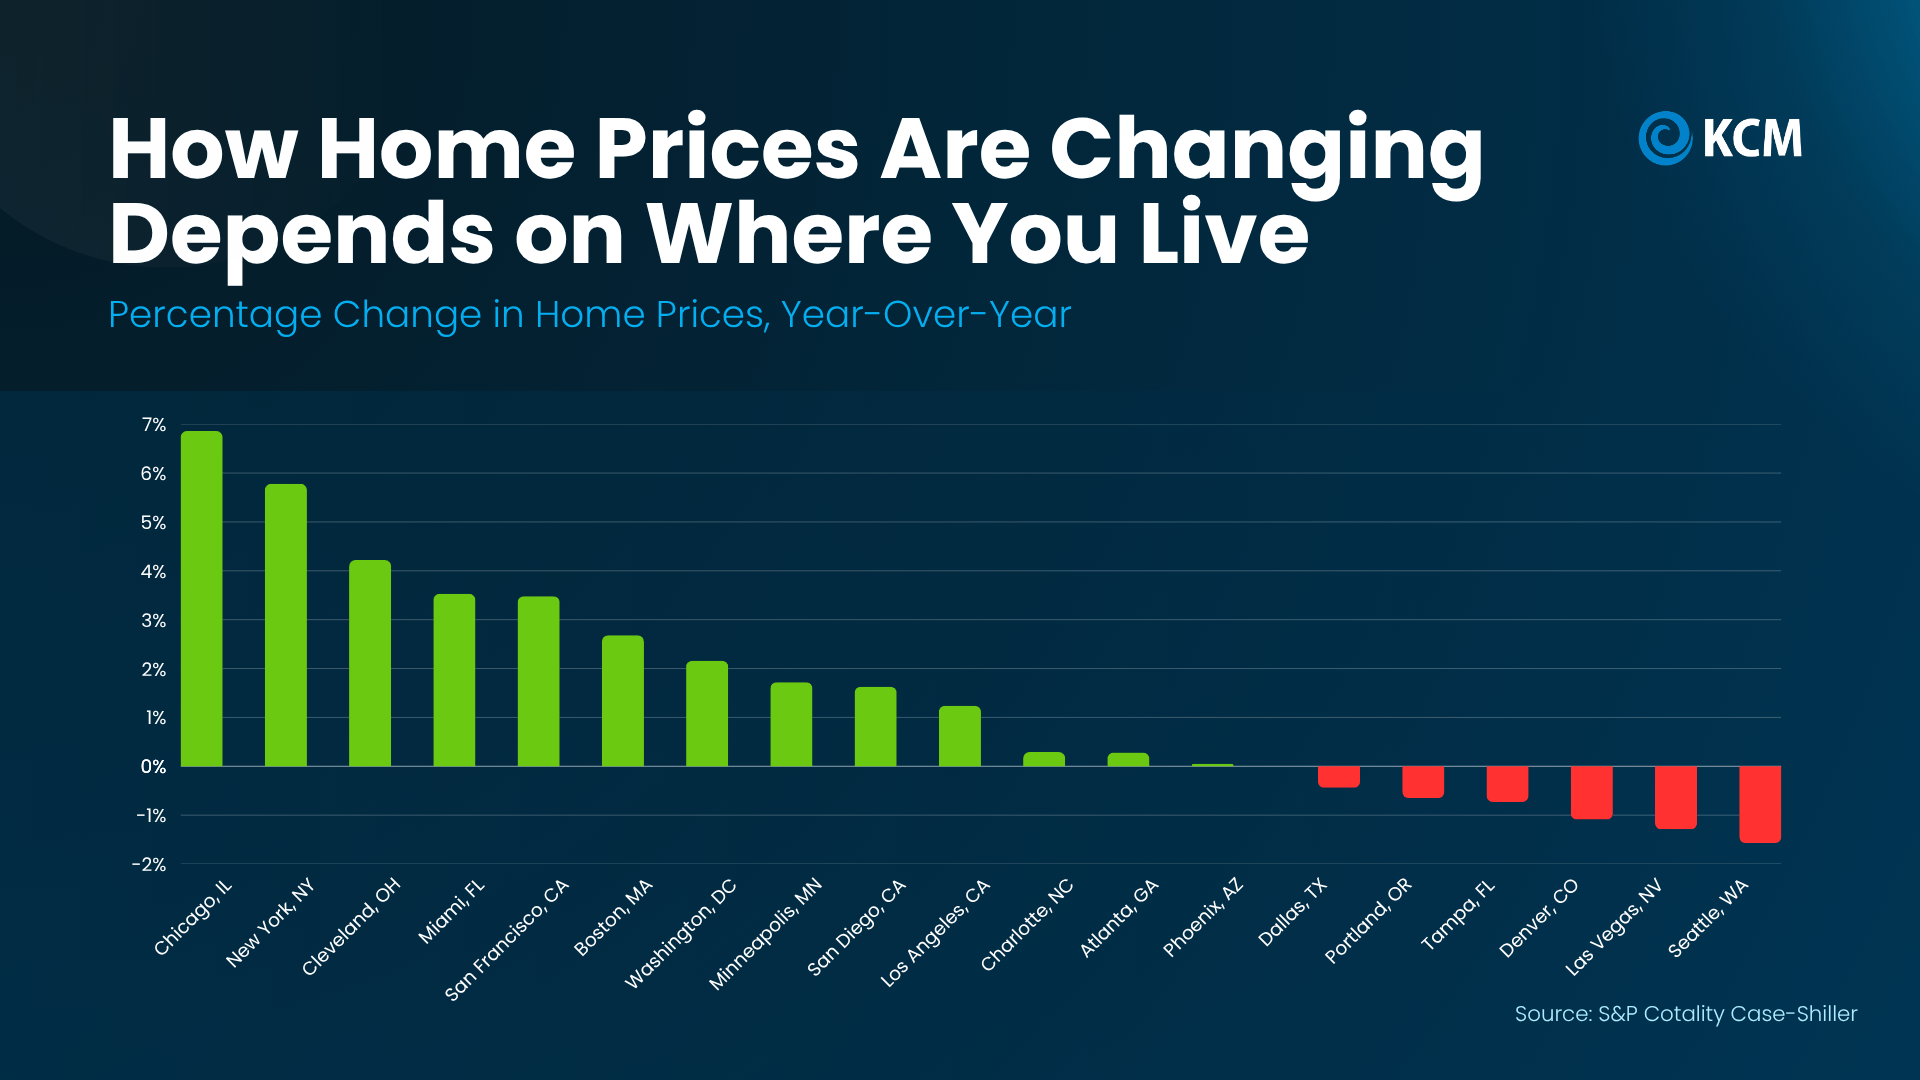
That gap changes your game plan. Selling in New York, where prices are up almost 6%? You may not need to cut your price. Buying in Denver or Las Vegas? You may have more room to negotiate.
Why You Don’t Need To Worry About a Crash
Just in case you’re seeing those slight declines in some markets and worried it means a bigger crash is coming, here’s what you need to remember. Even in the major metros where prices are down, the declines are 2% or less. That’s a long way from a crash like 2008. And if you look back at the graph above, there are more cities in the green than in the red.
And over time, home values have a strong track record. The Federal Housing Finance Agency (FHFA) says national prices have grown year-over-year every quarter since 2012. Go back further, and a $100k home bought in 1991 would be worth about $436k today, even with the 2008 crash factored in (see graph below):
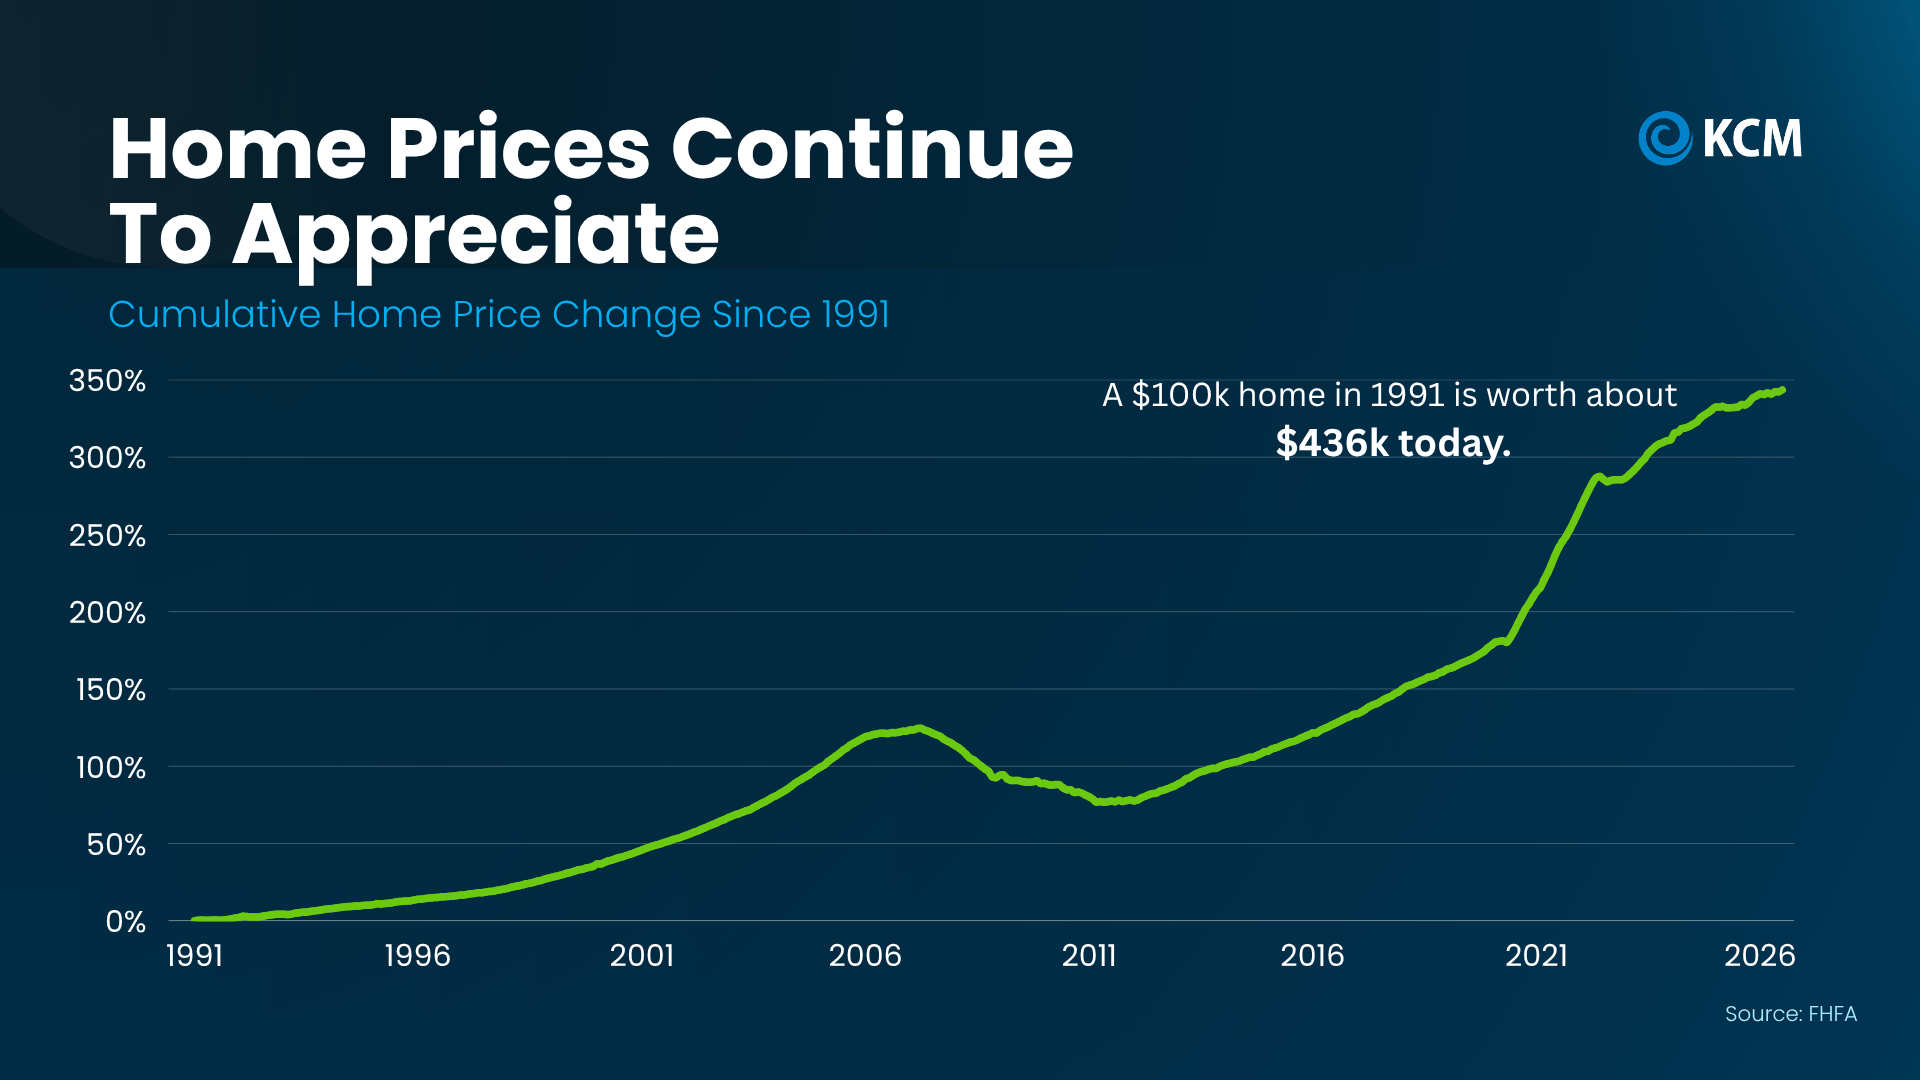
So, this short-term dip probably won’t stick around. The small declines we’re seeing now are in markets that overheated during the pandemic. As a whole, the market is headed back to normal – and normal means prices should rise over time.
Bottom Line
National headlines can’t tell you what your home is worth or how much room you have to negotiate. Local data can. If you’re thinking about buying or selling, connect with a local real estate agent to look at how prices are moving in your area, so you can set your price or make your offer with confidence.

Who’s Buying Homes with Cash Right Now?

Why Builders May Be More Motivated To Sell Than Homeowners

Why More Buyers Are Turning To Adjustable-Rate Mortgages Today


-
 Buying Tips4 weeks ago
Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.
-
 For Sellers4 weeks ago
What Higher Mortgage Rates Mean for Home Sellers
-
 Affordability3 weeks ago
Two Moves That Can Get You Into Your First Home Sooner
-
 Downsize3 weeks ago
Renovate or Relocate? What To Know Before You Decide To Age in Place
-
 Affordability3 weeks ago
Myth vs. Reality: Does the Fed Control Mortgage Rates?
-
 Affordability2 weeks ago
Why Most People Are Still Glad They Bought a Home
-
 Buying Tips2 weeks ago
The Biggest Credit Hurdle for Renters Who Want To Buy
-
 Buying Tips2 weeks ago
Why There are More Homes for Sale Right Now (and What It Means for You)
You must be logged in to post a comment Login